
How Investors May Respond To Ducommun Stock After PAC 3 Missile Contract
- Ducommun announced a follow-on agreement with Simmonds Precision Products worth over US$35 million to supply electronic assemblies for Lockheed Martin's PAC-3 missile family, manufactured at its Tulsa, Oklahoma performance center.
- This new PAC-3 award reinforces Ducommun's focus on higher value engineered defense content and supports its VISION 2027 effort to grow missile and munitions exposure.
- This article will explore how Ducommun's investment narrative is influenced by this expanded PAC-3 missile electronics work under its VISION 2027 plan.
Ducommun Investment Narrative Recap
To own Ducommun, you need to believe the push into higher value defense electronics, including missile content, can offset the drag from an unprofitable base and exposure to commercial aerospace cycles. The recent US$35 million PAC-3 award fits that story by reinforcing backlog and visibility, but it does not change the fact that Ducommun is still loss making today.
Right now, the near term swing factor is execution on facility consolidation, cost savings and mix shift toward engineered products, while managing transfers and recertifications without disruption. The biggest risk remains concentration in defense platforms and timing uncertainty around Boeing and Spirit AeroSystems build rates, which could still create choppy revenue and margin outcomes.
The PAC-3 electronics agreement from Simmonds Precision Products looks most relevant to the current Ducommun story. It ties directly into missile and munition exposure under VISION 2027 and leans into areas where the group has been highlighting strong order activity and higher value content within Electronic Systems.
For catalysts, this award contributes to the defense backlog that investors are watching alongside margin progress and automation benefits expected into 2025 and 2026. Execution risk does not go away though. Ducommun still has to integrate this extra PAC-3 workload smoothly into the Tulsa performance center while juggling facility consolidation and commercial aerospace volatility.
Ducommun's current narrative assumes revenue rising to US$1.1b and earnings reaching US$146.1 million by 2029. That path implies 8.4% yearly revenue growth and an earnings swing of about US$167.3 million from a loss of US$21.2 million today to the 2029 consensus figure.
Uncover why Ducommun's fair value indicates a 27% potential upside to its current price before that discount closes.
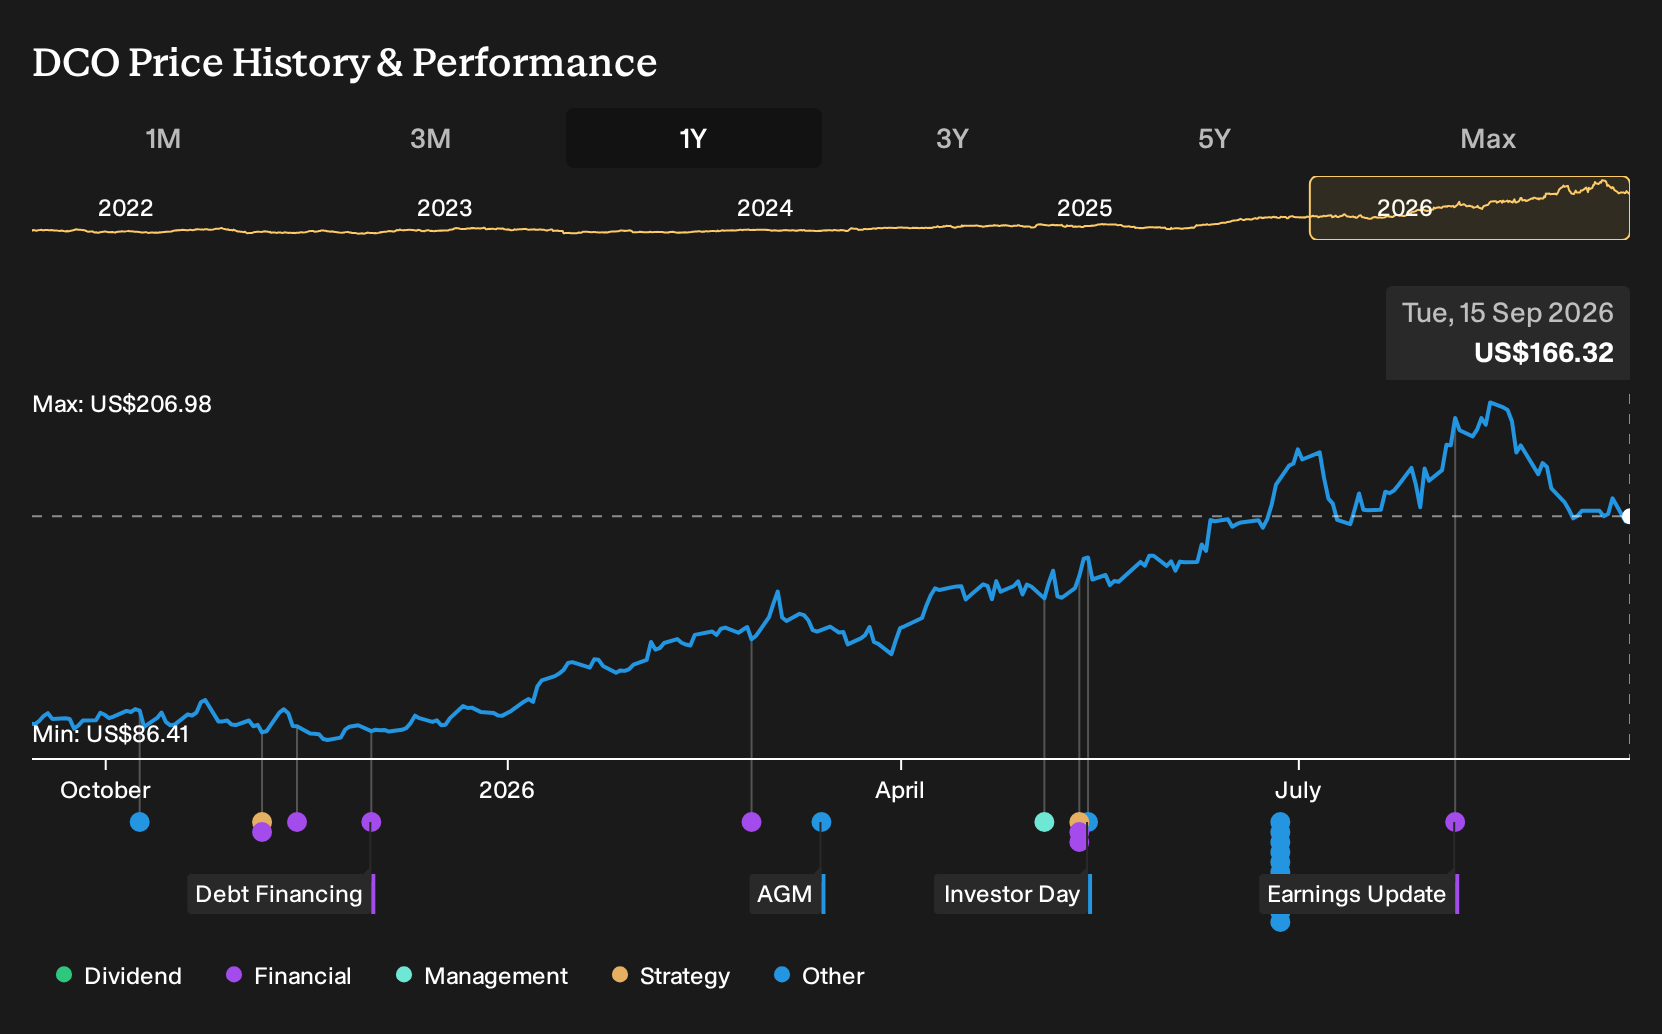
Exploring Other Perspectives
One optimistic twist in the alternate Ducommun story is missile driven operating leverage. The most bullish analysts were already penciling in about US$1.1b of revenue and US$142.6 million of earnings by 2029 before this PAC 3 update. You can treat this new award as a prompt to compare those upbeat expectations with more cautious views.
Explore 2 other Ducommun fair value estimates, including one that suggests up to 33% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ducommun research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Ducommun. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ducommun's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ducommun?
If the Ducommun story has you thinking about portfolio upgrades, it can help to cast the net wider and scan for other businesses that fit your risk, income, or value preferences using the Simply Wall St Screener.
- For investors who care most about resilience and capital preservation, you can focus on companies that score well on financial strength using our 11 resilient stocks with low risk scores.
- If reliable balance sheets matter more to you than headline growth, narrow your watchlist to firms with clean leverage and solid fundamentals through the list of solid balance sheet and fundamentals (22 results).
- For those hunting for underappreciated opportunities with stronger fundamentals than their share prices suggest, filter the market using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com