
Conagra (CAG) Stock Looks Below Fair Value As Sales Stay In Focus
Conagra Brands has seen its share price slide in recent years, while management reshapes the business and leans into ideas like “GLP-1 friendly” frozen meals. That mix of weak share returns and shifting demand leaves a clear question for investors who focus on numbers. Is the current US$15.02 price tag adequately supported by Conagra Brands' sales.
- Over the past 5 years the stock has fallen about 41.1%, which puts the spotlight firmly on whether the revenue base is strong enough to support the current valuation.
- The move to label some Healthy Choice products as “GLP-1 friendly”, alongside a recent dividend cut and investment in brands and the supply chain, may influence how much sales growth and profitability investors are willing to bake into the price.
- Your read on Conagra Brands is one view; the desks covering it have another. See what analysts think Conagra Brands's shares could be worth.
The issue now is whether the stock price investors see today is justified by the sales Conagra Brands is generating and expected to produce.
If you are questioning whether Conagra Brands' US$15.02 share price is properly anchored to its sales, it can help to compare that same lens across 34 high quality undervalued stocks
Does Conagra Brands Look Undervalued on Sales?
P/S is a clean way to look at Conagra Brands because sales are still positive while earnings and cash flow are working through impairments and restructuring noise.
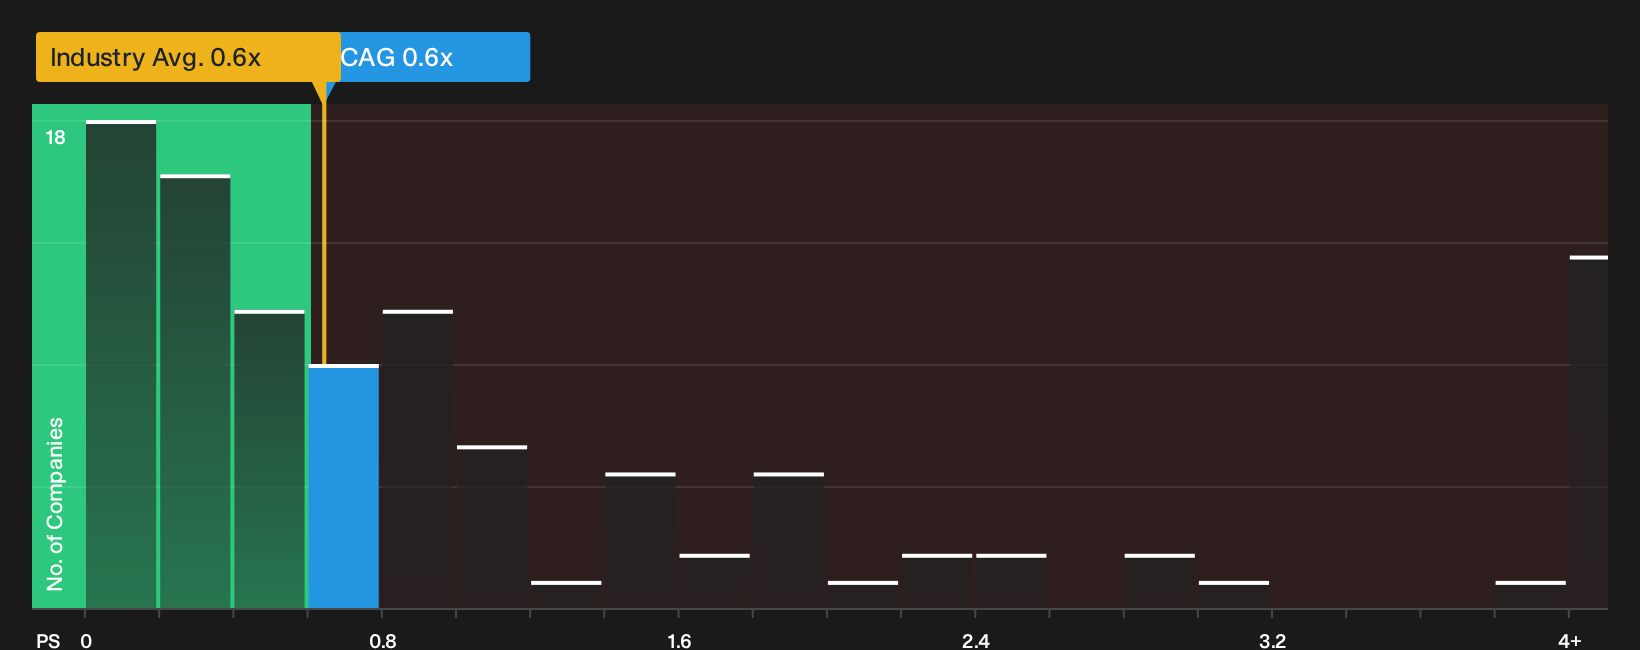
On this lens, Conagra Brands trades on a P/S of about 0.6x, which is almost identical to the broader Food industry average of roughly 0.6x and very close to peers at about 0.6x as well. Based on the fair multiple implied by its own mix of margins, growth profile, size and risk, the current P/S sits below where the model would usually place a business like this. This points to the shares screening as undervalued on sales. Because the recent net loss and dividend cut stem in part from non cash charges and a reset of capital allocation, the P/S framework is effectively saying the stock price does not yet ascribe a premium for those brand and supply chain investments. Despite the push into “GLP-1 friendly” products and heavier marketing spend, the valuation on revenue still looks compressed next to the tailored fair multiple. This is where that potential opportunity or risk for you really lies. Explore the numbers behind Conagra Brands's P/S valuation.
The Conagra Brands Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Conagra Brands leaves off by spelling out what would need to happen to growth, margins and earnings for the stock to be worth materially more or less than today’s price, and they sit on the company’s Community page. Rather than giving you a single model output, each scenario lays out the assumptions behind its fair value so you can test those inputs against future results as they are reported.
Community views on Conagra Brands split around whether today’s price reflects a reset opportunity or signals more pressure ahead.
Bull case: 23% undervalued
"Conagra's focused innovations around "better-for-you" and health-oriented product categories, particularly recent moves in protein-centric and plant-based snacks and frozen meals, position the company to capture outsized market share..."
Discover why this Narrative puts Conagra Brands at 23% undervalued.
Bear case: 25% overvalued
"The ongoing consumer shift toward fresh and minimally processed foods threatens to erode long-term demand for Conagra's core frozen and packaged offerings, increasing the risk of declining sales..."
Explore why this Narrative puts Conagra Brands at 25% overvalued.
The share price is only one piece of the Conagra Brands puzzle
Valuation tells you what the market is willing to pay today, but the projections for where Conagra Brands could be a few years from now give a very different lens to compare against that sticker price. Explore where analysts expect Conagra Brands to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com