
Hyatt Hotels (H) Shares Dropped, What Is Behind The Fresh Attention?
Why the new Delta partnership matters for Hyatt investors
Hyatt Hotels (H) has moved into the spotlight after announcing a long term loyalty collaboration with Delta Air Lines. The agreement links World of Hyatt and SkyMiles rewards across flights and hotel stays.
The tie up is set to roll out in the coming months, initially aimed at elite members of both schemes. Investors are watching how this could influence Hyatt Hotels shares, customer behavior and future earnings power.
Hyatt Hotels shares trade at US$160.19 after a pullback, with the 30 day share price return down 11.49% and the 90 day share price return down 20.65%, even as the 1 year total shareholder return sits at 12.13% and the 5 year total shareholder return reaches 120.66%. This suggests that longer term holders have still seen strong compounding, while near term momentum has faded despite the new Delta loyalty announcement.
Scan beyond Hyatt Hotels and this Delta tie up by sizing up premium travel peers screened for stronger fundamentals with the list of solid balance sheet and fundamentals (22 results).
Hyatt Hotels appears to be a powerful hospitality platform tied to a fresh airline partner, yet the share price already reflects years of strong total returns. Is this still a solid business at a fair tag today, or a premium story priced accordingly?
Most Popular Narrative: 19% Undervalued
Compared with the most followed narrative fair value of $197.78, Hyatt Hotels at $160.19 appears meaningfully cheaper, which is why investors are paying close attention to how loyalty expansion and asset sales could reshape the story.
The sale of Playa's real estate, along with other owned properties, is anticipated to reduce Hyatt's ownership of hotels. This aligns with its asset-light strategy and could affect net margins by lowering capital expenditure and maintenance costs.
The development pipeline, with approximately 138,000 rooms and several new signings in diverse locations such as India, Italy, and the U.S., is expected to influence revenue as these new properties come online.
See why 6 investors see Hyatt Hotels as 19% undervalued.
Result: Fair Value of $197.78 (UNDERVALUED)
Still, the narrative can be knocked off course if slower upscale bookings persist or if economic volatility and financing conditions affect Hyatt Hotels development plans.
Find out about the key risks to this Hyatt Hotels narrative.
Another view on Hyatt Hotels valuation
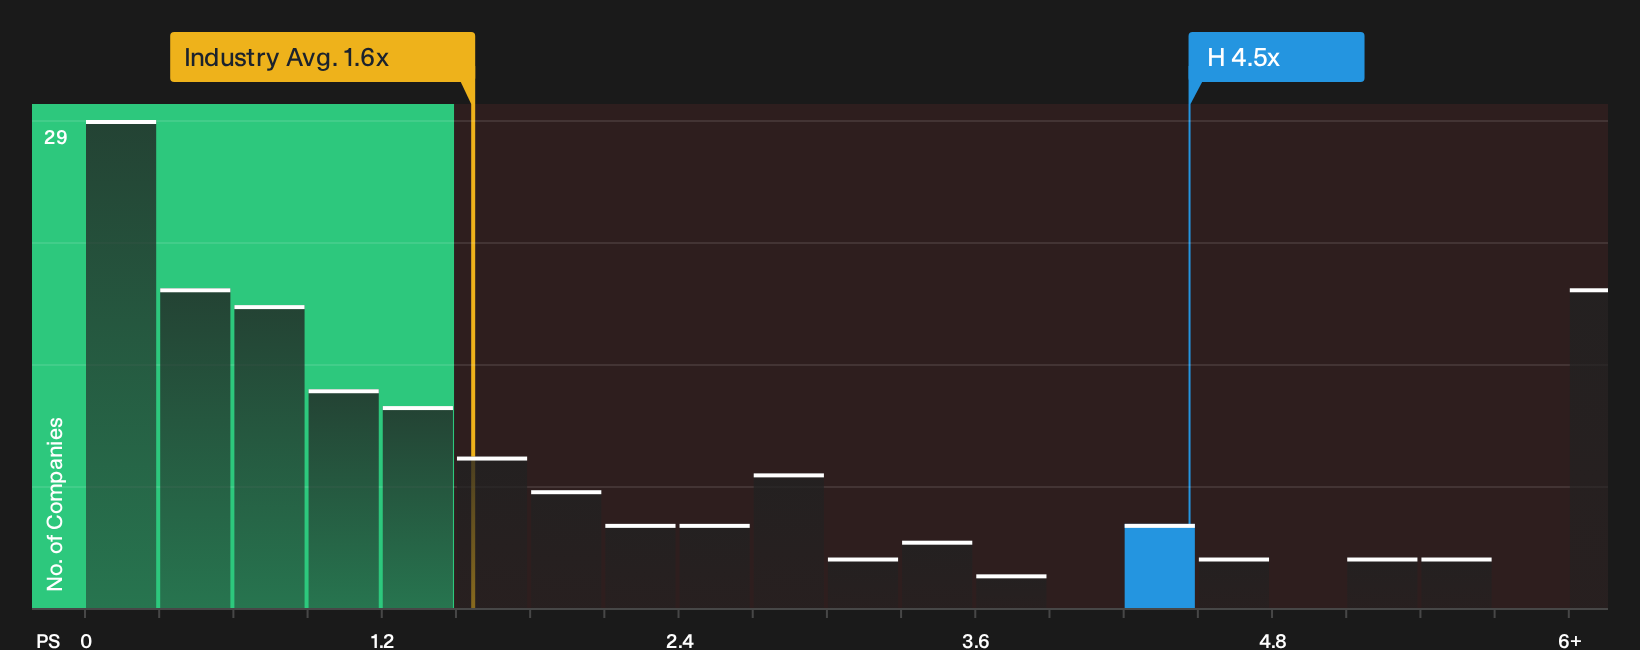
The narrative fair value suggests Hyatt Hotels could be 19% undervalued, yet the pricing signal from sales per share tells a different story. The stock trades on a P/S ratio of 4.5x, while the US Hospitality sector averages 1.7x and Hyatt Hotels own fair ratio is 3.8x.
That gap implies investors are already paying a premium for the brand and its loyalty story, which reduces any margin for error if forecasts or travel demand disappoint. The real question is whether you are comfortable paying above both peers and the fair ratio for this kind of growth profile.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed views on whether Hyatt Hotels is currently priced for optimism or caution. Move quickly, review the data, and weigh the 2 key rewards and 4 important warning signs.
Looking for more ideas beyond Hyatt Hotels?
If Hyatt Hotels has you thinking harder about price, quality and risk, do not stop here. Use focused screeners to surface fresh candidates before the crowd.
- Hunt for quality at a discount by scanning the 34 high quality undervalued stocks that blend solid fundamentals with pricing that still looks appealing.
- Anchor your portfolio with steady income and capital discipline by zeroing in on the 6 dividend fortresses that pass strict payout and balance sheet checks.
- Cut down portfolio risk by filtering for the 11 resilient stocks with low risk scores that combine resilient finances with calmer share price behavior.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com