
3 U.S. Financial Stocks That Could Benefit If Higher Rates Stay Put
Markets are being reshaped in real time as higher U.S. rates, a 10-year Treasury at levels last seen in 2007, and fresh geopolitical and energy shocks pull money away from some corners of Wall Street and toward others. That creates both openings and traps. This article walks through three U.S. Interest-Rate Beneficiaries from our screener, each tightly linked to these headlines, to help you decide which stories deserve a closer look.
The companies covered below are only a small sample, and the full screen surfaced 38 more U.S.-listed banks, insurers and financial firms with equally compelling rate-sensitive narratives that are not unpacked in this article. To sort through them efficiently, head straight to the U.S. Interest-Rate Beneficiaries (Banks and Other Financials) screener to identify, analyze, and focus on the interest-rate beneficiaries that best fit your own approach.
Victory Capital Holdings (VCTR)
Overview: Victory Capital Holdings is an asset manager offering a wide range of investment products to institutions, intermediaries, retirement platforms, and individual investors. This ties it closely to interest-rate driven rotations across financial markets.
Operations: Victory Capital generates about US$1.6b in revenue from providing investment management services and related products across its platform.
Market Cap: US$6.7b
Victory Capital Holdings provides exposure to a diversified asset manager whose cash economics and product mix are closely linked to higher-rate financial conditions.
"The First Eagle deal is expected to close in the first half of 2025, subject to regulatory approvals and customary conditions, and reflects continued consolidation in asset management as fee pressure affects the sector."
What happens to Victory Capital Holdings’ earnings power if a single assumption about future fee pressure and cost discipline changes?
If that earnings lever is what matters most to you, the full narrative for Victory Capital Holdings shows how fee pressure, scale and integration could still reshape Victory Capital’s trajectory.

Invesco (IVZ)
Overview: Invesco is a global investment manager that builds and runs funds and portfolios for individuals, institutions and retirement savers across asset classes.
Operations: Invesco generates about US$6.9b in Investment Management revenue, with roughly US$5.2b from the Americas and the rest from APAC and EMEA.
Market Cap: US$13.9b
Invesco fits this interest-rate beneficiaries screen because rising yields and stronger financials can influence where clients allocate assets across its platform. This in turn shapes fee income and operating leverage when conditions improve.
"Strategic partnerships and global expansion enable Invesco to lead in alternative investments and emerging markets, potentially transforming its growth and profitability outlook."
What happens to Invesco’s margins and fee resilience if a single assumption about how clients shift toward higher-yield products proves wrong?
When that assumption breaks, full narrative for Invesco shows where Invesco’s fee mix, capital flexibility and overlooked earnings drivers could still be quietly accelerating.

Kearny Financial (KRNY)
Overview: Kearny Financial is a New Jersey based community bank offering traditional deposit accounts, loans and related financial services that tie directly into changing U.S. interest rates.
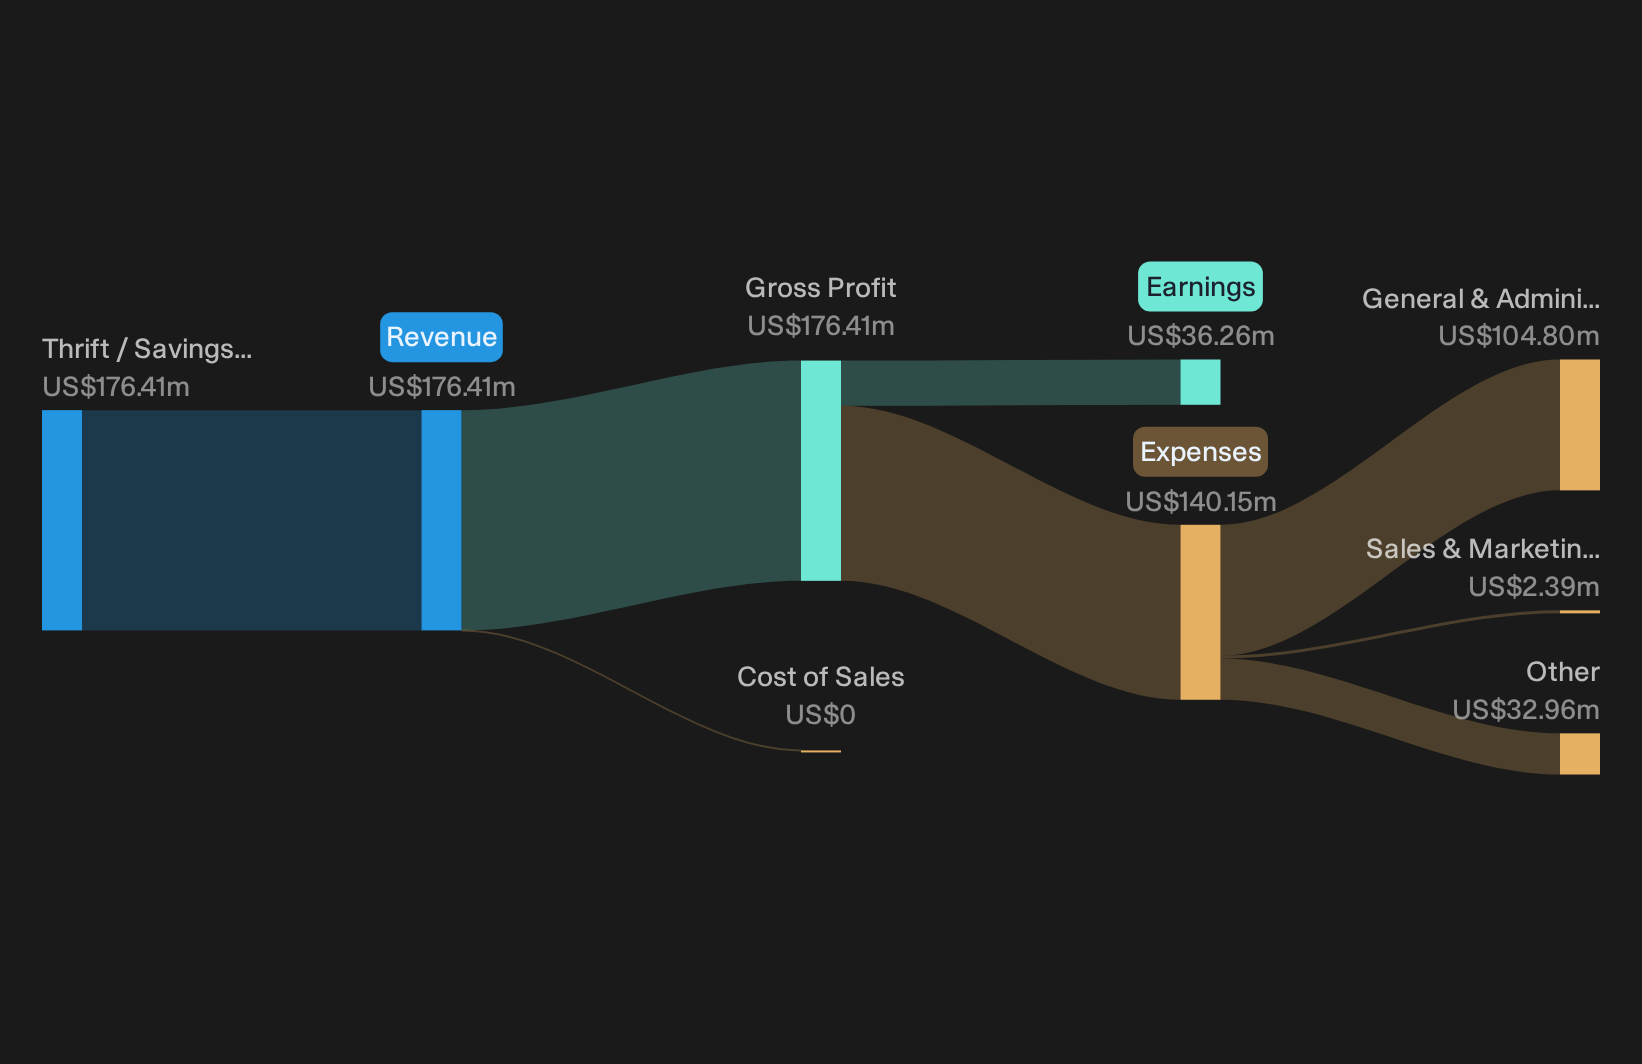
Operations: Kearny Financial generates about US$176 million of thrift and savings institution revenue entirely from customers in the United States.
Market Cap: US$618 million
Kearny Financial provides exposure to a traditional U.S. lender whose net interest income is closely linked to higher rates, with 2026 net interest income at US$155.28 million and net profit margin at 20.6%. The appeal depends on what happens when one unseen pressure on those rate driven margins shifts direction.
When that margin pressure finally bites, the analysis report for Kearny Financial reveals whether Kearny Financial’s 2026 income and net profit margin are masking deeper risks or a cleaner reset
Seeking Fresh Alternatives Before They Fly
New themes are breaking out while yesterday’s favorites risk dropping out of focus. Scan fresh stock ideas before the crowd, while it matters, and get in early.
- Spot cash generative businesses early and review a curated list of solid balance sheet and fundamentals (22 results) that keeps financial resilience front and center before momentum really starts flying.
- Track income workhorses in real time and scan the hand picked 6 dividend fortresses while yields remain under the radar for now, then position with confidence.
- Ride structural demand shifts and inspect the focused 38 power grid technology and infrastructure stocks while infrastructure upgrades are still underappreciated and before capital floods into the same opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com