
Dropbox (DBX), What Is Behind The Fresh Attention Now?
Dropbox (DBX) drew attention after Chief Financial Officer Ross Tennenbaum sold 97,558 Class A shares on 10 September 2026 under a pre-set Rule 10b5-1 trading plan adopted in June.
Against that backdrop, Dropbox shares have been on a strong run, with a 7-day share price return of 11.3% and a 90-day share price return of 42.5% contributing to a 39.7% year-to-date move. The 1-year total shareholder return of 17% points to momentum that has built over time rather than appearing overnight.
See how Dropbox fits into the wider momentum story by reviewing a hand-picked set of 34 high quality undervalued stocks that combine recent strength with solid fundamentals.
Dropbox now appears to be a profitable, global subscription business with a strong platform and a share price that has moved sharply higher. Does that recent surge leave the stock fairly valued, or stretched?
Most Popular Narrative: 23% Overvalued
Dropbox closed at $37.63, while the most followed narrative pegs fair value around $30.67. The recent rally now leans ahead of that framework even as it credits the business with steady profitability and strong cash generation.
Persistent emphasis on operational efficiency via infrastructure optimization, disciplined hiring, and lower marketing spend has resulted in sustained improvements in non-GAAP operating margins and free cash flow. This has enhanced the company's ability to invest in long-term growth areas while also supporting increasing earnings and cash flow per share. Increasing focus on data security, privacy, and third-party integrations with platforms like Slack, along with ongoing investments in backend improvements, aligns Dropbox with evolving industry-wide regulatory demands and enterprise expectations. This strengthens its competitive positioning for large, security-conscious customers and provides a foundation for stable enterprise revenue and longer-term margin improvement.
See why 10 investors see Dropbox as 23% overvalued.
Result: Fair Value of $30.67 (OVERVALUED)
Still, the recent decline in total revenue and annual recurring revenue, along with pressure on ARPU from lower-priced plans, could quickly challenge the Dropbox optimism narrative.
Find out about the key risks to this Dropbox narrative.
Another View On Dropbox Valuation
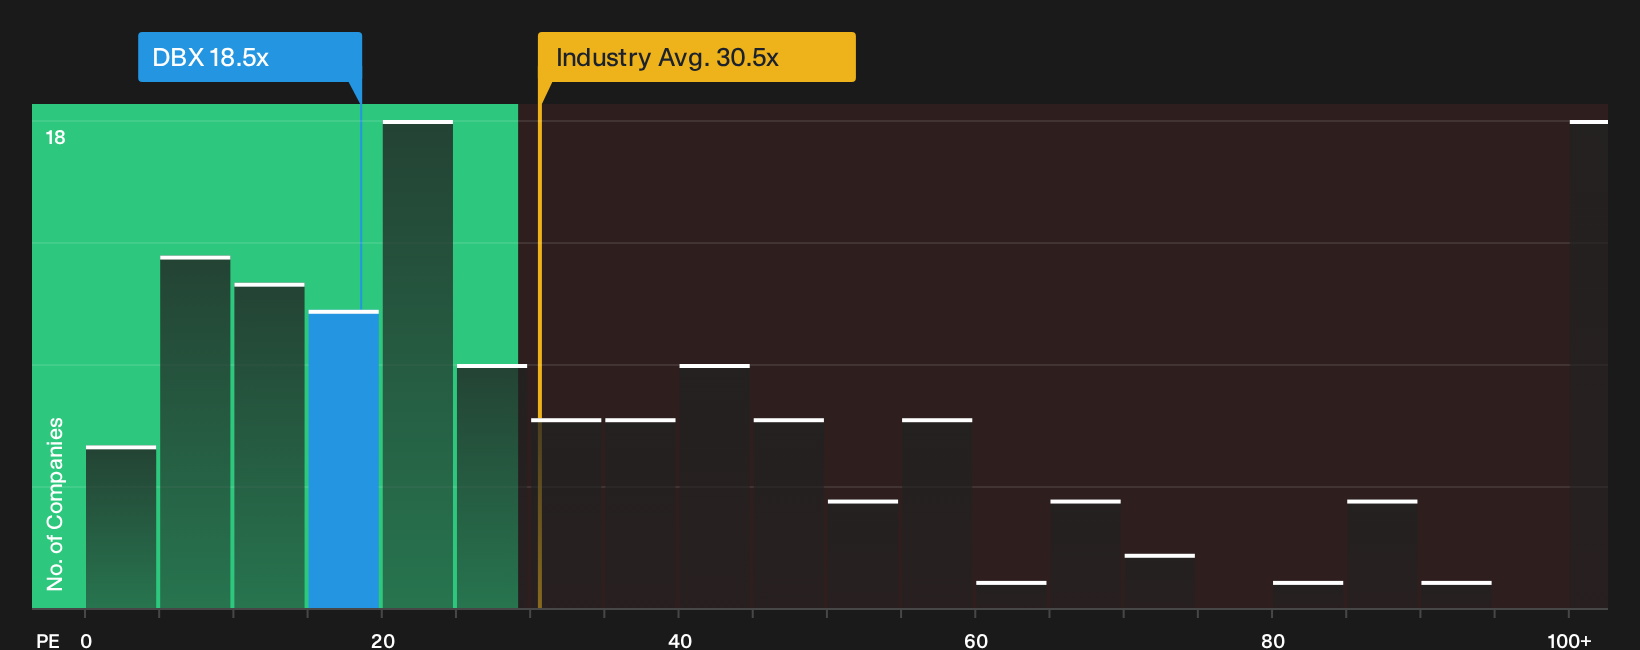
The narrative fair value of $30.67 frames Dropbox as 23% overvalued, yet the market is also looking at plain P/E math. On that score, DBX trades at 18.5x earnings versus a fair ratio of 22.6x and a US Software peer average of about 30x. That gap points to meaningful valuation risk if the narrative is right, but also scope for rerating if earnings hold up and sentiment swings. Which lens do you trust more when the numbers disagree?
See what the numbers say about this price, and find out in our valuation breakdown.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Dropbox is clearly split, with enthusiasm around profitability offset by concerns about slowing revenue trends and plan mix. Act quickly. Review the full picture and weigh both sides through 2 key rewards and 3 important warning signs
Looking For More Investment Ideas Beyond Dropbox?
Do not stop at Dropbox. If you only focus on one ticker, you could miss out on other opportunities that better fit your goals and risk comfort.
- Target higher potential upside in smaller companies by scanning a focused set of 2 elite penny stocks with strong financials with stronger financial profiles than the typical micro-cap story.
- Strengthen your core holdings by reviewing a curated list of solid balance sheet and fundamentals (22 results) that can help anchor a portfolio when conditions get choppy.
- Seek underappreciated opportunities by working through a 16 high quality undiscovered gems that pairs quality fundamentals with limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com