
Does Extended FDA Review Change The Bull Case For Exelixis (EXEL)?
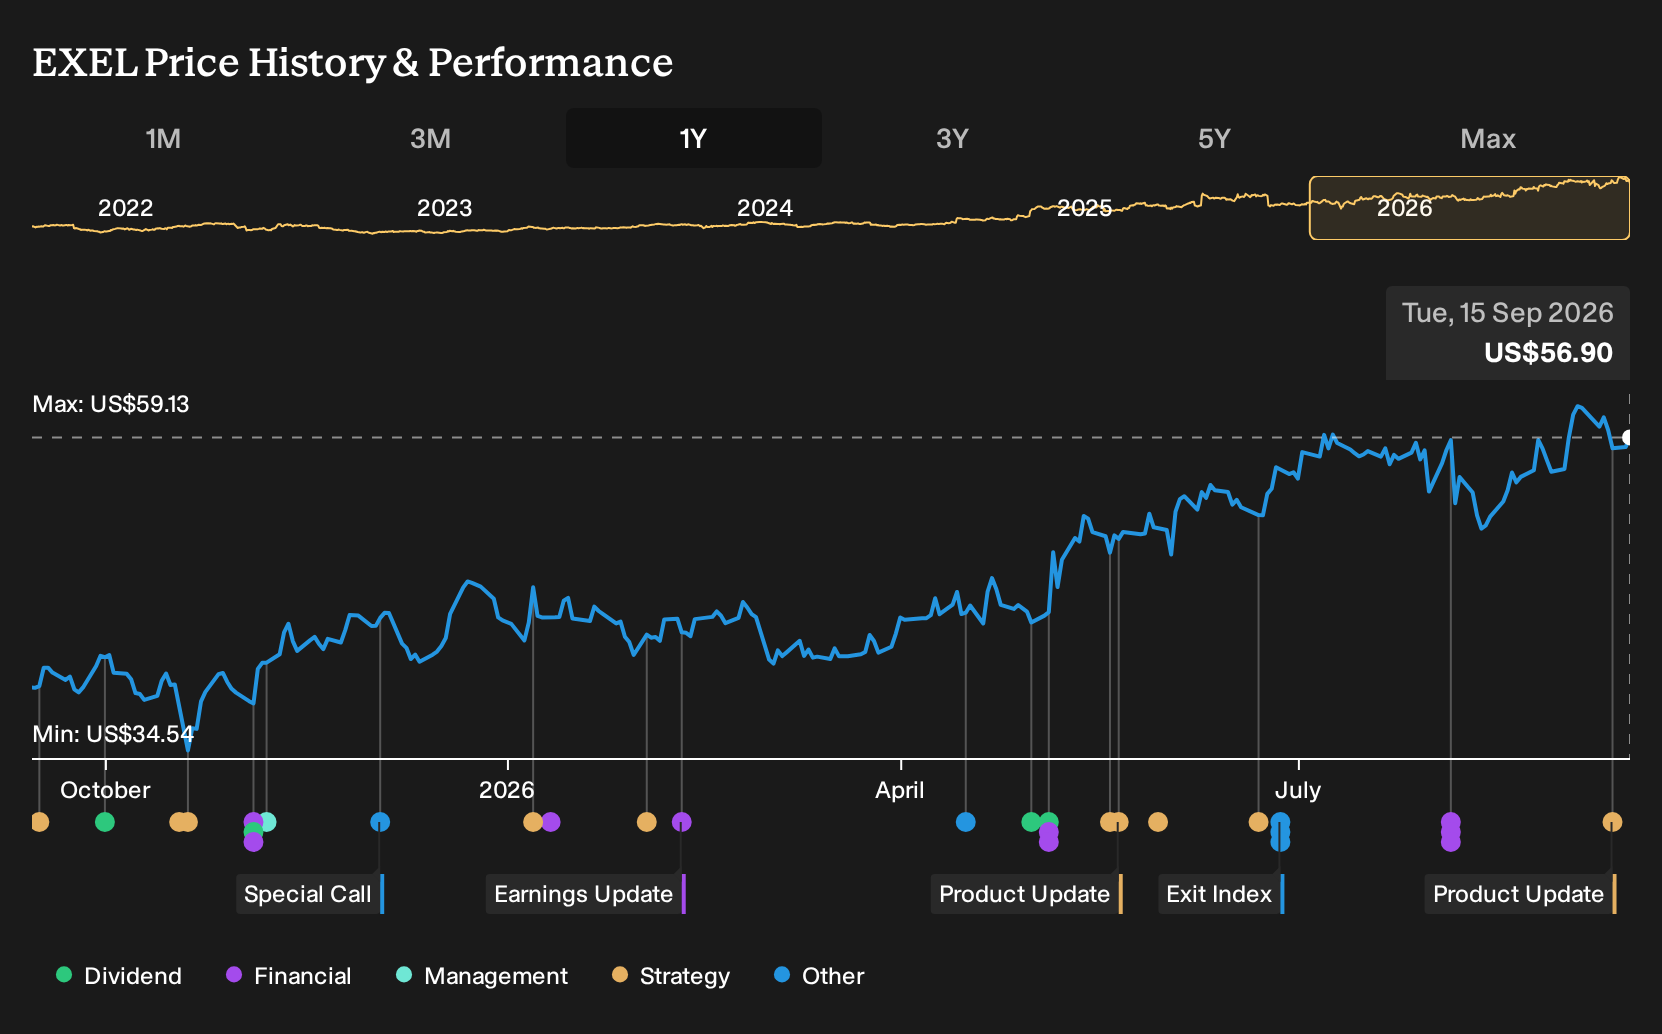
- On September 10, 2026, Exelixis reported that the FDA extended review of its zanzalintinib plus atezolizumab NDA for metastatic colorectal cancer by three months after updated safety and efficacy data were classified as a major amendment, moving the action date to March 3, 2027.
- The FDA’s request for and assessment of new zanzalintinib data puts renewed attention on Exelixis’ regulatory risk, clinical profile, and the timing of its efforts to diversify beyond the existing CABOMETYX franchise.
- Next, we examine how Exelixis’ investment narrative is affected by the extended FDA review timeline for zanzalintinib in colorectal cancer.
Scan beyond Exelixis and see how other oncology focused stories are setting up right now through our curated list of 16 high quality undiscovered gems.
Exelixis Investment Narrative Recap
For an Exelixis shareholder, the core belief is that CABOMETYX can keep supporting the business while zanzalintinib and other assets gradually reduce reliance on a single drug. The extended FDA review for zanzalintinib adds time but not a clear new hurdle, so the most important near term catalyst remains that colorectal decision.
The biggest risk still sits with CABOMETYX concentration and margin pressure from 340B discounts and pricing pressure. If future exclusivity, competition in renal cell carcinoma or neuroendocrine tumors, or reimbursement trends break against Exelixis, the current growth profile and cash generation could become harder to sustain.
The clearest related update is management’s recent framing of Exelixis around a CABOMETYX franchise and a potential zanzalintinib colorectal launch. That plan highlights how much the business is leaning on deeper penetration in renal cell carcinoma and neuroendocrine tumors while zanzalintinib works through late stage development and the regulatory process.
With R&D running at about US$1b a year and a US$750m buyback in play, execution on trials and approvals carries real weight. Any change to zanzalintinib timing now interacts with that spending profile and with efforts to diversify revenue before CABOMETYX faces heavier competitive and policy headwinds.
Exelixis’ current analyst storyline points to revenues of US$3.3b and earnings of US$1.3b by 2029. That view assumes yearly top line expansion of 10.6% and an earnings increase of about US$439m from US$860.6m today.
Uncover why Exelixis' fair value indicates a 7% potential downside to its current price, creating a valuation premium that leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic Exelixis analysts focus on zanzalintinib as a future blockbuster, not just a support act to CABOMETYX. Before this FDA delay, the bullish camp was modeling about US$3.8b of revenue and US$1.5b of earnings by 2029. You can treat this review extension as a live test of how quickly those upbeat forecasts might shift.
Explore 4 other Exelixis fair value estimates, including one that suggests as much as 220% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Exelixis research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Exelixis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Exelixis' overall financial health at a glance.
Looking for more investment ideas beyond Exelixis?
If the Exelixis story has sharpened your thinking and you want to stress test your approach across other companies, the Simply Wall St Screener can help you quickly sort through businesses that fit your risk, income, or value preferences.
- For investors who care about quality first and volatility second, you can filter for resilient balance sheets and steady fundamentals with our list of solid balance sheet and fundamentals (22 results).
- If capital preservation is front of mind, you can reduce guesswork by focusing on companies that score well on stability metrics through the 11 resilient stocks with low risk scores.
- When the goal is finding value that the market might be overlooking, you can cast a wider net across fundamentally strong but less followed stocks using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com