
Bigger Credit Line Could Be A Game Changer For AutoNation (AN)
- AutoNation amended and restated its unsecured credit agreement in mid September 2026, lifting revolver capacity to $2.0b, expanding its accordion feature to $1.0b, keeping or reducing borrowing spreads, and extending the facility to September 2031 while maintaining leverage and interest coverage covenants.
- The larger, longer dated credit line gives AutoNation more room to fund store investments, acquisitions, and working capital without locking into long term fixed funding.
- Next, we consider how AutoNation's investment narrative could be affected by this larger, longer revolving credit facility.
Scan beyond AutoNation and see how other car retailers are using flexible funding by reviewing our hand picked list of solid balance sheet and fundamentals (22 results).
AutoNation Investment Narrative Recap
To own AutoNation you need to be comfortable with a car retailer that leans heavily on service, used vehicles, and its finance arm to support earnings, while facing real pressure from online and direct to consumer models. The bigger revolving credit facility does not change that core thesis. It simply gives more room to support store upgrades, the AutoNation USA rollout, and working capital around those existing priorities.
The key near term swing factor is execution in used vehicles and after sales, where margin pressure from digital competitors and EV adoption could bite if pricing or volumes soften. The credit agreement extension helps reduce near term refinancing noise but does not remove the structural risks around OEM channel shifts, agency models, and the potential drag on high margin service work.
The upcoming Gabelli 50th Annual Automotive Symposium in November, where AutoNation management is scheduled to present, looks relevant in light of this new credit line. Investors get fresh commentary on how the retailer intends to use a larger, longer revolver alongside its store footprint, digital tools, and AN Finance.
That forum also puts AutoNation side by side with peers on issues like tariffs, vehicle affordability, EV complexity, and autonomous features, which directly touch the main catalysts and threats. For anyone tracking the stock, what management says there about used vehicle economics, aftermarket resilience, and capital allocation may matter more than the headline increase from a US$1.9b to US$2.0b facility.
AutoNation's current earnings sit at US$679.0 million, with analyst forecasts pointing to US$816.2 million of earnings and US$29.9b of revenue by 2029. That outlook assumes 2.8% yearly revenue growth and an earnings increase of about US$137.2 million from earnings today.
Uncover how AutoNation's fair value indicates a 19% potential upside to its current price that could narrow quickly as expectations reset.
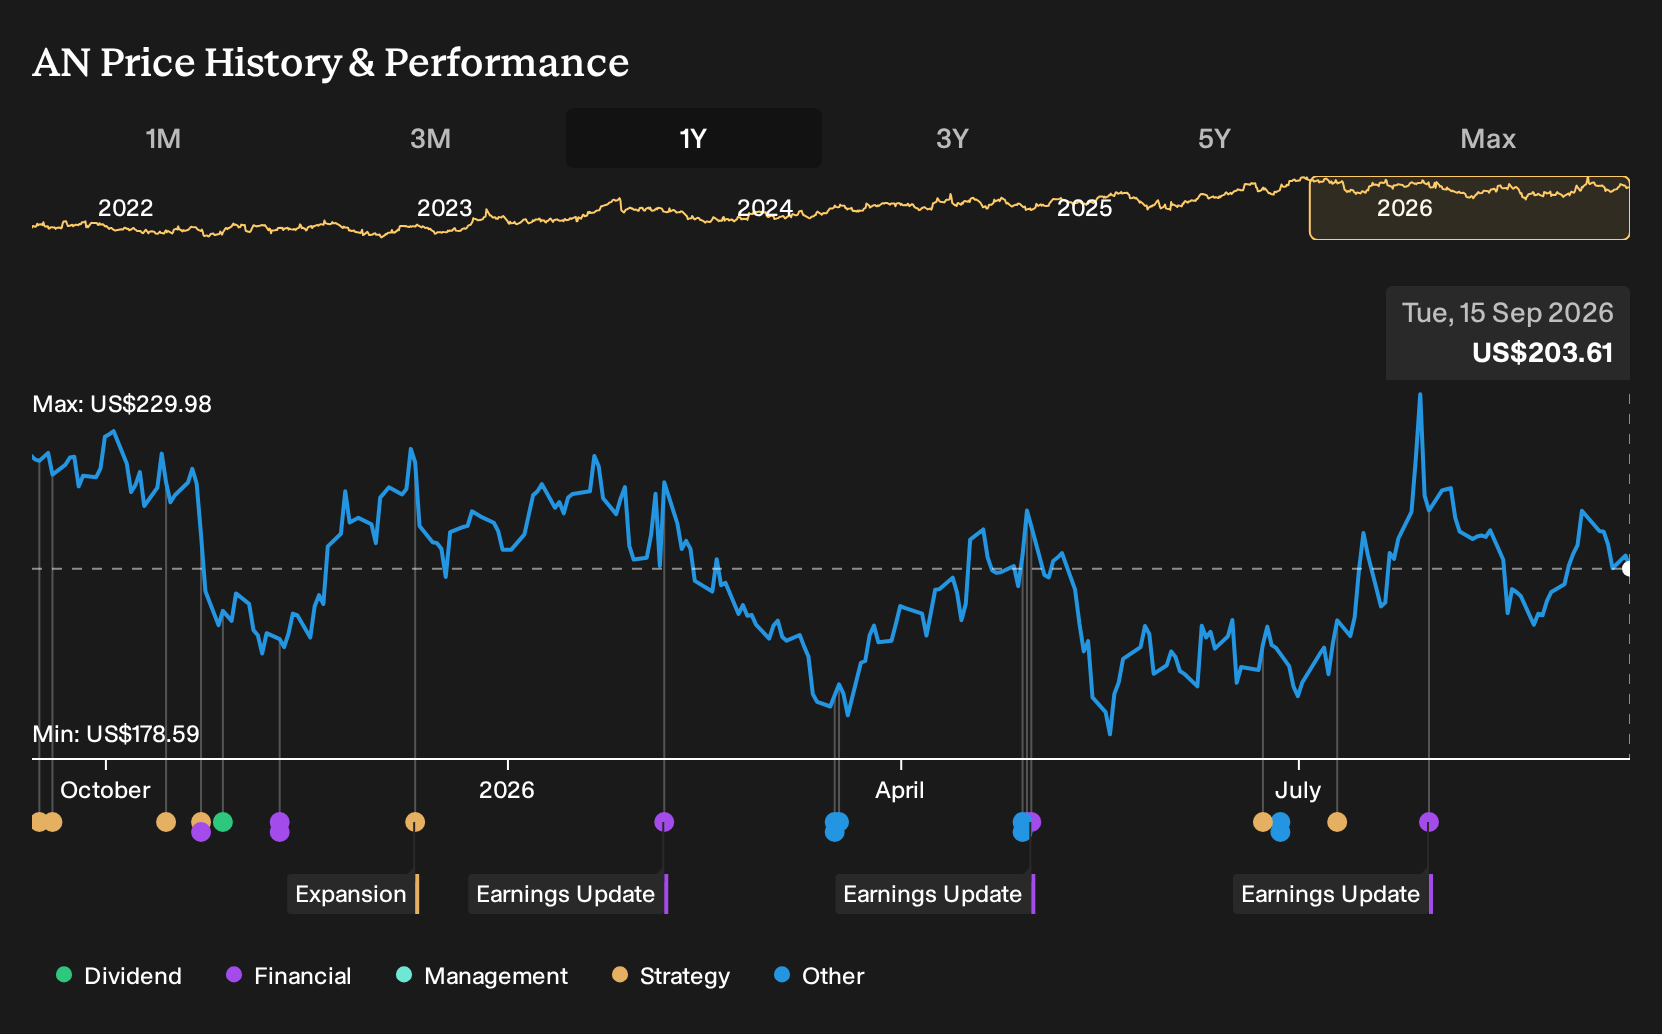
Exploring Other Perspectives
Some of the most optimistic analysts frame AutoNation’s expanding digital platform as the real swing factor. They were already modeling about US$31.5b of revenue and US$867.0 million of earnings by 2029, well above the consensus path, before this larger credit facility. Those views may evolve rather than converge as this funding move sinks in.
Explore another AutoNation fair value estimate, including one that suggests up to 19% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AutoNation research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AutoNation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AutoNation's overall financial health at a glance.
Looking For More Ideas Beyond AutoNation?
If you want to pressure test your view on AutoNation and broaden your watchlist, the Simply Wall St Screener can help you quickly scan for other businesses that fit the kind of balance sheets, income streams, and risk profile you care about.
- For investors who prioritize financial resilience and clean accounts, start with a list of solid balance sheet and fundamentals (22 results) that can handle different cycles without stretching the balance sheet.
- If you are hunting for quality at a sensible entry point, cast a wider net over 34 high quality undervalued stocks that currently combine solid fundamentals with prices that may not fully reflect them.
- Those looking for underfollowed opportunities can focus on 16 high quality undiscovered gems that pair strong business metrics with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com