
Castle Biosciences (CSTL) Draws Fresh Attention After TissueCypher Study As Valuation Debate Builds
Castle Biosciences (CSTL) is back in focus after new research on its TissueCypher Barrett's Esophagus test suggested the tool may better align Barrett's management decisions with individual patient risk profiles.
Recent trading suggests investors are reassessing Castle Biosciences. The 1-day share price return of 6.16% and 90-day share price return of 75.31% point to building momentum, while the year-to-date share price return is still down 7.89% and the 1-year total shareholder return of 63.22% highlights how sharply sentiment has swung over the past year.
Spot emerging momentum stories like Castle Biosciences by scanning our hand-picked 16 high quality undiscovered gems with solid fundamentals that may still be flying under most investors' radar.Castle Biosciences now carries a 63% 1-year total return and a move of more than 75% over 90 days. Is that mostly better appreciation for the business, or a sharp swing in sentiment that valuation needs to test?
Most Popular Narrative: 19% Undervalued
Against the last close at $35.50, the most widely followed narrative pegs Castle Biosciences' fair value at $44.00. This frames the recent price strength as only a partial catch up to its implied worth.
Progress toward broader reimbursement, including the ongoing reconsideration process for DecisionDx-SCC and the pursuit of new LCD policies for pipeline tests, has the potential to materially improve average selling prices and margin structure, driving stronger earnings and cash flow leverage over time.
See why 4 investors see Castle Biosciences as 19% undervalued.
Result: Fair Value of $44.00 (UNDERVALUED)
Still, reimbursement setbacks around DecisionDx-SCC and pressure from competing genomic and AI diagnostics could quickly challenge the current narrative for Castle Biosciences.
Find out about the key risks to this Castle Biosciences narrative.
Another View: Market Pricing Versus Fair Ratio
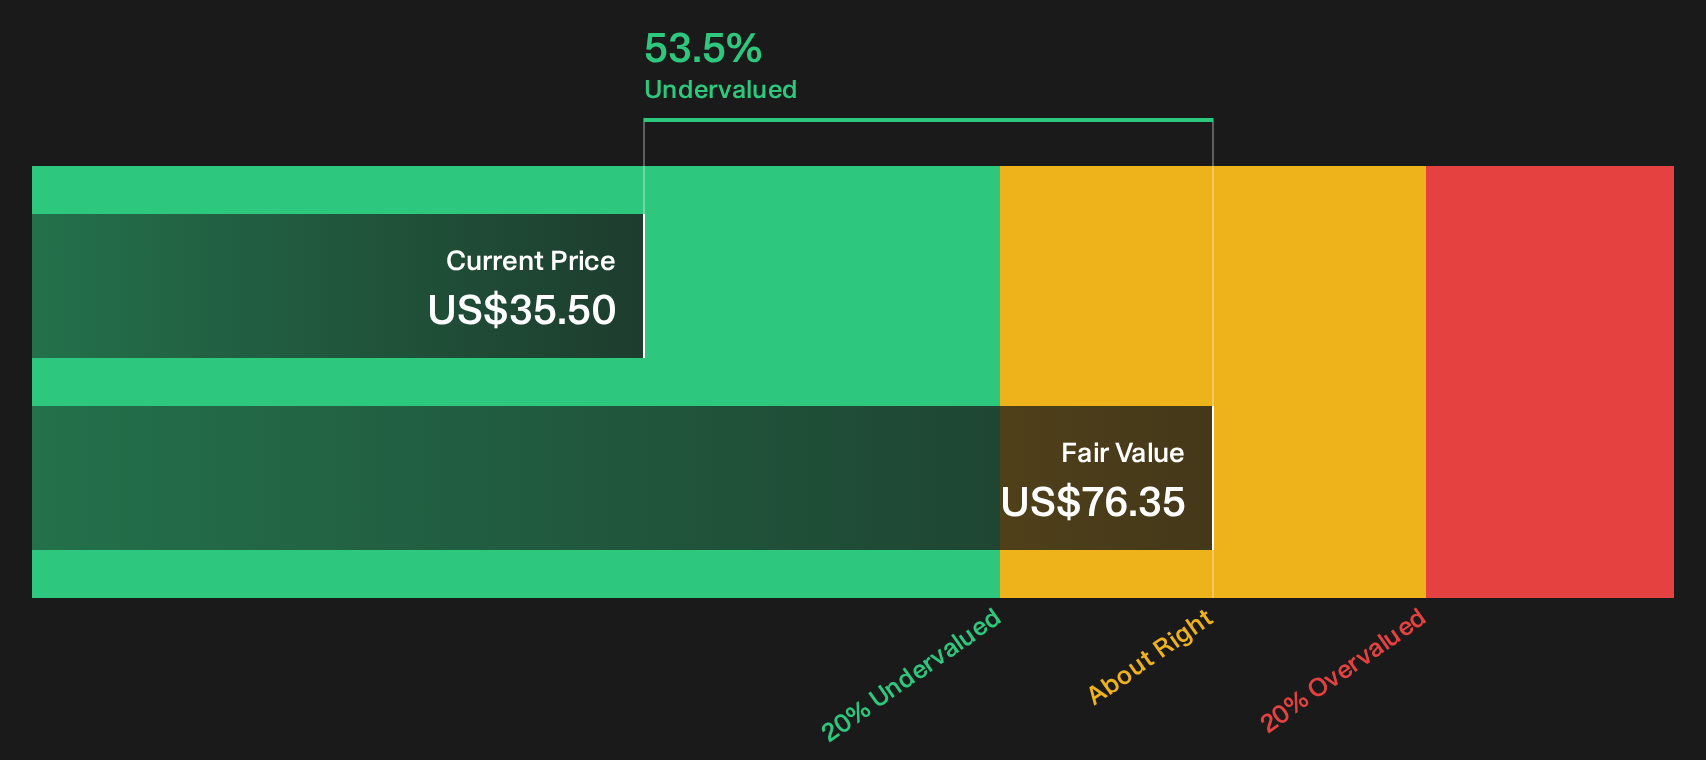
DCF work suggests that Castle Biosciences is trading 53.5% below an estimated future cash flow value of $76.35. At the same time, the market is paying a relatively high 3x P/S, compared with 1.3x for the broader US healthcare group and 0.7x for peers. This raises the question of whether the stock represents an opportunity based on cash flows or a stretch based on sales multiples.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Castle Biosciences can either pull you in or push you away, so move quickly, test the numbers yourself, and weigh both sides of the story with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Castle Biosciences?
Do not stop with Castle Biosciences. Use the same structured approach across sectors so you are consistently working from data, not headlines or hunches.
- Target potential mispricing by scanning a curated pool of quality opportunities using the 34 high quality undervalued stocks.
- Strengthen capital preservation by focusing on businesses flagged in the 11 resilient stocks with low risk scores that pair resilience with measured downside profiles.
- Pursue reliable income ideas by reviewing companies highlighted as 6 dividend fortresses that combine yield with underlying business fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com