
DICK'S Sporting Goods (DKS) Stock May Be A Bargain On Earnings
DICK'S Sporting Goods has seen its share price fall sharply over the past year, which puts fresh attention on what investors are really paying for its earnings today. With the stock changing hands around US$123.72 at the last close, the key issue is whether that level lines up with the profits the retailer is currently generating.
- The share price has declined 42.9% over the past year, which puts recent market confidence in DICK'S Sporting Goods' earnings power under the microscope.
- The business model depends heavily on turning merchandise and store traffic into consistent profit margins, so any shift in how efficiently it converts sales into earnings can reshape what investors are willing to pay for each dollar of profit.
- The analysts covering DICK'S Sporting Goods have run their own numbers. See what analysts think DICK'S Sporting Goods's shares could be worth.
For investors, the debate is whether DICK'S Sporting Goods' current share price is appropriately aligned with its earnings when judged against a Fair Ratio benchmark.
To see how this same earnings based valuation question plays out across other companies, widen your search to the 34 high quality undervalued stocks
Does DICK'S Sporting Goods Look Undervalued on Earnings?
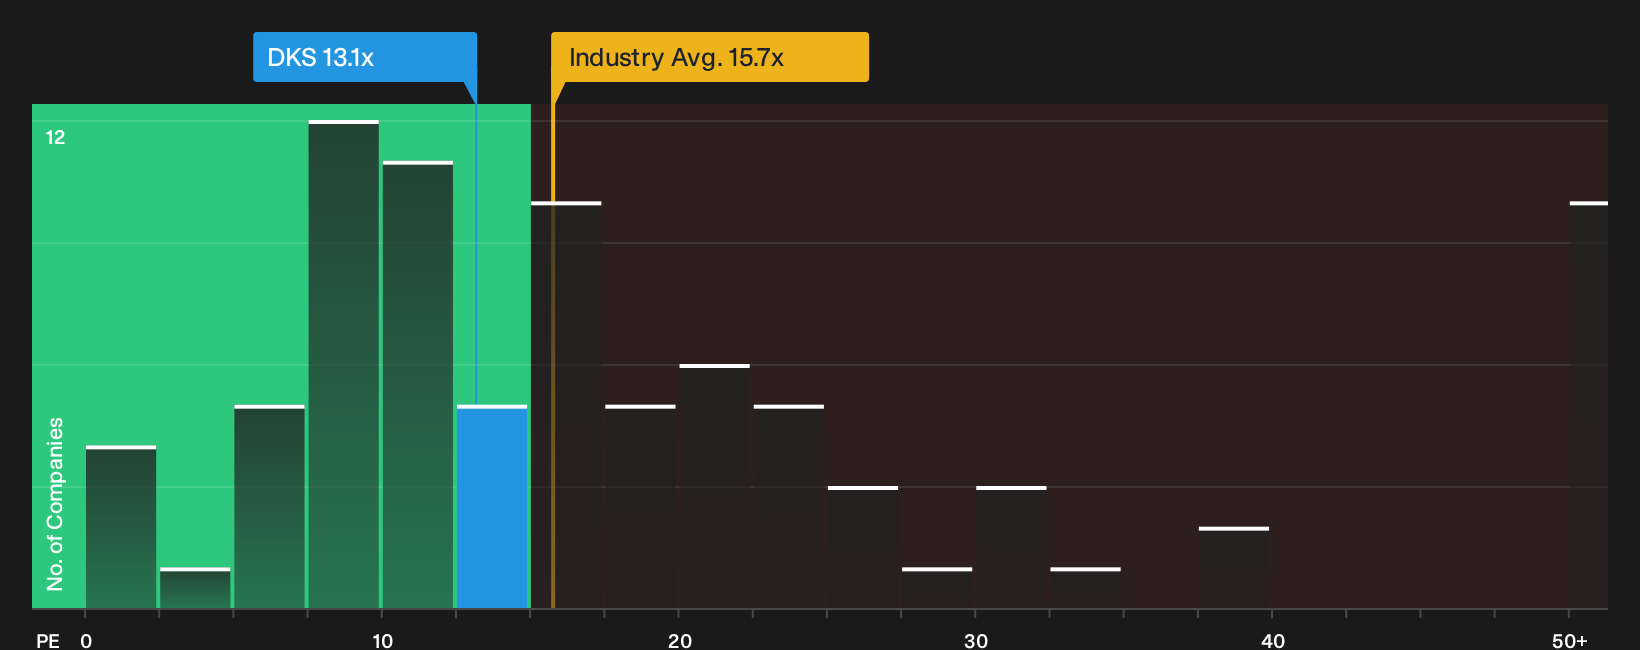
The P/E ratio is a useful yardstick for DICK'S Sporting Goods because earnings are a key focus for retailers that convert store traffic into profit. On this measure, the stock trades on a P/E of about 13.1x, which is below the Specialty Retail sector average of roughly 15.7x and also below a broader peer group closer to 22.1x.
A Fair Ratio model that factors in DICK'S Sporting Goods' industry, profitability profile, size and risk points to a higher P/E than the market is currently applying, so the shares change hands at a discount to what that framework suggests might be appropriate. For an investor, the gap between the 13.1x multiple and both sector and peer benchmarks highlights how much weight the market is putting on potential risks or earnings questions compared with retailers priced nearer those higher levels. Explore the numbers behind DICK'S Sporting Goods's P/E valuation.
The DICK'S Sporting Goods Narrative: What Would Justify Today's Price?
Narratives for DICK'S Sporting Goods pick up where the P/E puzzle leaves off by spelling out which future paths for sales, margins and earnings would need to play out for the stock to be worth materially more or materially less than it is today on Simply Wall St's Community page. Instead of a single number from a ratio or model, they lay out the underlying earnings story that number relies on so you can watch how reality compares over time.
Community views on DICK'S Sporting Goods split between a strong earnings recovery story and a sharper focus on execution risk around Foot Locker and promotions.
Bull case: 46% undervalued
"The launch and ongoing growth of proprietary platforms like GameChanger and the DICK’S Media Network are set to meaningfully boost gross margins..."
Discover why this Narrative puts DICK'S Sporting Goods at 46% undervalued.
Bear case: 10% overvalued
"Full-year Foot Locker pro forma comp guidance moved from 1.5% to 3% growth to 2% to flat and the operating income expectation shifted to a loss..."
Explore why this Narrative puts DICK'S Sporting Goods at 10% overvalued.
DICK'S Sporting Goods valuation leaves one crucial issue hanging
Price multiples only tell part of the story for DICK'S Sporting Goods, because separate checks have flagged specific areas of concern that could matter more than any P/E comparison. Take a closer look at 3 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com