
Should Arizona Campus Expansion Require Action From Amkor Technology (AMKR) Investors?
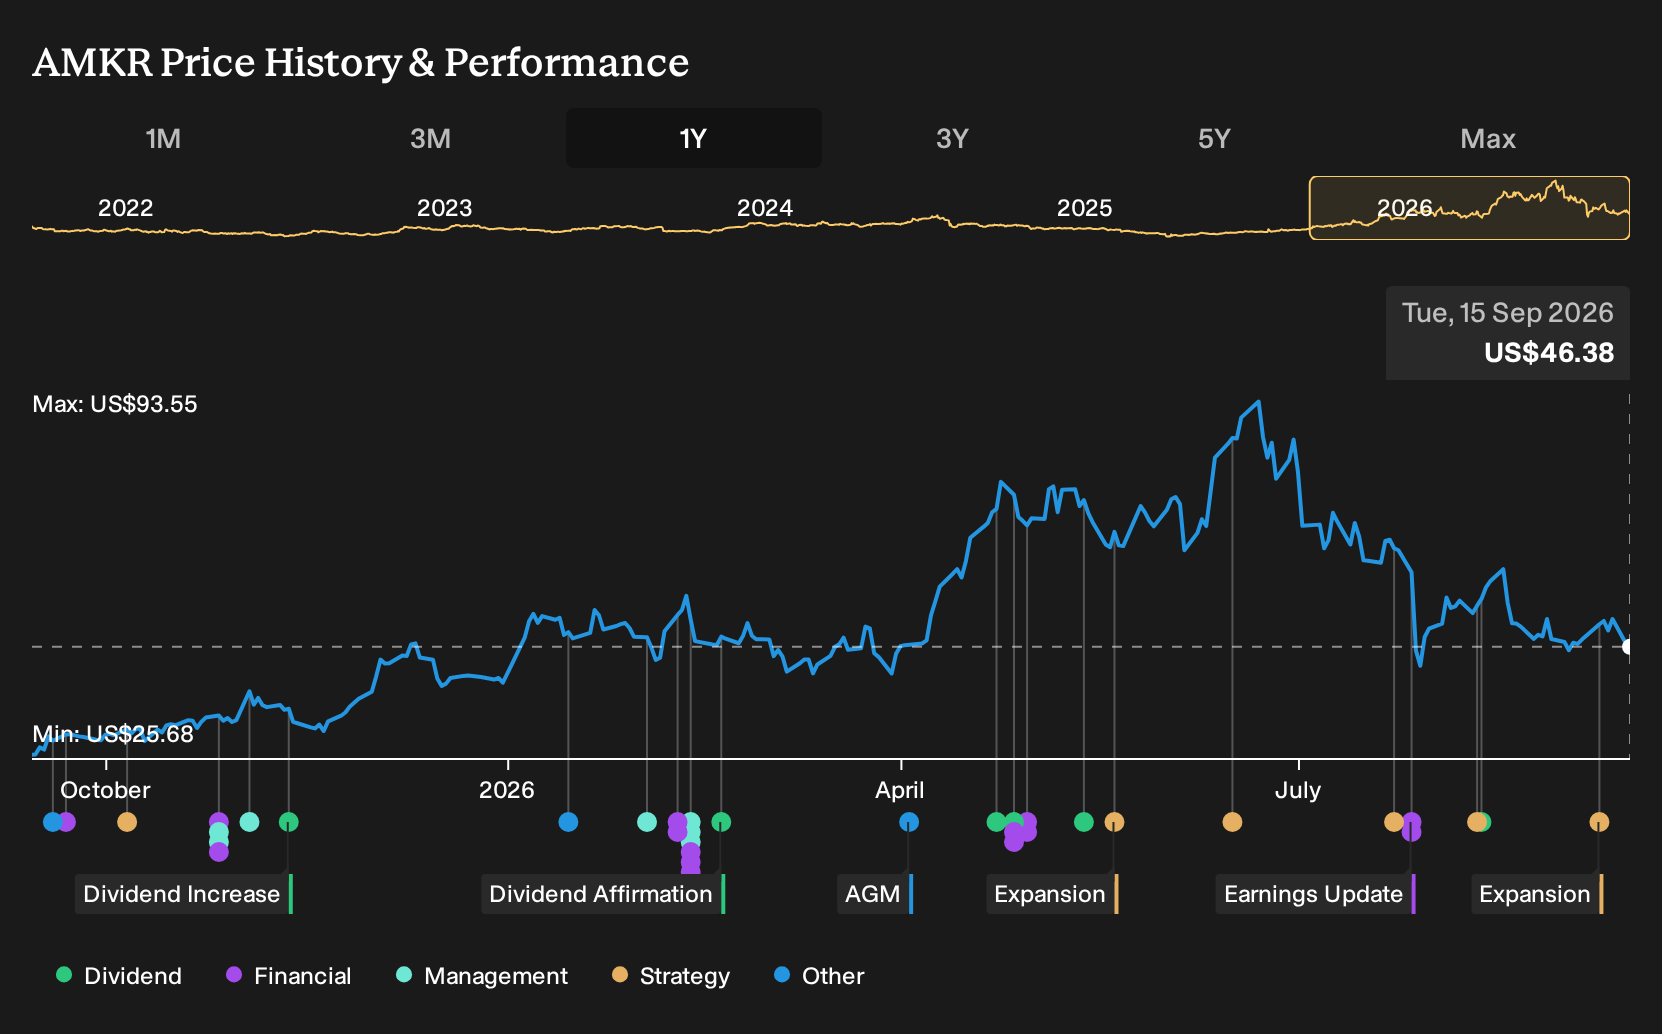
- Amkor Technology has outlined phase 2 of its Arizona advanced packaging and test campus, lifting planned cleanroom space to about 93,000 square meters and total project investment to roughly US$12b. Construction is targeted to start in 2027 and finish by the end of 2029.
- The expanded Arizona site is set up as the first high volume advanced packaging OSAT production hub in the U.S., giving Amkor Technology customers a domestic turnkey bump, probe, assembly and test option aligned with long term regional supply chain goals.
- We will now look at how Amkor Technology's enlarged US$12b Arizona campus could reshape the existing investment narrative for the business.
Scan beyond Amkor Technology and this Arizona expansion by reviewing hand-picked peers exposed to chip packaging, testing and related capacity themes in the 60 AI infrastructure stocks.
Amkor Technology Investment Narrative Recap
To own Amkor Technology, you need to believe outsourced advanced packaging and test will remain central to AI data center, high performance computing and automotive programs, and that customers will continue to value regional supply chains. The Arizona build out fits that view but does not change that the near term swing factor is still how quickly new AI and advanced packaging work absorbs global capacity.
The biggest operational risk right now is overbuilding, especially in the U.S., then running those plants below optimal utilization while depreciation and fixed costs rise. Phase 2 in Arizona increases that exposure, so the focus remains on execution discipline, mix toward higher value packages and how Communications demand holds up relative to Computing and Automotive strength.
The Phase 2 Arizona plan is the clearest recent operational marker linked to those catalysts. Capacity is being built for high volume advanced packaging with a full bump, probe, assembly and test flow. This ties directly into long duration agreements with customers such as TSMC and NVIDIA that already frame future loading assumptions in both Arizona and Asia.
With construction on Phase 2 scheduled from late 2027 through 2029, the key issue for Amkor Technology is how well management matches that build schedule to actual AI, data center and automotive program ramps while handling parallel projects in Korea, Vietnam, Portugal and Taiwan. Execution gaps could leave utilization and returns under pressure at the same time that convertibles, higher CapEx and Communications softness keep financial risk elevated.
Amkor Technology's current analyst narrative points to revenues of US$10.0b and earnings of US$904.8m by 2029, built on an assumed 10.4% yearly revenue growth rate and an earnings step up of about US$349m from US$555.5m today.
Uncover why Amkor Technology's fair value indicates a 65% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest Amkor Technology forecasts lean hard into the risk of overcapacity. Those analysts were pencilling in revenues of about US$9.4b and earnings near US$740.8m by 2029, well below consensus. That creates a more cautious story, and this new Arizona expansion could prompt them to revisit those assumptions.
Explore 4 other Amkor Technology fair value estimates, including one that suggests it could be worth just $65.00!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Amkor Technology research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Amkor Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amkor Technology's overall financial health at a glance.
Looking For More Investment Ideas Beyond Amkor Technology?
If Amkor Technology has sharpened your view on advanced packaging and AI infrastructure, it can help to compare it with other listed businesses that offer different mixes of quality, income and balance sheet strength. The Simply Wall St Screener lets you filter by fundamentals in a few clicks so you can build a watchlist that fits your own risk tolerance and time horizon.
- Prefer resilient balance sheets and solid fundamentals over headline stories? Start with this list of solid balance sheet and fundamentals (22 results) to see which companies match that profile.
- If stability matters more than excitement right now, focus on lower risk profiles by scanning through the 11 resilient stocks with low risk scores that already pass a tight resilience filter.
- Hunting for quality businesses that are not already crowded trades? Use the 16 high quality undiscovered gems to surface stocks with strong fundamentals that may still fly under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com