
Is Alignment Healthcare (ALHC) A Bargain After Medicare Advantage Reform Fears?
Regulatory shock puts Alignment Healthcare in focus
Bipartisan lawmakers have introduced the Protecting Approved Care Act, targeting prior authorization and payment practices in Medicare Advantage. Alignment Healthcare (ALHC) dropped sharply as investors weighed possible pressure on medical loss ratios and operating margins.
The sharp reaction to the Protecting Approved Care Act comes on top of a difficult run for Alignment Healthcare, with the share price down 51.6% over 90 days and the 1-year total shareholder return declining 37.3%, even though the 3-year total shareholder return is still positive at 60.5%.
Scan beyond Alignment Healthcare and pressure from Medicare Advantage reforms by reviewing a curated group of list of solid balance sheet and fundamentals (22 results) that may handle policy shocks differently.
The question now is whether Alignment Healthcare’s steep drop reflects cracks in the underlying Medicare Advantage model or a rapid reset in sentiment that has pushed the stock too far. The valuation work starts at this point.
Most Popular Narrative: 58% Undervalued
On the most followed view, Alignment Healthcare’s fair value runs well ahead of the recent $10.37 close, which puts the current selloff against a much richer long term cash flow story.
Alignment's robust, technology-enabled care model and investments in administrative automation, workflow standardization, and digital health platforms position the company to significantly lower SG&A expenses and improve scalability, likely powering both margin expansion and earnings growth over the next several years.
Ongoing expansion into existing counties and new states, combined with low market penetration and favorable demographic trends from a rapidly aging population, create a long-term runway for outsized membership and revenue growth as the Medicare-eligible population swells.
See why 11 investors see Alignment Healthcare as 58% undervalued.
Result: Fair Value of $24.92 (UNDERVALUED)
Still, the narrative around Alignment Healthcare can unravel quickly if Medicare Advantage reimbursement tightens further or if competition forces higher acquisition costs and weaker profitability.
Find out about the key risks to this Alignment Healthcare narrative.
Another view on Alignment Healthcare’s valuation
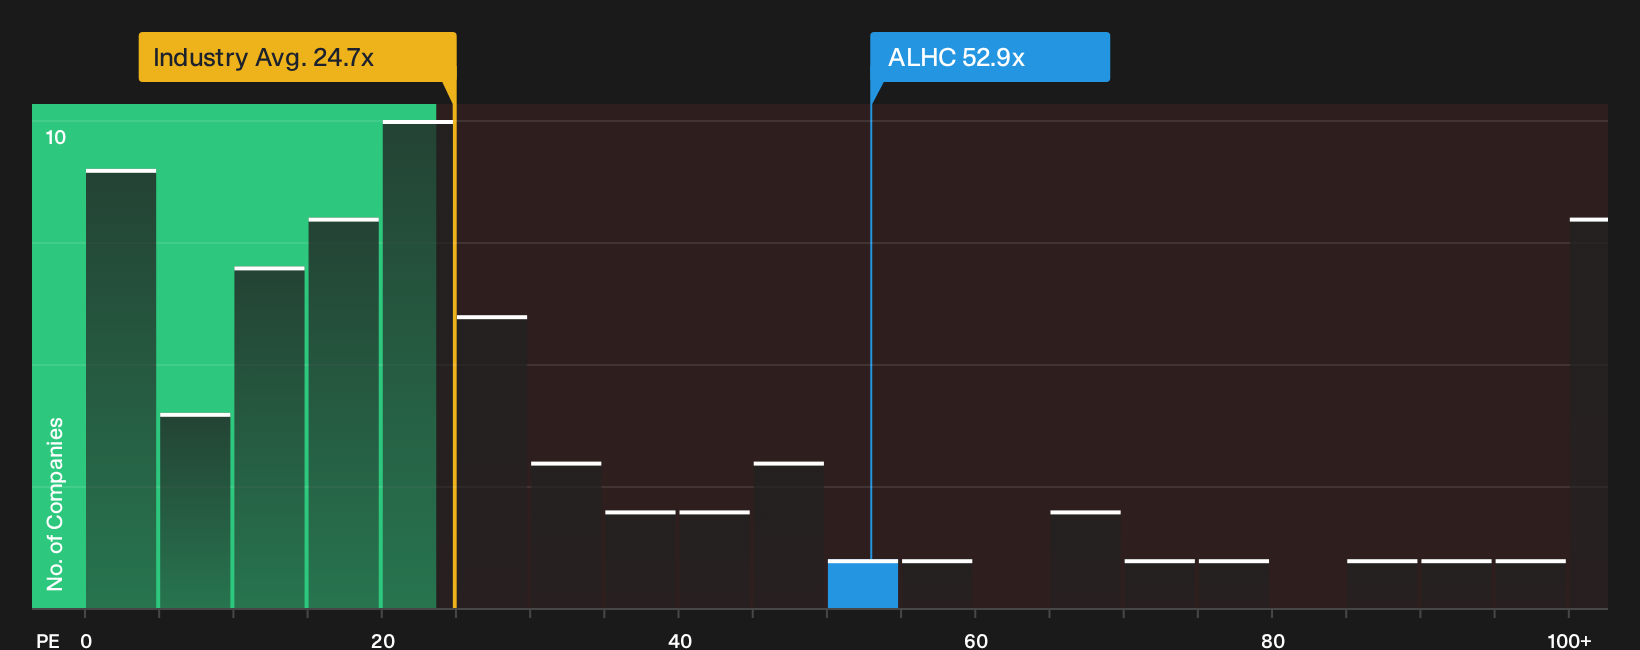
On simple earnings multiples, Alignment Healthcare screens very differently from that 58% undervalued DCF story. The stock trades on a P/E of 52.9x, versus 24.8x for the wider US Healthcare industry and a fair ratio of 47.4x, which points to richer pricing and less margin for error if expectations slip.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like this around Alignment Healthcare rarely last. Act while sentiment is unsettled, and weigh both sides of the story by checking the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Alignment Healthcare?
Do not stop your research with Alignment Healthcare. Widen your watchlist now so you are not hunting for fresh opportunities after others have already moved.
- Target dependable upside potential by reviewing a curated mix of quality companies trading at attractive valuations through the 34 high quality undervalued stocks.
- Prioritise staying power and capital preservation by focusing on businesses with resilient financial footing using the 11 resilient stocks with low risk scores.
- Spot tomorrow’s potential leaders early by scanning a focused group of under-followed stocks with solid fundamentals via the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com