
Micron Technology (MU) Could Be 54% Undervalued As Research Leadership Shifts
Micron Technology (MU) has reshuffled its research leadership, appointing veteran semiconductor executive Deirdre Hanford to lead Micron Research Labs following a broad search for long-term innovation leadership.
Recent trading in Micron Technology reflects that push and pull between excitement over AI memory demand and concerns about how fast that spending continues. The share price is down 7.3% over the past week and 11.1% over 90 days, yet the year-to-date share price return of 194.1% and a very large 1-year total shareholder return signal strong momentum that has cooled in the short term as investors digest product milestones, union risks in Taiwan, and the broader debate over AI development spending.
Scan how AI memory volatility is rippling through related opportunities by comparing Micron Technology with a curated set of 60 AI infrastructure stocks.
Micron Technology is still priced for an AI memory boom after a huge run and a sharp pullback. Given that mix, does the current valuation still compensate you for the execution and cycle risk ahead?
Most Popular Narrative: 54% Undervalued
Micron Technology last closed at $927.60, while the most followed narrative pegs fair value at $2,018.05 using an 11.13% discount rate. That gap frames a bullish story built on AI memory demand and the firm’s position in a tight supply chain.
The primary engine driving Micron's forward revenue growth is the industry-wide transition to vertically stacked HBM4 architectures. The high physical complexity of HBM manufacturing introduces a steep 3x physical wafer consumption penalty over standard planar DDR5. This wafer penalty reduces the global supply of standard commodity memory, creating a persistent supply deficit. This structural tightness allows memory manufacturers to transition away from annual fixed-price agreements toward compressed monthly contracts featuring retroactive, spot-linked post-settlement clauses, maximizing capital returns.
See why 141 investors see Micron Technology as 54% undervalued.
Result: Fair Value of $2,018.05 (UNDERVALUED)
Still, the Micron Technology story leans heavily on tight HBM4 supply and generous CHIPS Act support. Either a packaging stumble or policy reversal could puncture that 54% undervalued thesis fast.
Find out about the key risks to this Micron Technology narrative.
Another View on Micron Technology’s Valuation
The narrative crowd argues Micron Technology is 54% undervalued, yet the SWS DCF model tells a different story. On that framework, the shares change hands well above an estimated future cash flow value of $574.63, which points to an overvaluation signal instead.
That split between cash flow math and story-driven fair value leaves you with a simple question: Which set of assumptions are you actually leaning on when you underwrite Micron’s risk and return profile? Look into how the SWS DCF model arrives at its fair value.
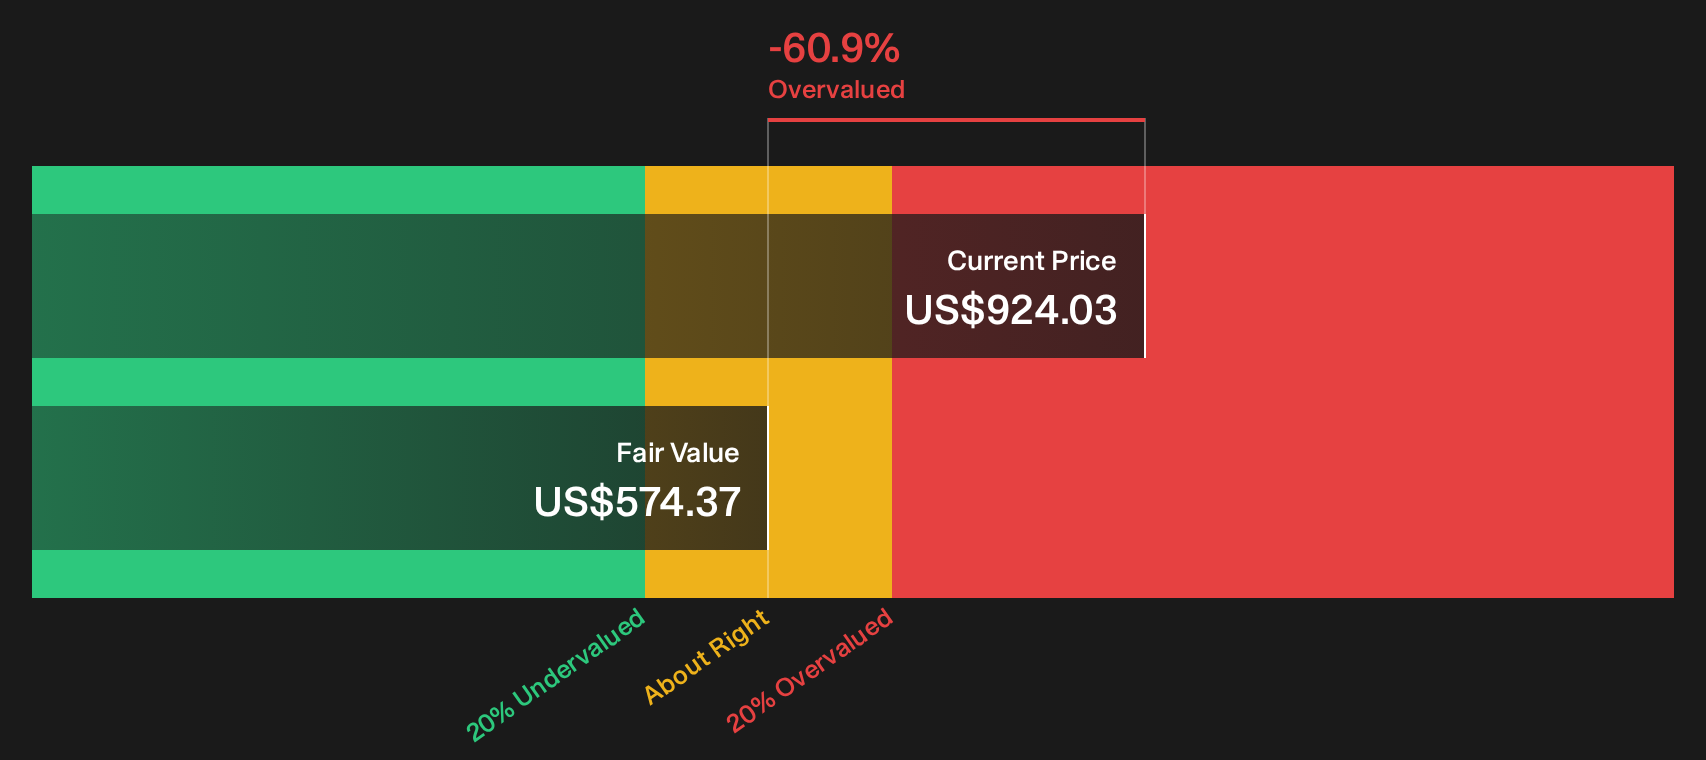
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Micron Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Pockets of optimism sit right beside clear concern around Micron Technology, which makes speed and independent judgment matter. Act on your own read of the data and pressure test both sides of the story by digging into 4 key rewards and 3 important warning signs
Ready For More Ideas Beyond Micron Technology?
Do not stop with Micron Technology. You miss real context if you ignore how other businesses are priced, financed, and rewarded across different styles of opportunity.
- Target stronger upside potential by scanning a 16 high quality undiscovered gems that many investors are not watching yet.
- Prioritize resilience first and stress test your downside by working through a 11 resilient stocks with low risk scores built around sturdier balance sheets and lower risk scores.
- Focus on quality at a reasonable entry point by filtering through a list of solid balance sheet and fundamentals (22 results) that blends healthier finances with fundamental support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com