
Solvay (ENXTBR:SOLB) And The Molecular Sieves Story As Fair Value Stays In Question
The Europe molecular sieves market is projected to grow, supported by tighter EU environmental rules and rising medical oxygen demand. This trend is putting Solvay (ENXTBR:SOLB) and its basic chemicals portfolio on many investors’ radar.
Solvay’s recent share price has drifted lower, with the 90 day share price return down 6.83% and the year to date share price return down 5.27%. However, the 3 year total shareholder return of 41.22% hints that long term holders have still seen solid value creation as sentiment now cools despite interest in its molecular sieves exposure.
Scan beyond Solvay and track other basic materials players exposed to industrial demand shifts with our curated list of list of solid balance sheet and fundamentals (195 results)
Solvay shares now trade below recent levels while longer term holders still sit on sizeable gains. Does that dip offer a reasonable entry now, or does waiting for clearer value make more sense as you look at the valuation work next?
Most Popular Narrative: 3% Overvalued
Solvay’s most followed valuation narrative now anchors fair value at €25.10, a touch below the last close at €25.90. This puts the recent share price softness against slightly richer expectations for future cash generation.
Ramp-up of new, highly competitive soda ash and rare earth capacities offers scope for improved profitability and share gains once market demand normalizes or supply rationalization (e.g., Chinese plant closures) occurs. This operational leverage may be underappreciated in the current valuation.
See why 31 investors see Solvay as 3% overvalued.
Result: Fair Value of €25.10 (OVERVALUED)
Still, two pressure points could easily unsettle that fair value story: prolonged weak pricing in soda ash and any rise in environmental remediation costs that squeezes Solvay’s future cash generation.
Find out about the key risks to this Solvay narrative.
Another View On Solvay’s Value
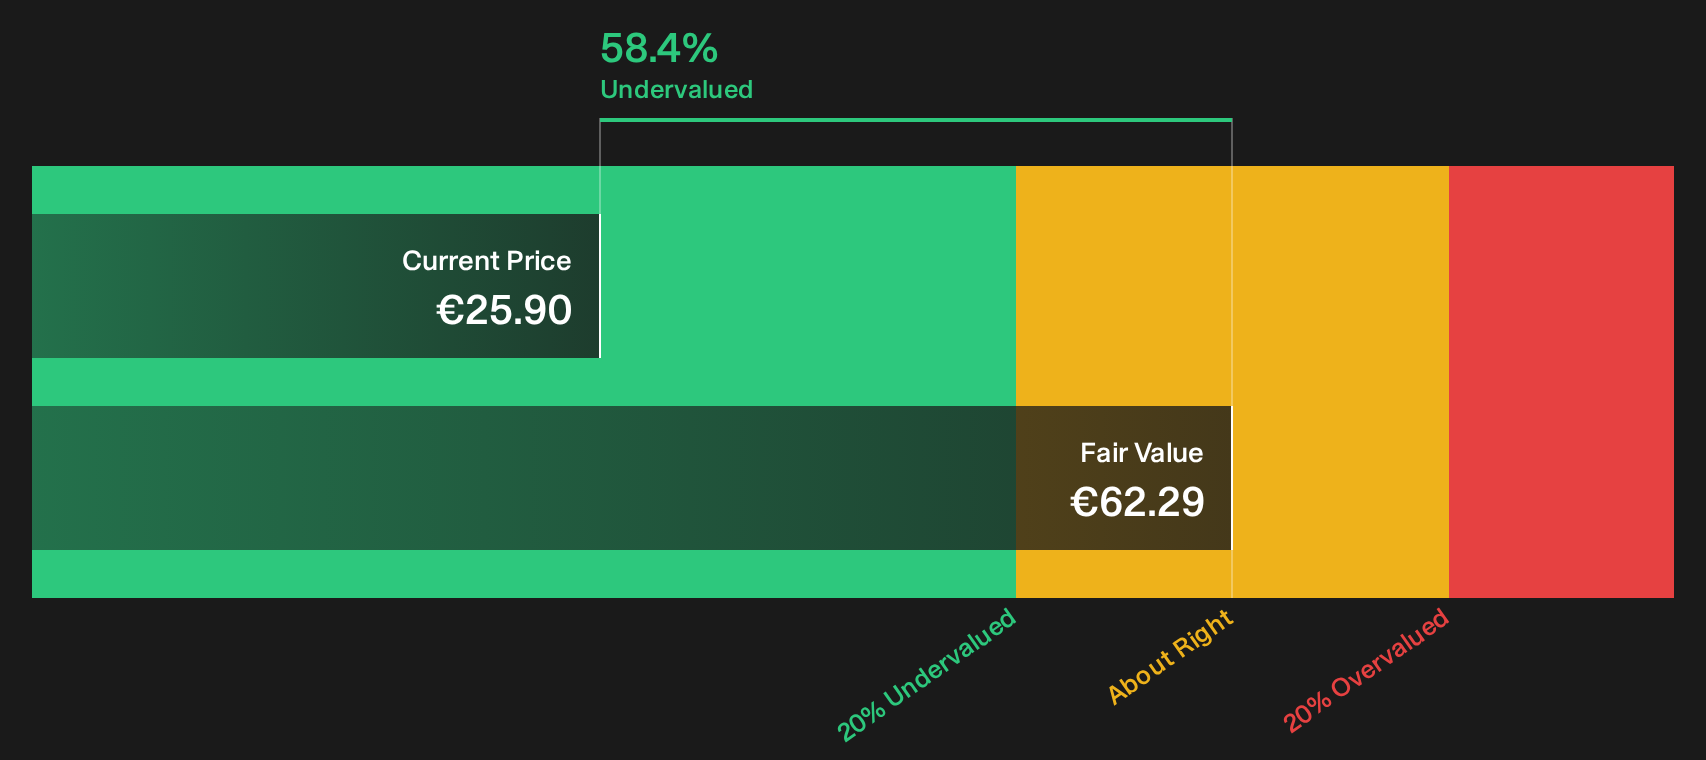
Analysts see Solvay as around 3% overvalued at €25.10, yet our DCF work points to a very different picture. The SWS DCF model estimates future cash flows at about €62.29 per share, which frames the current €25.90 price as heavily discounted. Which story do you trust more, the market multiple or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed verdict so far on Solvay, right? Use the numbers, not the noise, to pressure test your own stance and weigh up the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Solvay?
Do not stop at Solvay. Broaden your watchlist with fresh ideas and give yourself more options when the next big move comes into focus.
- Hunt for potential bargains that combine quality with compressed expectations by scanning our 192 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies in the 163 dividend fortresses offering higher yields with supporting fundamentals.
- Dial down risk and concentrate on sturdier balance sheets by screening through the 103 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com