
How Investors Are Reacting To REA Group (ASX:REA) Contract Limits Removed
- REA Group entered a court enforceable undertaking with the ACCC after concerns about restrictive realestate.com.au contracts, agreeing to stop requiring agencies to list all or most properties on its platform and to offer greater flexibility to downgrade listing tiers.
- The shift away from tying agents to high tier listings and exclusive use of realestate.com.au indicates increasing competitive and regulatory scrutiny of REA Group’s pricing model and contract structure.
- We will now assess how REA Group's revised contracts and greater agent listing flexibility could influence its broader investment narrative.
REA Group Investment Narrative Recap
To own REA Group, you need to be comfortable with a property classifieds leader that leans heavily on premium listing yields, product breadth and adjacent services like financials, all in a market where listing volumes and pricing are key swing factors. The ACCC undertaking chips away at contract stickiness and high tier upsell pressure, yet does not change the core reliance on Australian property activity.
The most immediate catalyst still sits in execution on premium products, audience depth and financial services, given earnings are forecast to grow 11.1% per year. The biggest near term risk is that competition and now clearer regulatory guardrails make further yield expansion harder. This would test the current P/E and the thesis that REA can keep monetising its audience more deeply.
The AI and workflow focus highlighted by REA Group’s FlowLab program is especially relevant now. Management is putting attention on tools that cut friction for agents, like Agent Angel and other Hackdays projects, at the same time as contracts become less restrictive and rival portals have more room to compete for vendor spend.
For you as an investor, that makes product execution in AI and automation part of the core catalyst set, not a side project. If REA can turn these tools into clear time savings and better campaign results for agencies, that could help offset some of the pricing and exclusivity constraints introduced by the ACCC process and support the broader digital property thesis.
REA Group's narrative projects A$2.3b revenue and A$984.2m earnings by 2029. This assumes 5.1% yearly revenue growth and an earnings increase of about A$311m from A$673.0m today.
Uncover why REA Group's fair value indicates a 22% potential upside to its current price, which could narrow quickly as sentiment catches up.
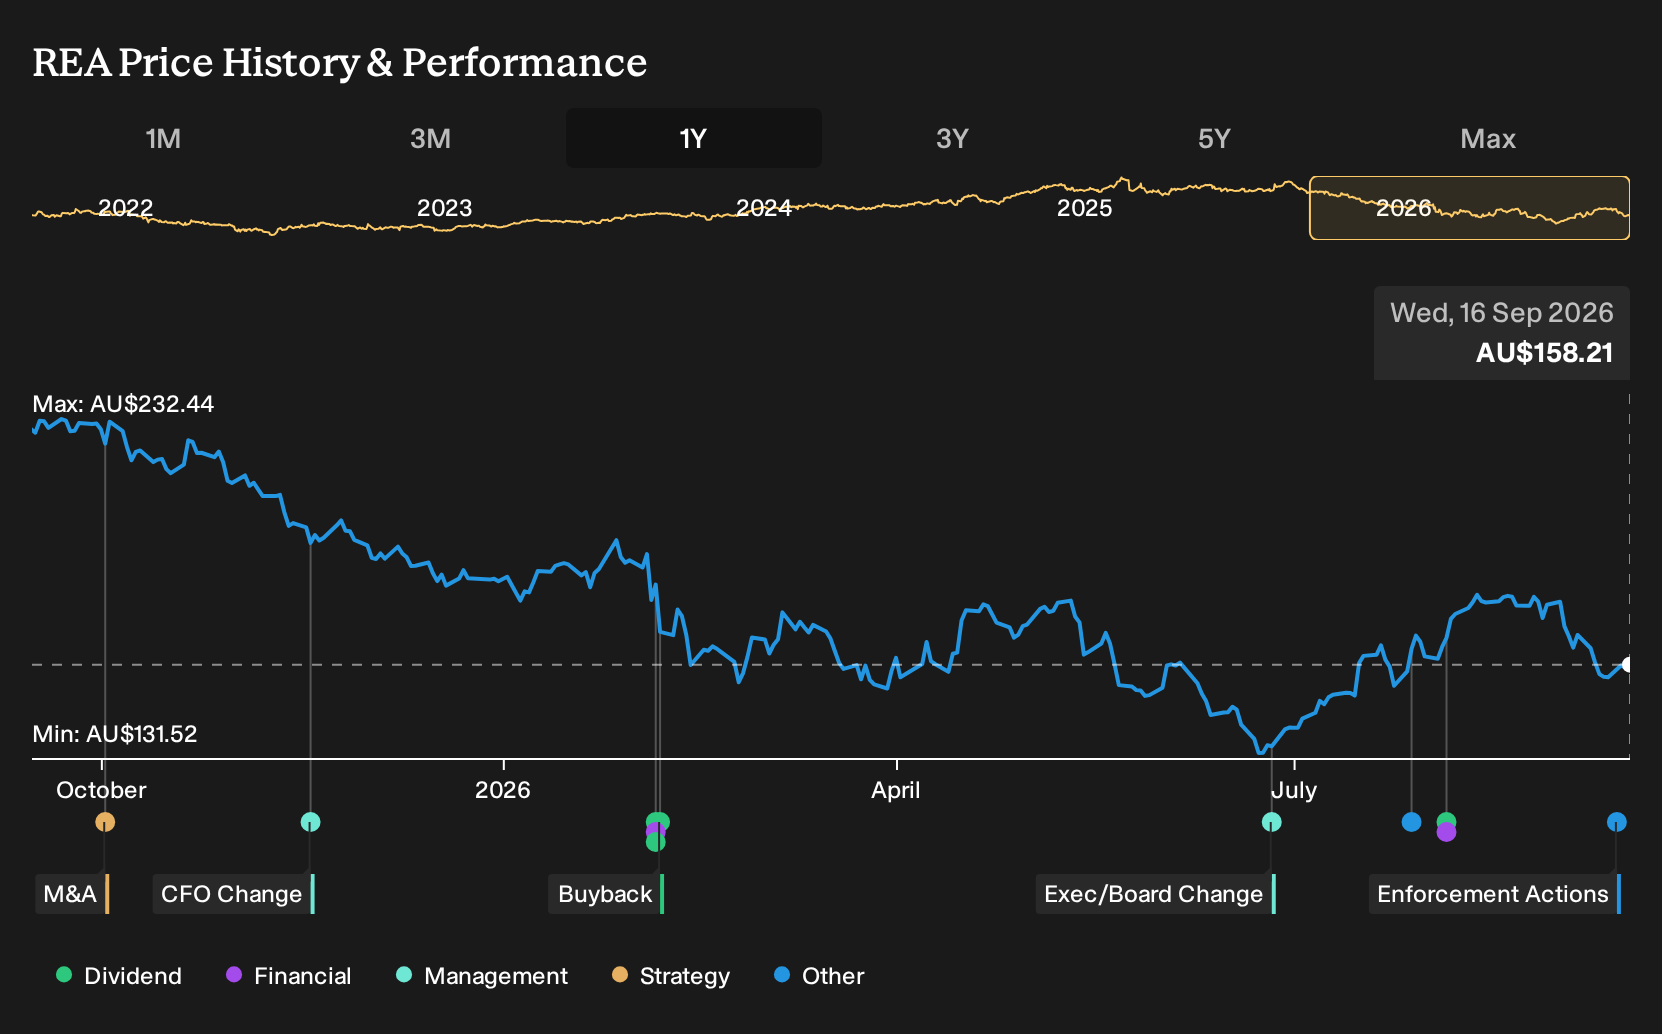
Exploring Other Perspectives
One alternate view says the real risk for REA Group is structural, not cyclical. On that score, the most cautious analysts were already assuming only 2.0% annual revenue growth and earnings of about A$787.3 million by 2029 before this ACCC move. That is a much tougher story. Use it as a prompt to test your own assumptions, because fresh regulation could push these narratives in new directions.
Explore 5 other REA Group fair value estimates, including one that suggests as much as 6% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your REA Group research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for REA Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate REA Group's overall financial health at a glance.
Looking For More Ideas Beyond REA Group?
If the REA Group story has sharpened your thinking about pricing power, contracts and competitive pressure, it can be useful to widen the lens and compare it with other businesses that fit different risk and quality profiles.
- If capital preservation is high on your list, scan a curated set of 3 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- For readers hunting for more value orientated opportunities, line up REA Group beside a 5 high quality undervalued stocks identified by the screener's quality and pricing filters.
- If you want potential upside in less crowded areas of the market, sort through a 15 high quality undiscovered gems that pair solid fundamentals with relatively low investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com