
Lennar (LEN) Stock Trades At A Discount Following Its 39% Slide
Lennar has seen its share price fall sharply over the past year, and the drop raises a straightforward question for investors who focus on fundamentals. Is the current valuation still in step with the earnings power of this large US homebuilder, given the pressure from higher mortgage costs and softer housing demand?
- The stock is down about 39.0% over the past 12 months, which puts the focus squarely on whether that move has reset expectations around Lennar's earnings or if the slide reflects deeper concerns about its profit engine.
- Recent commentary from management points to margin pressure from affordability challenges and higher buyer incentives, which can influence how much of each dollar of revenue ultimately turns into earnings available to shareholders.
- Your read on Lennar is one view; the desks covering it have another. See what analysts think Lennar's shares could be worth.
The issue now is whether Lennar's current share price is appropriately aligned with what its earnings suggest the business is worth today.
If you are questioning whether Lennar's earnings still justify today's share price, it can help to apply the same perspective across 34 high quality undervalued stocks.
Is Lennar Still Cheap on Earnings?
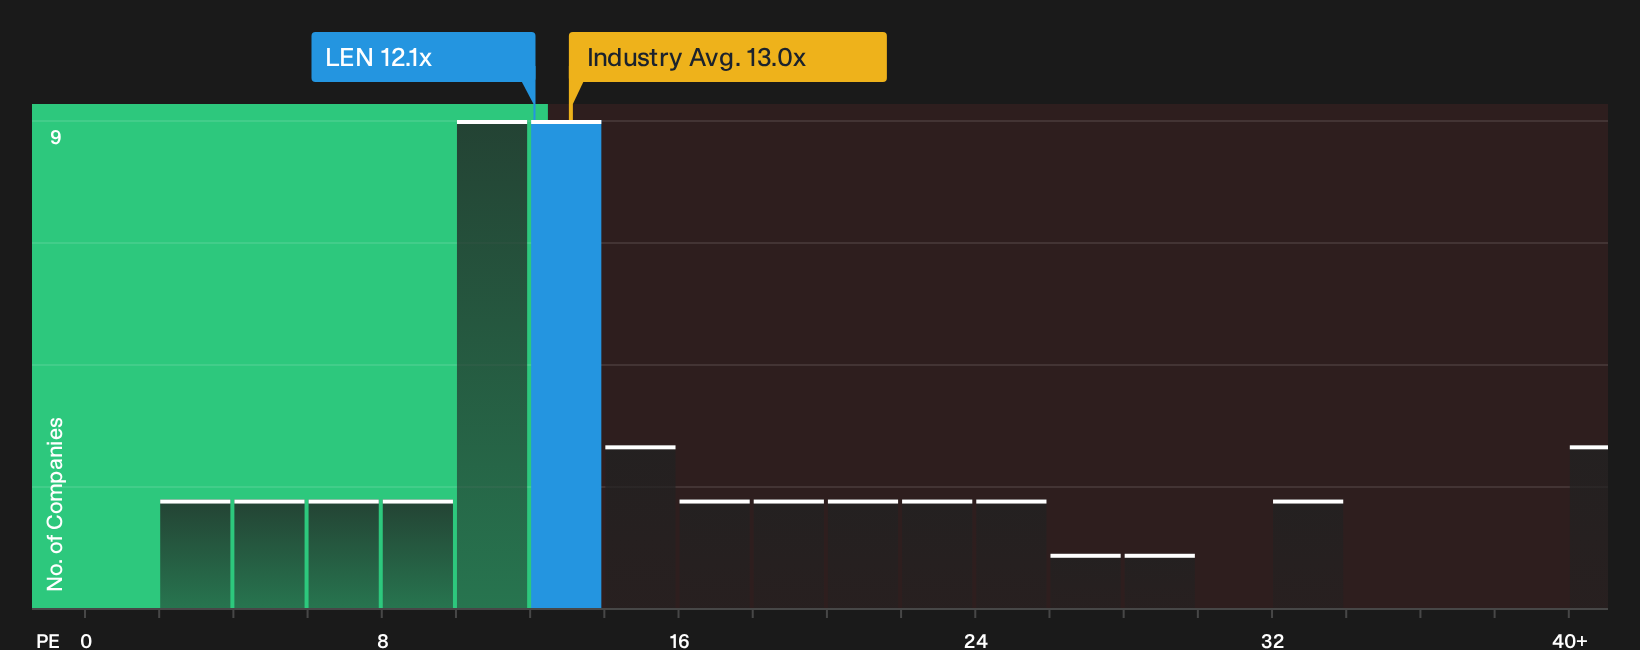
The P/E ratio is a useful starting point for Lennar because earnings remain a key lens for homebuilders with cyclical demand and changing margins. Lennar currently trades on a P/E of 12.1x, which is slightly below both the Consumer Durables industry average of 13.0x and the peer group on 12.4x, so the stock changes hands at a modest discount to what investors are paying for comparable builders on this measure.
The Fair Ratio model, which estimates the P/E you might expect given Lennar's specific mix of growth prospects, profitability, size and risk, points to a higher multiple than the one the shares currently carry. On this framework, the stock screens as undervalued. Because recent earnings expectations have been cut, with analysts looking for lower Q3 FY26 profits due to affordability pressure and incentives, the current discount suggests the market is already pricing in some of that hit to earnings power rather than paying up for a quick rebound. Explore the numbers behind Lennar's P/E valuation.
The Lennar Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Lennar valuation puzzle leaves off by spelling out the specific assumptions on future growth, margins and earnings that would need to play out for the stock to be worth meaningfully more or less than it is today on the Community page. Each narrative ties its number to a concrete view on how Lennar's growth profile, profitability and risk balance might evolve, which you can revisit as new information comes through.
The community split on Lennar is real, with one camp seeing the recent reset as an opening and the other worrying that the headwinds are not fully reflected.
Bull case: 7% undervalued
"Lennar's transition to an asset-light, land-light model with just-in-time delivery is expected to generate more predictable volume and growth, reducing the asset base and risk profile while improving cash flow..."
Discover why this Narrative puts Lennar at 7% undervalued.
Bear case: 20% overvalued
"The company anticipates ongoing margin pressure due to increased sales incentives of approximately 13% to counteract affordability issues..."
Explore why this Narrative puts Lennar at 20% overvalued.
One more piece of the Lennar story deserves attention
Before you lean too heavily on Lennar's earnings multiple and community narratives, it is worth checking the separate risk checks that have picked up specific concerns that could change how you view the whole picture. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com