
Is First Bancorp (FBNC) Fully Valued Following Its Latest Dividend Declaration?
First Bancorp (FBNC) has reaffirmed its shareholder payout policy, declaring a cash dividend of $0.24 per share, payable on October 23, 2026, to investors of record on September 30.
At a latest share price of US$64.10, First Bancorp has given investors a year-to-date share price return of 25.91%, while the 1-year total shareholder return sits at 23.19% once dividends are included. Short-term momentum has cooled, with the 30-day share price return down 3.38% after a 6.32% gain over 90 days. This fresh dividend declaration therefore lands against a backdrop of stronger multi-year total shareholder returns of 146.51% over 3 years and 81.79% over 5 years, which points to a story built over time rather than a quick rerating.
Scan beyond First Bancorp’s dividend story and review a hand picked set of income focused banks and financials in the 6 dividend fortresses
Bulls view First Bancorp as a solid earner with a consistent dividend and strong multi year returns, while bears point to recent share price softness. The key question is which story the current valuation signals appear to support next.
Preferred P/E of 20x for First Bancorp: Is it justified?
First Bancorp trades on a P/E of 20x, which is a premium tag relative to many US bank stocks, even after the strong multi year share price return and recent dividend announcement.
The P/E ratio compares the current share price to earnings per share and gives a rough sense of how much investors are paying for each dollar of profit. For banks like First Bancorp, it is one of the most watched gauges because earnings quality, loan performance, and capital efficiency all eventually flow through that number.
For this stock, the key tension is that the valuation multiple is rich while several fundamentals look supportive. Earnings grew 37.1% over the past year, revenue expanded 21.1% on an annual basis, net income growth is 28.2% per year, profit margins are 32.3% compared with 26.8% a year ago, and earnings are expected to grow significantly faster than the broader US market according to the forecasts provided. That combination can help explain why investors are willing to pay up relative to peers. However, the current P/E of 20x is also above the estimated fair P/E of 17x, which suggests the market may be pricing in a lot of good news already and could move closer to that fair ratio if expectations cool.
Compared with the US Banks industry average P/E of 11.9x and a peer average of 11.4x, First Bancorp carries a clearly higher earnings multiple. The gap to the estimated fair P/E of 17x is also meaningful. This indicates the current valuation is richer than both the sector and the level the market could eventually converge toward if sentiment normalizes.
Explore the SWS fair ratio for First Bancorp.
Result: Price-to-earnings of 20x (OVERVALUED)
Still, the recent share price pullback over 1 day, 7 days, and 30 days, alongside a richer P/E than peers, could quickly challenge optimism about First Bancorp.
Find out about the key risks to this First Bancorp narrative.
Another View On First Bancorp’s Value
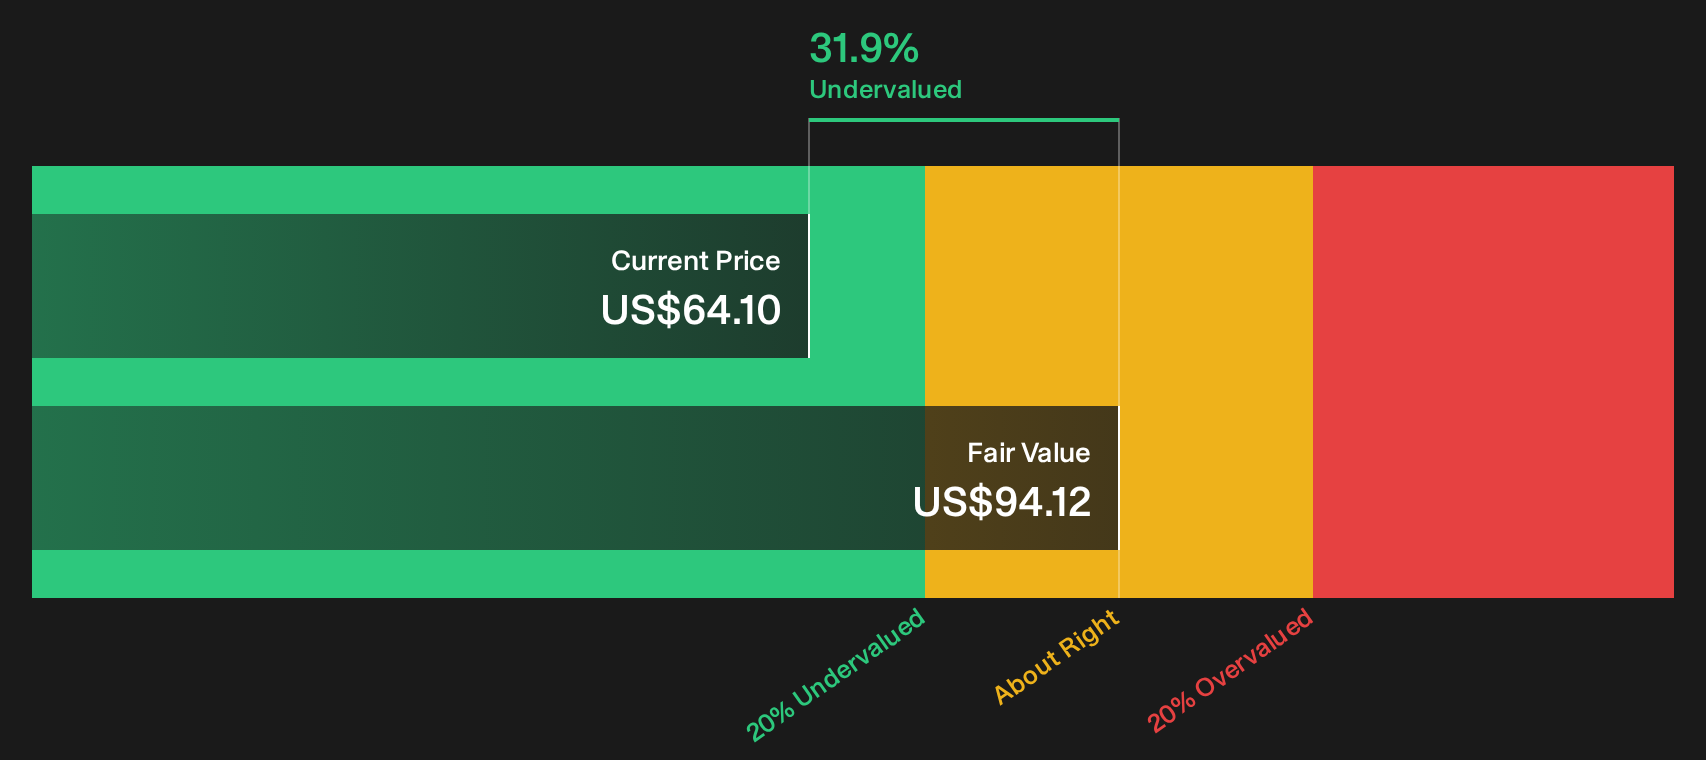
The P/E of 20x presents First Bancorp as expensive, yet the SWS DCF model suggests the opposite. On that cash flow view, the shares at $64.10 trade around 31.9% below an estimated fair value of $94.12. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear opportunity for First Bancorp? If the numbers raise more questions than answers, pressure test the optimism yourself with the 4 key rewards
Looking for more investment ideas beyond First Bancorp?
If First Bancorp has sharpened your focus on quality, do not stop here. Broaden your watchlist now so you are not reacting after the next move.
- Target resilient balance sheets and consistent fundamentals by scanning the list of solid balance sheet and fundamentals (22 results) that match your risk comfort.
- Hunt for mispriced opportunities by reviewing the 34 high quality undervalued stocks that pair financial strength with appealing valuations.
- Lock in income focused ideas by checking the 6 dividend fortresses built around higher yielding but fundamentals driven payers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com