
Merchants Bancorp (MBIN) Is Back In Focus, What Is Catching Investors’ Attention?
Merchants Bancorp (MBIN) has drawn fresh attention after its recent share performance, with the stock down about 4% over the past month but ahead roughly 8% in the past 3 months.
Despite some recent softness, Merchants Bancorp shares still reflect strong momentum, with the stock easing over the past month even after a sharp year-to-date share price return of 59.28% and a 1-year total shareholder return of 69.51%. These figures point to shifting expectations around its prospects and risk profile.
Scan beyond Merchants Bancorp's recent run and line up other financially solid opportunities with our hand picked list of solid balance sheet and fundamentals (22 results).
Merchants Bancorp now trades below both analyst targets and an indicated fair value, even after a strong year. Is that a margin of safety, or a warning sign about market caution?
Preferred Multiple of 10.6x P/E: Is it justified?
On simple earnings terms, Merchants Bancorp trades on a P/E of 10.6x, while still carrying a 1 year total return of 69.51%. That gap between valuation and recent performance raises the question of whether investors are being too cautious or simply pricing in more modest expectations.
The P/E ratio compares the current share price with earnings per share. For a diversified financial business like Merchants Bancorp, which generated $632.339m in revenue and $228.738m in net income, this measure helps you see what the market is willing to pay for each dollar of profit.
Compared with peers, the picture sharpens. The stock trades below the US Diversified Financial industry average P/E of 17.4x and below a peer average of 16.2x. It is also under an estimated fair P/E of 12.7x, which signals the market is applying a clear discount that could narrow if sentiment or results shift toward that fair level.
Explore the SWS fair ratio for Merchants Bancorp.
Result: Price-to-Earnings of 10.6x (UNDERVALUED)
Still, the narrative around Merchants Bancorp can change quickly if credit quality weakens in its specialized lending niches or if funding costs put pressure on profitability.
Find out about the key risks to this Merchants Bancorp narrative.
Another View on Merchants Bancorp's Value
While the 10.6x P/E suggests Merchants Bancorp trades at a discount, the SWS DCF model paints an even sharper picture. On that framework, the shares trade well below an estimated future cash flow value of $125.11, which points to a very wide valuation gap. Is that a genuine opportunity, or is the model too optimistic for a specialized lender with credit and funding risks?
Look into how the SWS DCF model arrives at its fair value.
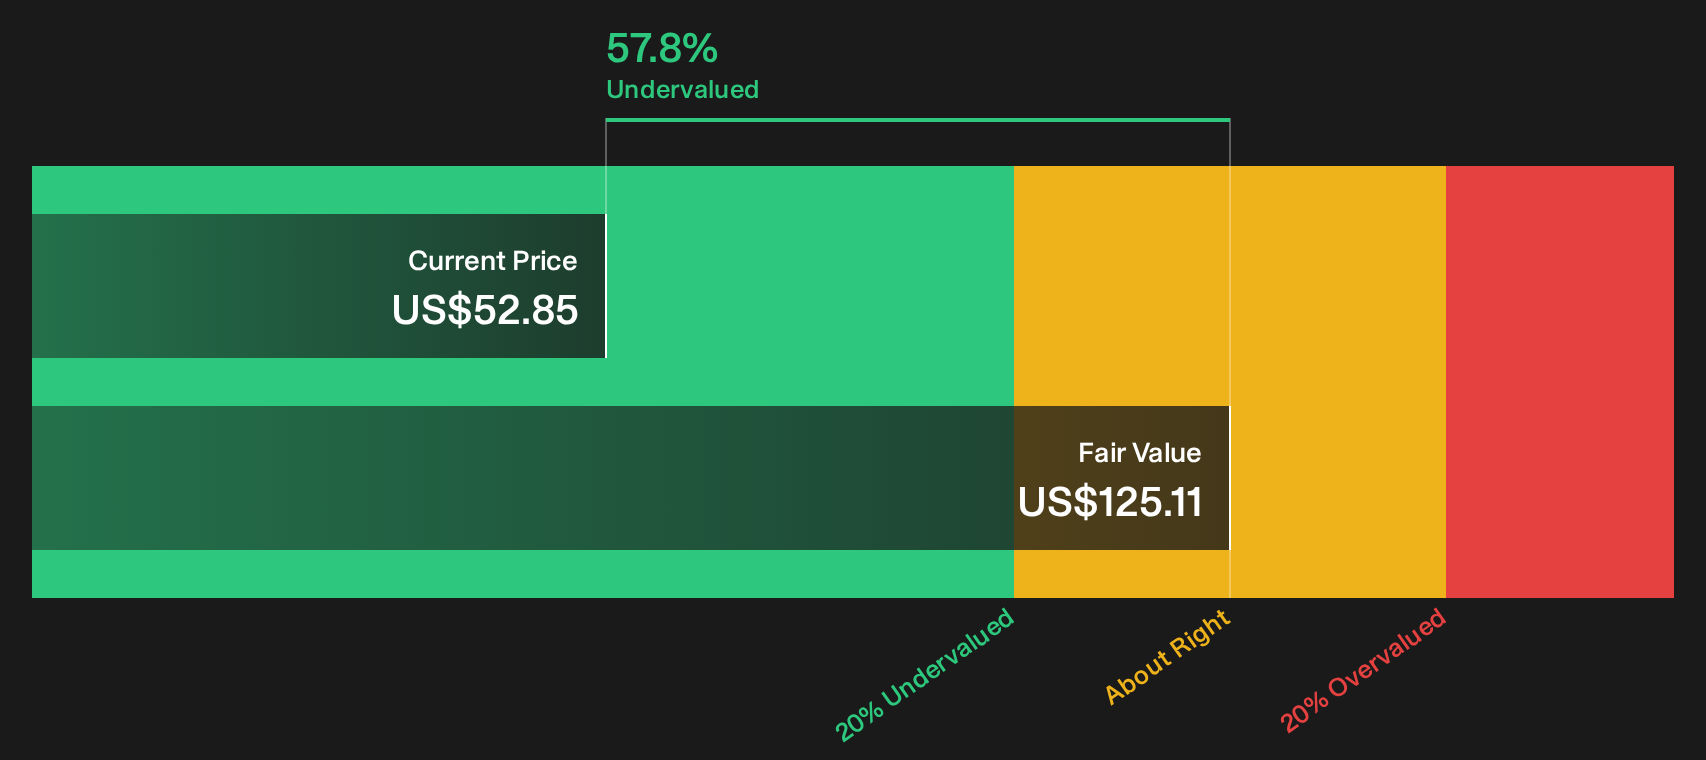
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Merchants Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the balance of optimism and concern around Merchants Bancorp matches your own read of the situation? Put the valuation, credit, and earnings assumptions under your own microscope, then pressure test that view against the 4 key rewards and 2 important warning signs.
Looking for more Merchants Bancorp sized investing ideas?
Do not stop your research with Merchants Bancorp alone. Broaden your watchlist with other candidates that fit your style, so you are not caught reacting late.
- Target resilient balance sheets by reviewing the list of solid balance sheet and fundamentals (22 results), which filters for companies with financial strength to handle tougher conditions.
- Hunt for quality at a discount with the 34 high quality undervalued stocks, which focuses on businesses trading below their assessed worth with solid fundamentals behind them.
- Build a steadier income stream by scanning the 6 dividend fortresses, where higher yielding payers with stronger backing are grouped in one place.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com