
ADMA Biologics (ADMA) Stock May Be Undervalued On Current Earnings
ADMA Biologics has delivered a striking long term return, yet the share price has dropped sharply over the past year. That mix of gains and setbacks puts a simple question in front of investors who follow ADMA Biologics: whether the current valuation is supported by the earnings the business is generating today.
- Over the past 5 years the stock has returned roughly 7x, which raises the issue of how much of ADMA Biologics' earnings power may already be reflected in the price.
- The business model depends on turning plasma collection and processing into durable profitability, so the quality and consistency of earnings can matter as much as any revenue headline for how traders frame the stock.
- There is a second opinion on ADMA Biologics worth weighing. See what analysts think ADMA Biologics's shares could be worth.
The stock's next move may depend on whether ADMA Biologics' current share price is in line with what its earnings can reasonably support.
To see how ADMA Biologics' recent swings compare with other earnings focused opportunities, line it up against 34 high quality undervalued stocks.
Does ADMA Biologics Look Undervalued on Earnings?
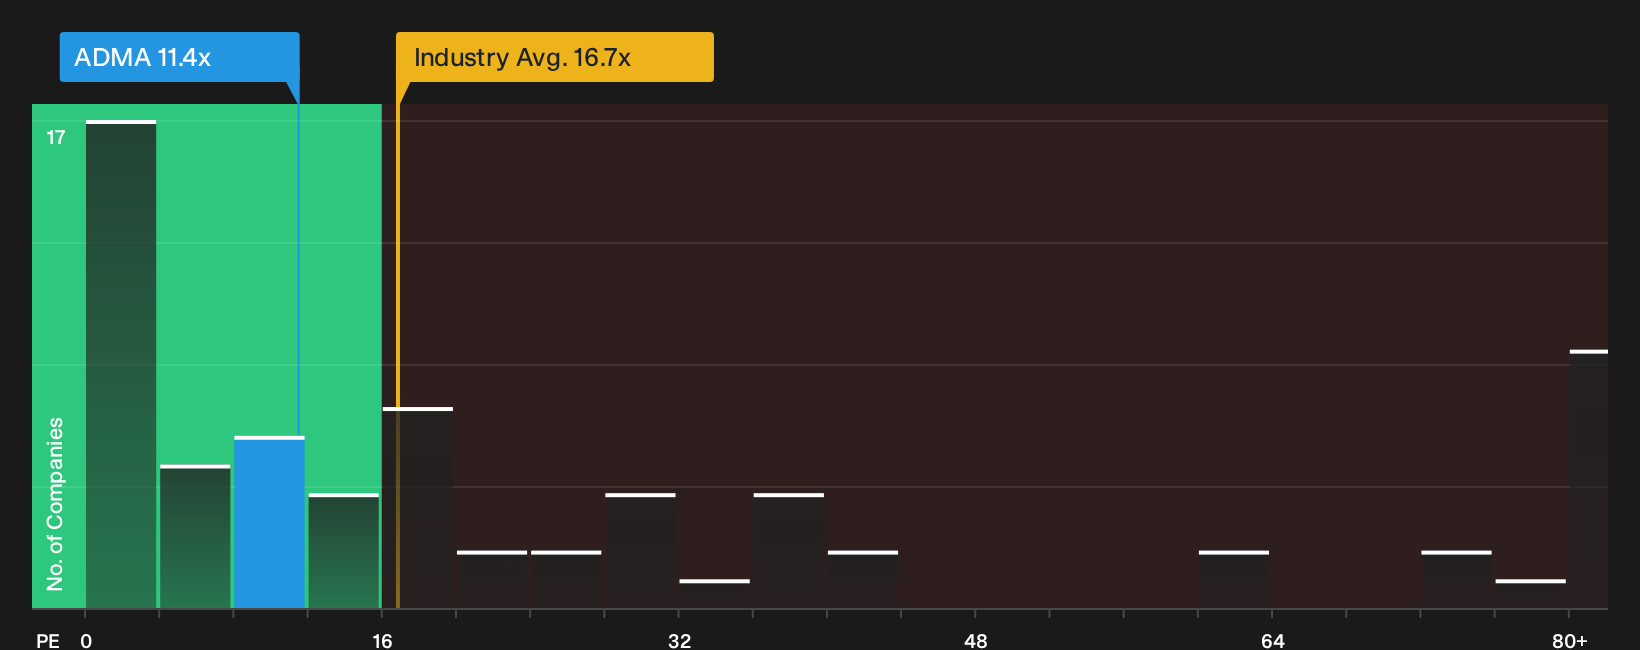
The P/E ratio works well for ADMA Biologics because the discussion here is anchored in the earnings the business is already producing. On this lens, the stock trades on about 11.4x earnings, which is well below the wider biotechs group on roughly 16.7x and sits even further under a peer set closer to 31.0x. That gap means the market is attaching a materially lower price tag to each dollar of ADMA Biologics' profit than it does for similar businesses.
A fair P/E based on ADMA Biologics' profile would sit higher than where the shares change hands today. This points to the stock screening as undervalued on this model rather than stretched. For a holder, the key question is whether the earnings that justify this lower multiple are durable given the economics of plasma collection and processing, or whether the discount is more about perceived risk that could linger. Explore the numbers behind ADMA Biologics's P/E valuation.
The ADMA Biologics Narrative: What Would Justify Today's Price?
Narratives take that P/E gap for ADMA Biologics and spell out which future paths for growth, margins and earnings would need to play out for the current share price to look cheap or expensive. Each one treats fair value as a thesis about how the business might perform over time that you can watch and reassess, rather than a static number on a single date. Narratives live on Simply Wall St's Community page.
One of the top community narratives on ADMA Biologics: 51% undervalued
"The recent debt refinancing, lowering the cost of capital and providing a new $300 million credit facility, enhances liquidity and financial flexibility…"
Discover why this Narrative puts ADMA Biologics at 51% undervalued.
One more ADMA Biologics check that sits beyond the share price math
Price ratios only tell part of the story, because how the leadership team runs ADMA Biologics and the way their pay packets are structured can tilt the risk and reward balance in ways earnings multiples never show. See who runs ADMA Biologics and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com