
What Highwoods Properties (HIW)'s Leasing Surge Means For Shareholders
- Highwoods Properties reported signing 1,100,000 square feet of second generation leases since July 1, 2026, including over 200,000 square feet of new leases, alongside closing US$74 million of non core office dispositions in Richmond and Atlanta.
- This combination of fresh leasing commitments and pruning of non core assets highlights how Highwoods Properties is leaning into demand for its better located offices while reducing exposure to older, less aligned properties.
- We will now explore how Highwoods Properties' heavy second generation leasing could reshape its investment narrative around occupancy and stability.
Highwoods Properties Investment Narrative Recap
To own Highwoods Properties, you need to believe modern, well located offices in its Sunbelt markets can keep attracting tenants even as remote and hybrid work limit overall demand. The recent 1,100,000 square feet of second generation leasing, including long term renewals, supports that idea by reinforcing occupancy and near term cash flow visibility.
The key short term catalyst is whether this leasing momentum shows up clearly in the upcoming October 27 third quarter 2026 results and in the commentary on occupancy and rent trends. The biggest current risk is that interest costs remain a strain while earnings are forecast to decline, which could limit financial flexibility if leasing softens again.
The upcoming third quarter 2026 earnings release and conference call is the announcement that matters most in this context. Investors will want to see how Highwoods Properties connects the recent leasing and US$74 million of dispositions to metrics like occupancy, funds from operations, and interest coverage, without relying on one off gains.
This creates a near term test of the story. Management can outline how much of the 1,100,000 square feet is already contributing to rent, how much is still in the signed not yet commenced bucket, and what that means for future revenue in markets where structural office oversupply and ongoing hybrid work remain key operational headwinds.
Highwoods Properties' current analyst narrative points to revenues of US$919.4 million and earnings of US$91.6 million by 2029, based on an assumed 3.1% yearly revenue growth rate and a move from earnings today of US$166.4 million to that US$91.6 million figure. This represents an earnings decline of about US$74.8 million over the period.
Uncover how Highwoods Properties' fair value indicates a 5% potential upside to its current price before the market adjusts for the closing discount.
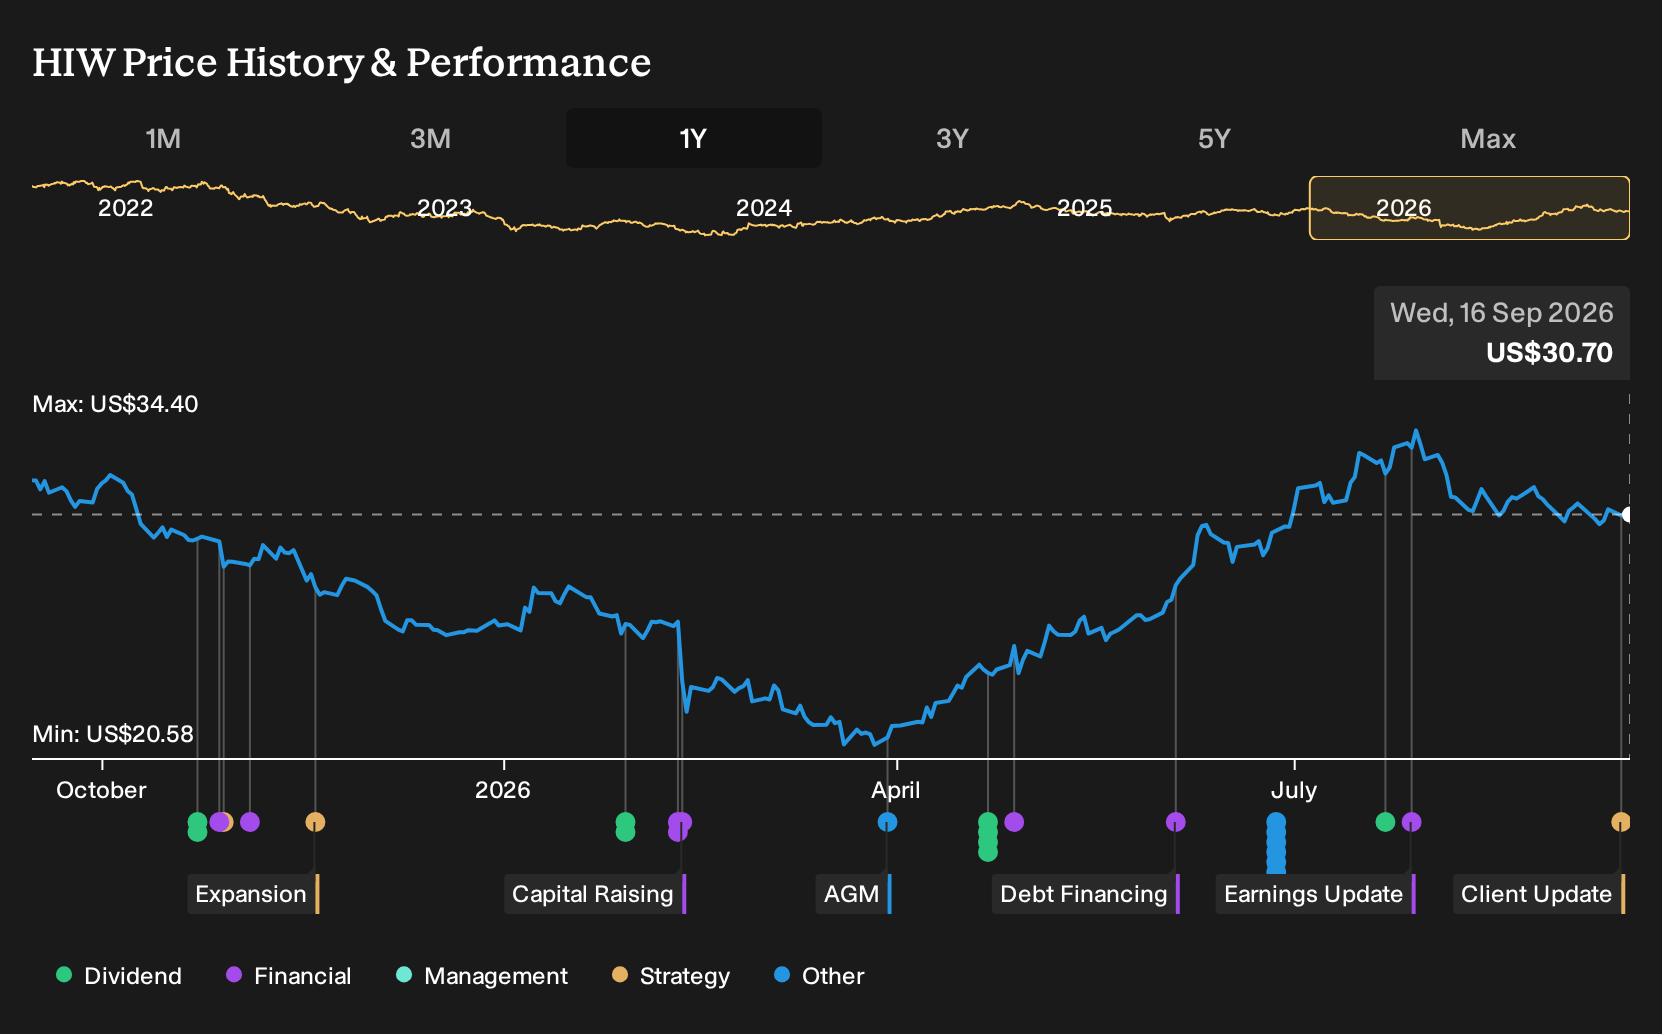
Exploring Other Perspectives
Some of the most optimistic analysts latch onto the development pipeline as the real swing factor for Highwoods Properties. Before this leasing and disposition news, they were already penciling in about US$958.8 million of revenue and US$89.4 million of earnings by 2029. You can treat those pre news forecasts as one possible path and compare them with your own view.
Explore 2 other Highwoods Properties fair value estimates, including one that suggests potential upside of as much as 14% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Highwoods Properties research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Highwoods Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Highwoods Properties' overall financial health at a glance.
Looking For More Ideas Beyond Highwoods Properties?
If the Highwoods Properties story has you thinking about balance sheets, cash flow and income resilience, it can be useful to line it up against other opportunities using the Simply Wall St Screener.
Here are a few different angles to broaden your watchlist.
- If resilience and lower volatility appeal to you, scan a curated set of 11 resilient stocks with low risk scores that may better match a capital preservation mindset.
- If you want income to play a bigger role in your returns, check out a focused collection of 6 dividend fortresses that combine yield with underlying fundamentals.
- If you like finding potential early stage opportunities before they are widely followed, review a targeted group of 16 high quality undiscovered gems that pair financial strength with room to grow.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com