
Bank of America (BAC) CEO Warns Of Sharp Fee Drop And Flat Trading Revenue
- Bank of America (NYSE:BAC) CEO Brian Moynihan warned that third quarter investment banking fees are set to decline sharply.
- Moynihan also flagged that third quarter trading revenue is expected to be broadly flat, pointing to softer capital markets activity.
- The chief executive highlighted cooling financing and prime brokerage activity in his comments, despite other business lines remaining more resilient.
- The warning on weaker investment banking fees and flat trading revenue is important, but it should not dominate your BAC view. We have also spotted 4 other big wins worth knowing about at Bank of America.
For readers weighing this update and looking for more ideas in related areas, the next stop is 32 AI small caps.
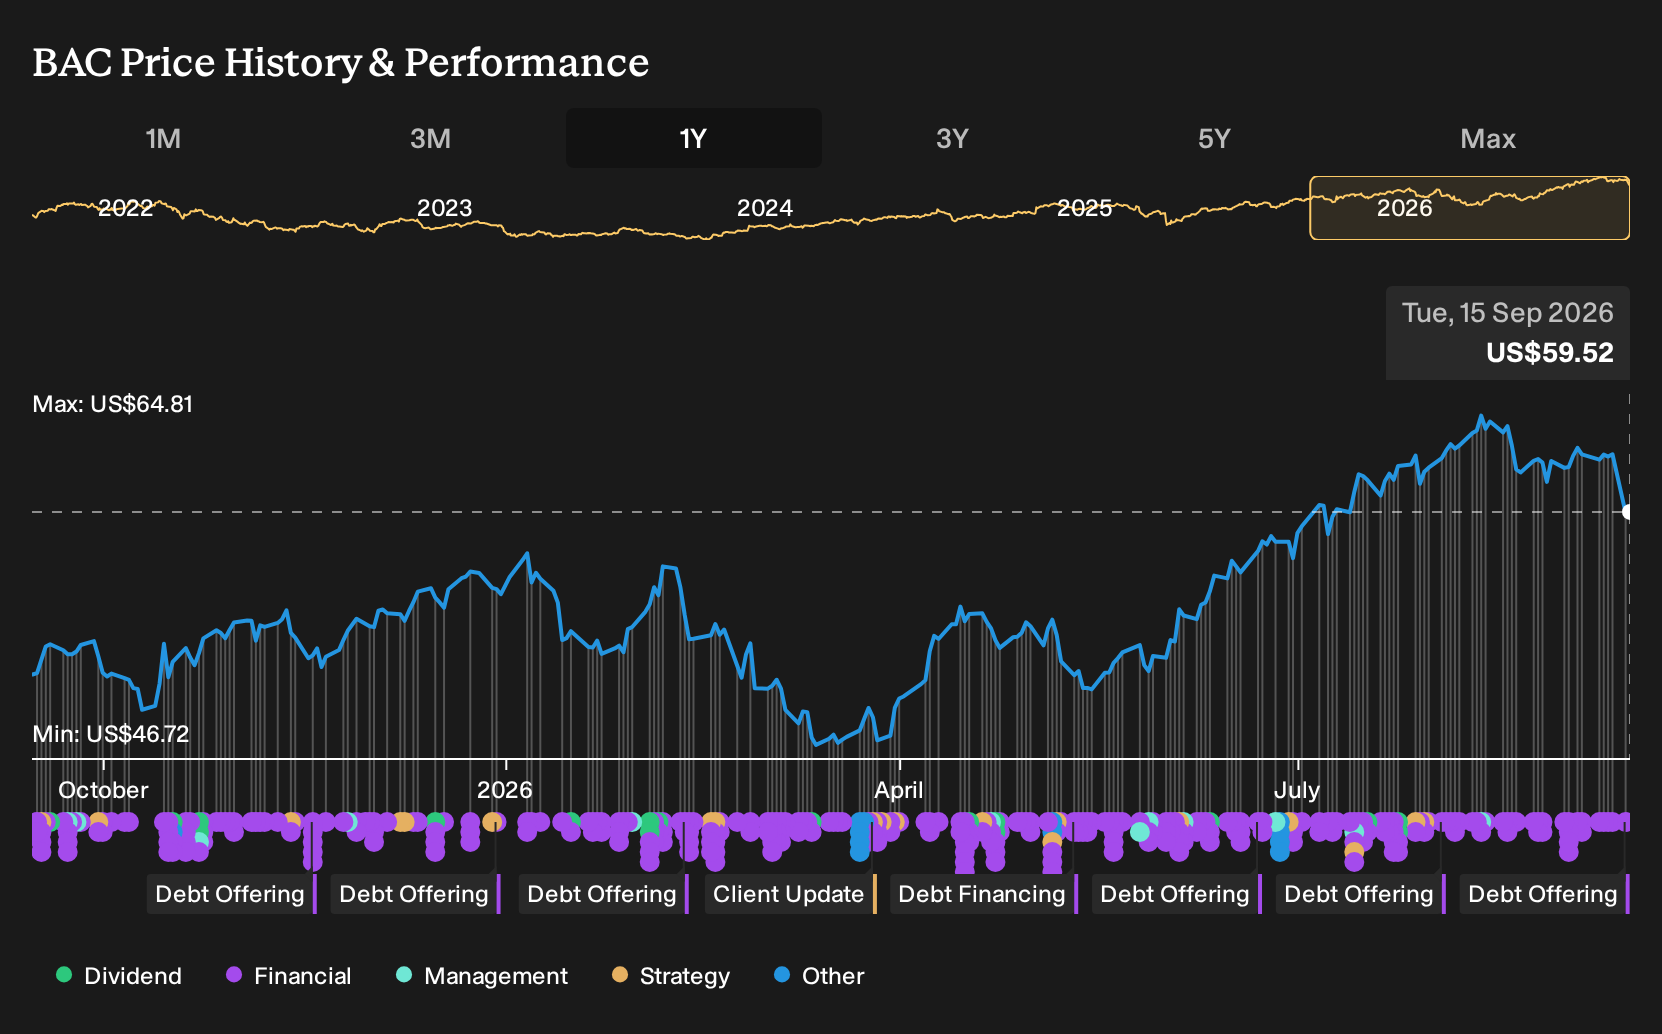
Bank of America is one of the largest US banks, with a US$416.2b market cap and a broad mix of consumer, business and institutional clients, so a slowdown in investment banking and trading affects only part of a much wider lending and services franchise.
See which insiders are buying and selling Bank of America following this latest news.
What Moynihan’s warning really signals for the Bank of America Narrative
For Bank of America, the Narrative is not about flawless quarters. It is about using digital scale, AI and interest rate positioning so that more reliable lending and deposit income offsets choppier capital markets results like this fee slowdown.
"Strategic actions around asset repricing and interest rate management, including fixed-rate asset re-pricing and cash flow hedge benefits, could improve net interest income, supporting future earnings growth..."
See how the full story points towards a $68.11 fair value for Bank of America.
The market reaction focuses on softer investment banking fees and flat trading. That response risks missing that the existing thesis already treats these activities as volatile add ons, while the central bet is on net interest income, digital engagement and AI driven efficiency doing the heavy lifting over time for Bank of America.
What Moynihan’s comments really test is the assumption that higher for longer rates and balance sheet management can steady earnings when capital markets cool, especially versus peers like JPMorgan or Citigroup that also lean on deal making. If investors expected capital markets strength to carry the story, this update simply realigns sentiment with the original Narrative.
The same headline looks encouraging or worrying depending on whether an investor’s story for Bank of America is built around capital markets momentum or around the slower grind of loans, deposits and cost control.
Add Bank of America to your Watchlist and get alerts as these catalysts play out.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com