
Should Heat Control Patent Require Action From AST SpaceMobile Stock Investors?
- AST SpaceMobile recently secured a U.S. patent for a tiled antenna structure with integrated heat pipes that manage extreme temperature swings across its large Block 2 BlueBird satellite arrays.
- The patent targets a core engineering bottleneck for high power direct to device satellites, since more efficient thermal control can support larger arrays, higher duty cycles, and potentially lower per unit capacity costs over time.
- This development may influence how investors think about AST SpaceMobile's overall investment narrative in relation to thermal management in its satellite arrays.
Scan the satellite and telecom space beyond AST SpaceMobile by lining up how it compares against 16 high quality undiscovered gems that are still flying under most radars.
AST SpaceMobile Investment Narrative Recap
To own AST SpaceMobile, you need to believe its capital intensive plan to build a direct to phone satellite network can convert contracted MNO relationships and spectrum access into meaningful usage. In the near term, the key issue is execution on satellite deployment and service activation. The new securities class action focuses on disclosure and expectations but does not directly affect how well the hardware or network operates.
The lawsuit adds another layer of uncertainty around capital access, especially given the size and frequency of recent convertible note offerings. That matters because a major current risk is funding a multibillion-dollar buildout without eroding shareholder value too quickly, while still keeping pace with competitors in direct to device coverage.
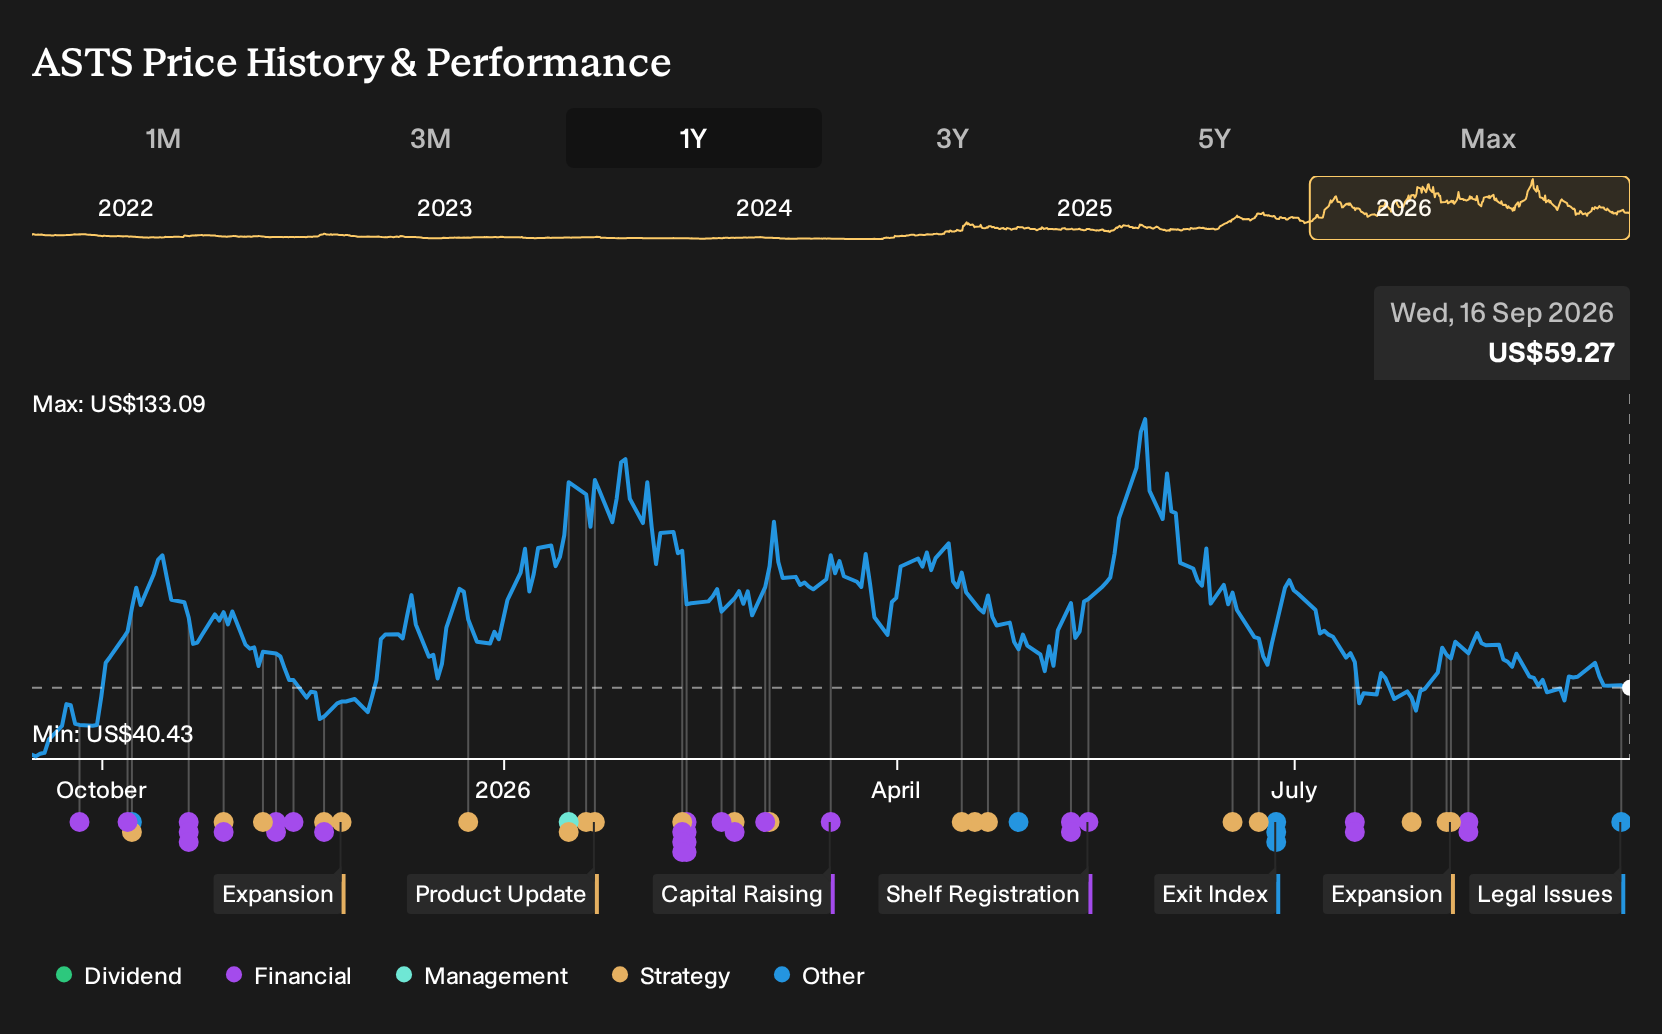
The most relevant backdrop to this legal action is AST SpaceMobile’s repeated convertible note offerings, including the July 2026 US$1.0 billion 1.625% convertible issue due 2034 with an option for an extra US$150 million. These deals highlight how dependent the business model is on external financing as it works toward a larger BlueBird constellation and service rollout.
For you as an investor, those financings intersect directly with today’s main catalyst and risk. Progress toward 45 to 60 satellites and conversion of over US$1.0 billion in contracted commitments into active service both rely on sustained spending. At the same time, each new capital raise and the lawsuit’s allegations keep the focus on dilution, debt load, and disclosure quality.
AST SpaceMobile Forecasts and Valuation Set-Up
AST SpaceMobile's narrative projects US$2.2b revenue and US$190.9 million earnings by 2029. This is based on the assumption of revenue growth of 165.5% per year and an earnings change of roughly US$809.7 million from a loss of US$618.8 million today.
Uncover why AST SpaceMobile's fair value indicates a 32% potential upside to its current price, which could narrow quickly if sentiment around AST SpaceMobile shifts.
Exploring Other Perspectives
Some of the lowest AST SpaceMobile analysts focus on competitive pressure rather than technology wins such as this new thermal patent. Before the lawsuit, this more bearish group was only penciling in about US$2.1b of revenue and roughly US$187.2 million of earnings by 2029. That is a far more cautious narrative. It shows how sharply opinions can differ and why you may want to compare several viewpoints, which could shift as this news is digested.
Explore 13 other AST SpaceMobile fair value estimates, including one that suggests as much as 71% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AST SpaceMobile research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AST SpaceMobile. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AST SpaceMobile's overall financial health at a glance.
Looking for more investment ideas beyond AST SpaceMobile?
Once the AST SpaceMobile story is on your radar, it can help to zoom out and line up a wider watchlist using the Simply Wall St Screener so you can compare risk, balance sheet strength, and income potential across a broader set of businesses.
- If you want resilience to be your starting point, scan a 11 resilient stocks with low risk scores that may help when you are prioritizing capital preservation.
- If balance sheet strength is your priority, line up a list of solid balance sheet and fundamentals (22 results) that can sit alongside higher risk ideas like AST SpaceMobile.
- If income is part of your plan, look at a 6 dividend fortresses that could support a yield focused approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com