
Waste Connections (WCN) Could Be 23% Undervalued Following Its Recent Pullback
Waste Connections (WCN) has drawn fresh attention after recent trading left the shares down about 5% over the past month and roughly 9% lower over the past year. Investors are now reassessing what that shift means.
Recent trading paints a picture of cooling momentum. The share price is now at US$156.50, with a 7 day share price return that declined 2.95% and a 30 day share price return that fell 5.16%. The 1 year total shareholder return is down 8.95%, while over 5 years the total shareholder return of 23.98% points to a steadier long run experience for investors willing to hold through shorter term swings.
Scan beyond Waste Connections and see how other rubbish and recycling operators stack up in our hand picked 11 resilient stocks with low risk scores, which aims to surface steadier, lower risk options in the sector.
For Waste Connections, a pullback after a solid multi year run can look tempting right away. The real question is whether the current valuation already reflects that reset or still makes it worth waiting for a cheaper entry.
Most Popular Narrative: 23% Undervalued
On the widely followed narrative, Waste Connections screens as undervalued, with a fair value of $203.92 set against the last close at $156.50 and a discount rate of 6.94% underpinning that view.
Robust acquisition activity, with annualized revenues closed already over $125 million, and a strong balance sheet position Waste Connections well for continued growth and successful integration of acquisitions, supporting future revenue and earnings growth. The integration of a strategic state-of-the-art recycling facility in New Jersey is expected to complement their expanding New York City franchise, potentially enhancing service capabilities and driving revenue growth.
See why 19 investors see Waste Connections as 23% undervalued.
Result: Fair Value of $203.92 (UNDERVALUED)
Still, Waste Connections relies heavily on acquisitions and commodity-linked recycling revenue. Weaker deal execution or lower pricing on recyclables could quickly challenge that undervalued narrative.
Find out about the key risks to this Waste Connections narrative.
Another View On Waste Connections Valuation
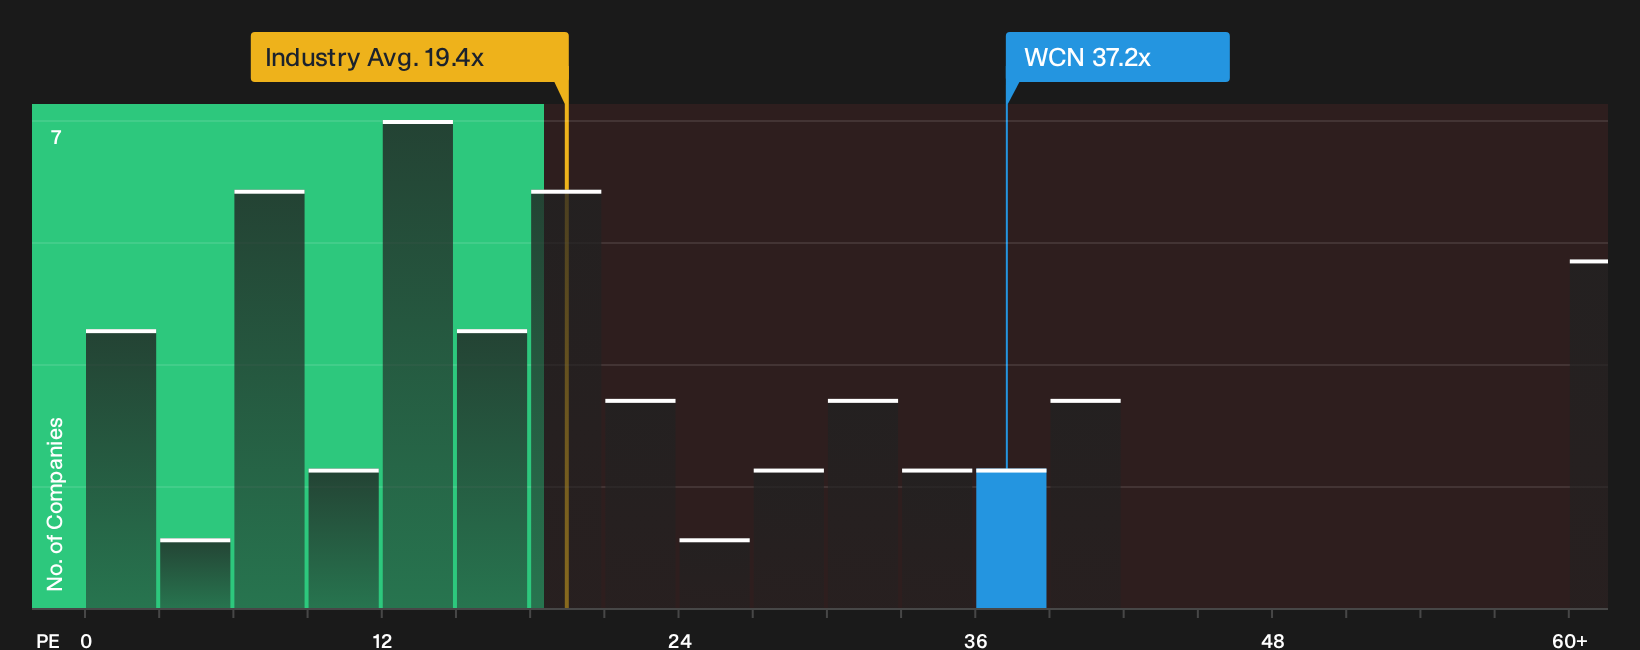
On the flip side of that 23% undervalued story, Waste Connections trades on a rich P/E of 37.2x. The fair ratio sits at 26.3x, the Commercial Services industry around 19.4x, and peers near 28.7x. That premium points to execution risk if expectations cool. Which reference point do you trust most?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Waste Connections share price and valuation can look confusing at first glance, so move quickly to check the full risk and reward profile for yourself. To see both sides of the story in one place, review the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Waste Connections?
If Waste Connections has you rethinking your portfolio, use this moment to scan fresh ideas so you are not relying on a single opportunity.
- Target stronger balance sheets by checking companies in the list of solid balance sheet and fundamentals (22 results) that combine financial resilience with more predictable fundamentals.
- Hunt for potential value by reviewing the 33 high quality undervalued stocks and compare pricing against quality metrics rather than just recent share moves.
- Strengthen your income stream by assessing firms in the 6 dividend fortresses that pair higher yields with an emphasis on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com