
China Nonferrous Mining (SEHK:1258) Rebounds 2%, Is It Above Fair Value?
China Nonferrous Mining (SEHK:1258) drew investor attention after a 2% gain in the latest session, even though the share price remains down about 12% over the past week.
That bounce comes after a sharp 7 day share price return decline of 11.91%. However, China Nonferrous Mining still carries a 30 day share price return of 4.00% and a 90 day share price return of 15.04%, while the 1 year total shareholder return sits at 30.58%.
Scan how China Nonferrous Mining compares with other copper focused producers by reviewing the hand picked 29 top copper producer stocks for potential ideas riding similar price momentum.
After that quick rebound, the real tension for China Nonferrous Mining sits in the gap between its HK$15.60 share price and valuation estimates. How far from fair value does this move actually leave you?
Preferred P/E of 13.5x for China Nonferrous Mining: Is it justified?
China Nonferrous Mining trades on a P/E of 13.5x, which puts the HK$15.60 share price in a zone where the market is paying up compared with both its own fair ratio and parts of its peer group.
The P/E multiple compares the current share price to earnings per share. For a copper and cobalt producer like China Nonferrous Mining, it effectively reflects what investors are willing to pay today for each dollar of profits generated from its operations in Zambia and the Democratic Republic of Congo.
Relative to the Hong Kong Metals and Mining industry average of 10.4x, the stock carries a richer P/E tag. That suggests buyers are accepting a premium compared with the sector. At the same time, the valuation is described as good value compared with a peer average of 30.7x, which points to a cluster of higher rated competitors that trade on far steeper earnings multiples. The estimated fair P/E of 12x also sits below the current 13.5x, a level the market could move toward if sentiment or expectations cool from here.
Explore the SWS fair ratio for China Nonferrous Mining.
Result: Price-to-earnings of 13.5x (OVERVALUED)
Still, the China Nonferrous Mining story can change quickly if copper or cobalt pricing weakens, or if its African operations face regulatory or operational setbacks.
Find out about the key risks to this China Nonferrous Mining narrative.
Another view on China Nonferrous Mining’s value
The SWS DCF model presents a very different picture for China Nonferrous Mining. According to this view, the HK$15.60 share price sits well below an estimated future cash flow value of HK$50.94, which implies a large valuation gap. Is that a safety margin, or is the model too optimistic?
Look into how the SWS DCF model arrives at its fair value.
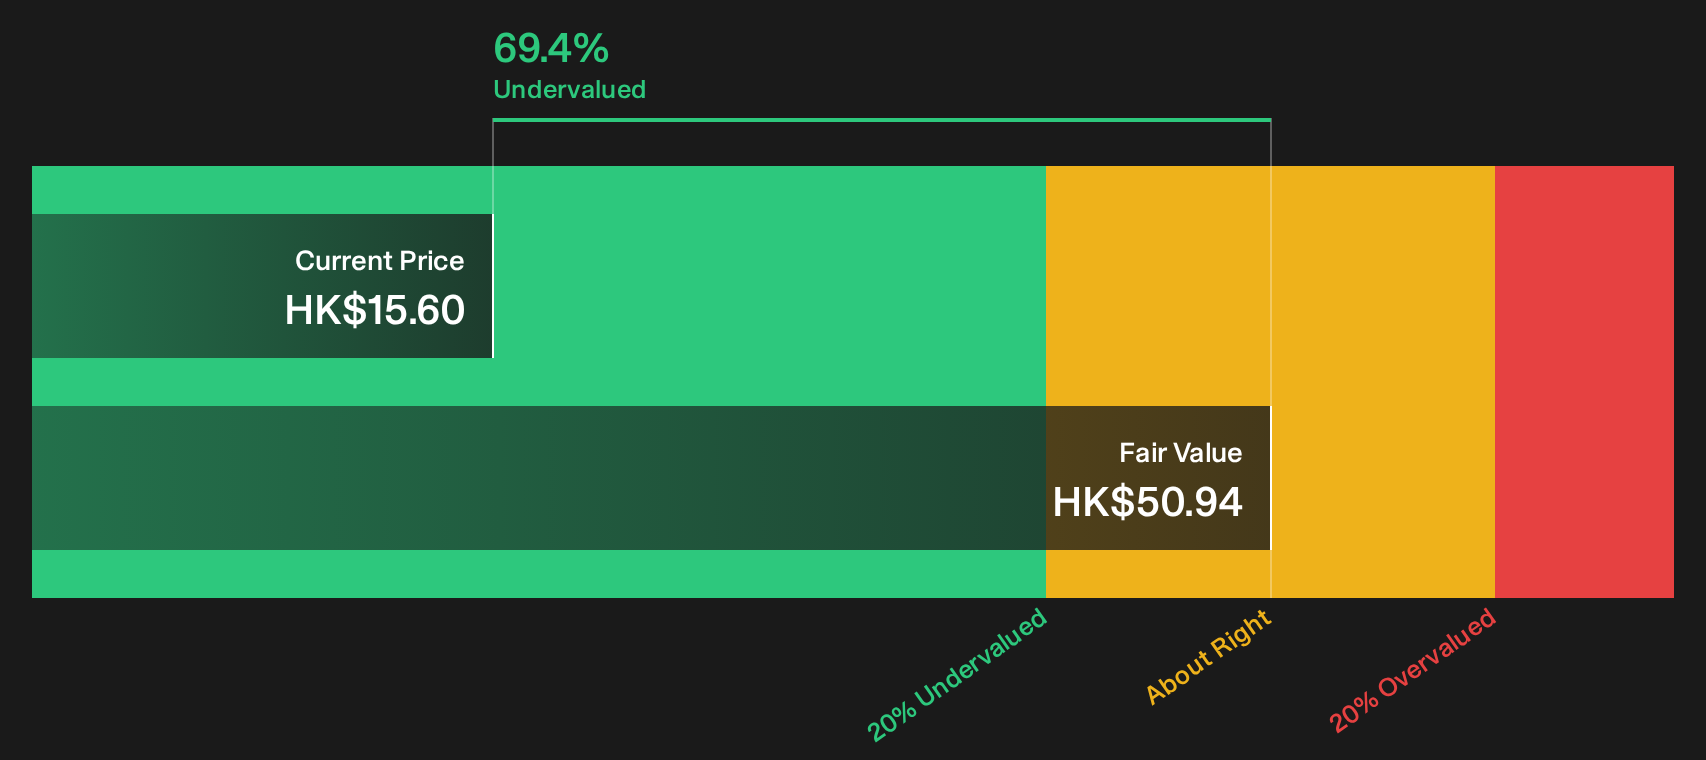
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Nonferrous Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 189 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the mixed signals around China Nonferrous Mining tilt more positive or cautious for you personally? Act quickly, pull up the underlying metrics, and pressure test your own thesis by checking the 3 key rewards.
Looking for more investment ideas beyond China Nonferrous Mining?
If China Nonferrous Mining has your attention, do not stop here. Broaden your watchlist and give yourself more options when markets move.
- Target potential mispricing by scanning companies that screen as 189 high quality undervalued stocks and see which ones deserve a closer look.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (194 results) that can help you filter for financial strength before the next bout of volatility hits.
- Look for emerging stories by checking out 619 high quality undiscovered gems that most investors may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com