
Dah Sing Banking Group (SEHK:2356) Publishes Investor Confidence Index, Is The Stock Still Undervalued?
Dah Sing Banking Group (SEHK:2356) drew fresh attention after Dah Sing Bank published the second edition of its 2027 Investor Confidence Index. The report highlighted strong sentiment among affluent Hong Kong investors and rising interest in diversified, digitally delivered investment solutions.
At a share price of HK$14.45, Dah Sing Banking Group has seen a 90 day share price return of 15.6% and a year to date share price return of 33.43%. The 1 year total shareholder return of 56.69% and 3 year total shareholder return above 2.5x suggest longer term momentum has been strong, even as the 7 day share price return has eased slightly. This hints that investors are weighing the upbeat confidence index against past gains rather than reacting to a single headline.
Scan beyond Dah Sing Banking Group and compare it with a hand picked 189 high quality undervalued stocks that share solid cash generation and balance sheet strength.
Bulls see Dah Sing Banking Group as a still cheap, cash generative bank after a strong run. Bears see a cyclical beneficiary that already priced in the good news. Which case does the current valuation support?
Preferred Multiple of 7.6x P/E: Is it justified?
Dah Sing Banking Group trades on a P/E of 7.6x, slightly above its own fair P/E estimate of 7.1x and clearly ahead of the Hong Kong banks sector on 5.2x. At a last close of HK$14.45 and with the SWS DCF model pointing to an intrinsic value of HK$19.61, investors are effectively paying a richer earnings multiple while the cash flow model still flags a discount.
The P/E ratio compares what you pay today for each dollar of earnings. For a lender like Dah Sing Banking Group, where profit is shaped by credit quality, funding costs, and fee income, this measure gives a quick sense of how much confidence the market has in the durability of those profits.
Here the signals are mixed. On one hand, Dah Sing Banking Group shows high quality earnings, net profit margins of 42.1% versus 41% a year earlier, and earnings growth over the past year of 19.4% compared with 8% for the Hong Kong banks industry. On the other hand, the stock is described as expensive relative to both its fair P/E of 7.1x and the peer average of 7.2x. This suggests investors are already paying up for that stronger profit profile rather than getting it at a clear discount.
The premium is even more pointed when set against the broader Hong Kong banks group, where the average P/E sits at 5.2x. That gap implies the market is assigning Dah Sing Banking Group a noticeably higher valuation than sector peers. The fair ratio also points to a level the multiple could move toward if enthusiasm fades or earnings expectations change.
Explore the SWS fair ratio for Dah Sing Banking Group.
Result: Price-to-earnings of 7.6x (OVERVALUED)
Still, Dah Sing Banking Group faces clear risks if credit quality softens or investor appetite for Hong Kong financials cools and drags on its valuation premium.
Find out about the key risks to this Dah Sing Banking Group narrative.
Another View: Cash Flows Say Dah Sing Banking Group Is Cheap
The earnings multiple paints Dah Sing Banking Group as fully priced, yet the SWS DCF model tells a different story. At HK$14.45 against an estimated cash flow value of HK$19.61, the shares screen about 26% below that fair value. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
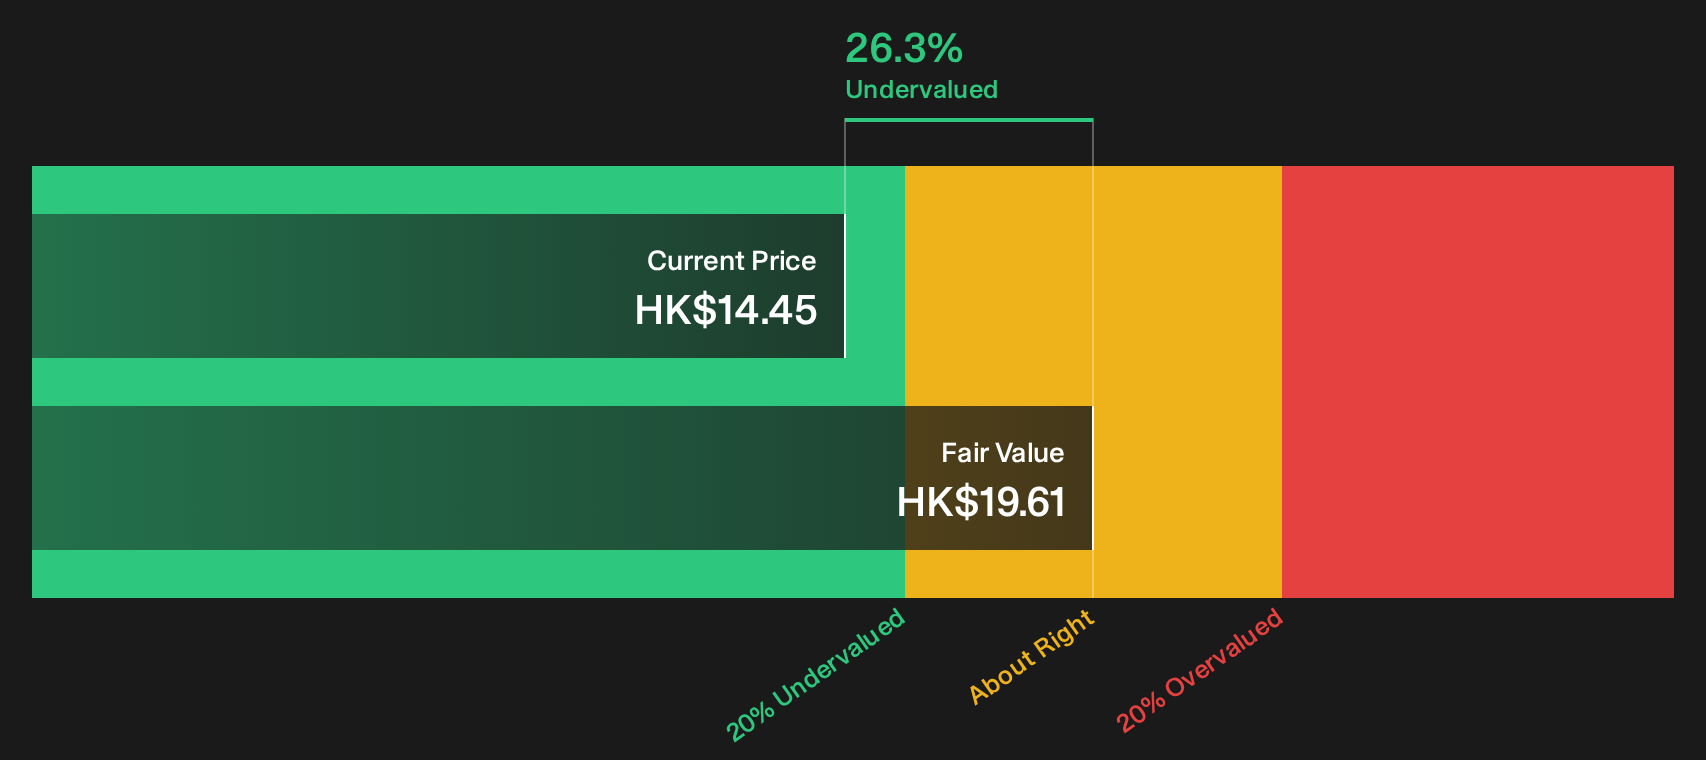
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Dah Sing Banking Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 189 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Dah Sing Banking Group so far, with both risks and rewards in play, mean the next move comes down to your own judgment. If you want a clear view of what could go right or wrong from here, take a look at the 3 key rewards and 3 important warning signs
Looking for more Dah Sing Banking Group sized ideas?
If you stop with Dah Sing Banking Group, you risk missing other opportunities that match your risk profile, income needs, and return expectations across the market.
- Target resilient balance sheets and steady fundamentals with a curated list of solid balance sheet and fundamentals (194 results) that helps you focus on financial strength first.
- Hunt for quality at a markdown by scanning a focused 189 high quality undervalued stocks that filters for both cash generation and robust balance sheets.
- Stack potential returns with income by reviewing a hand picked 161 dividend fortresses built around businesses offering higher yields with stability in mind.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com