
How Top HR Product Recognition Will Impact Paychex (PAYX) Stock
- Paychex’s AI-powered WISE intelligence engine was recently named a Top HR Product of the Year for 2026 by HR Executive, recognizing its embedded AI and guidance that help clients reduce payroll errors and streamline HR workflows.
- This award spotlights Paychex’s push to make AI a core part of day to day HR operations, which directly targets client pain points around accuracy, compliance, and efficiency across its human capital management platform.
- We will look at how Paychex’s investment narrative around AI driven HCM tools is affected by WISE gaining top HR product recognition.
Scan beyond Paychex and this WISE headline by checking a curated group of HR and automation peers through the 38 robotics and automation stocks.
Paychex Investment Narrative Recap
To own Paychex, you need to believe it can keep turning a broad HCM platform into steady fee income, while managing client churn and pricing pressure. In the near term, the main swing factor still appears to be execution on technology and automation, which influence operating margin and client retention more than any single product award.
The biggest risk remains pressure on profitability from higher employee costs, smaller deal sizes, and clients trading down on benefits. The WISE recognition supports the narrative around AI and workflow automation, but by itself it does not materially change those demand and cost risks at this time.
The WISE award aligns most directly with Paychex’s push into AI driven tools such as its Gen AI powered HR Copilot. Both products support the same operational goal: use embedded intelligence to cut payroll errors, reduce manual work, and keep customers on the platform rather than shopping for alternatives.
For potential catalysts, this matters because Paychex is already relying on automation and technology to support operating margin and possible cost synergies related to the pending Paycor acquisition. Execution on AI features like WISE and HR Copilot may help offset softer macro trends, but they coexist with integration risk and client behavior shifts that still require close monitoring.
How WISE Fits Into Paychex’s Earnings Roadmap
Paychex's narrative projects US$7.6b revenue and US$2.4b earnings by 2029. That trajectory assumes 5.4% yearly revenue growth and an earnings increase of about US$600m from US$1.8b today.
Uncover why Paychex's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
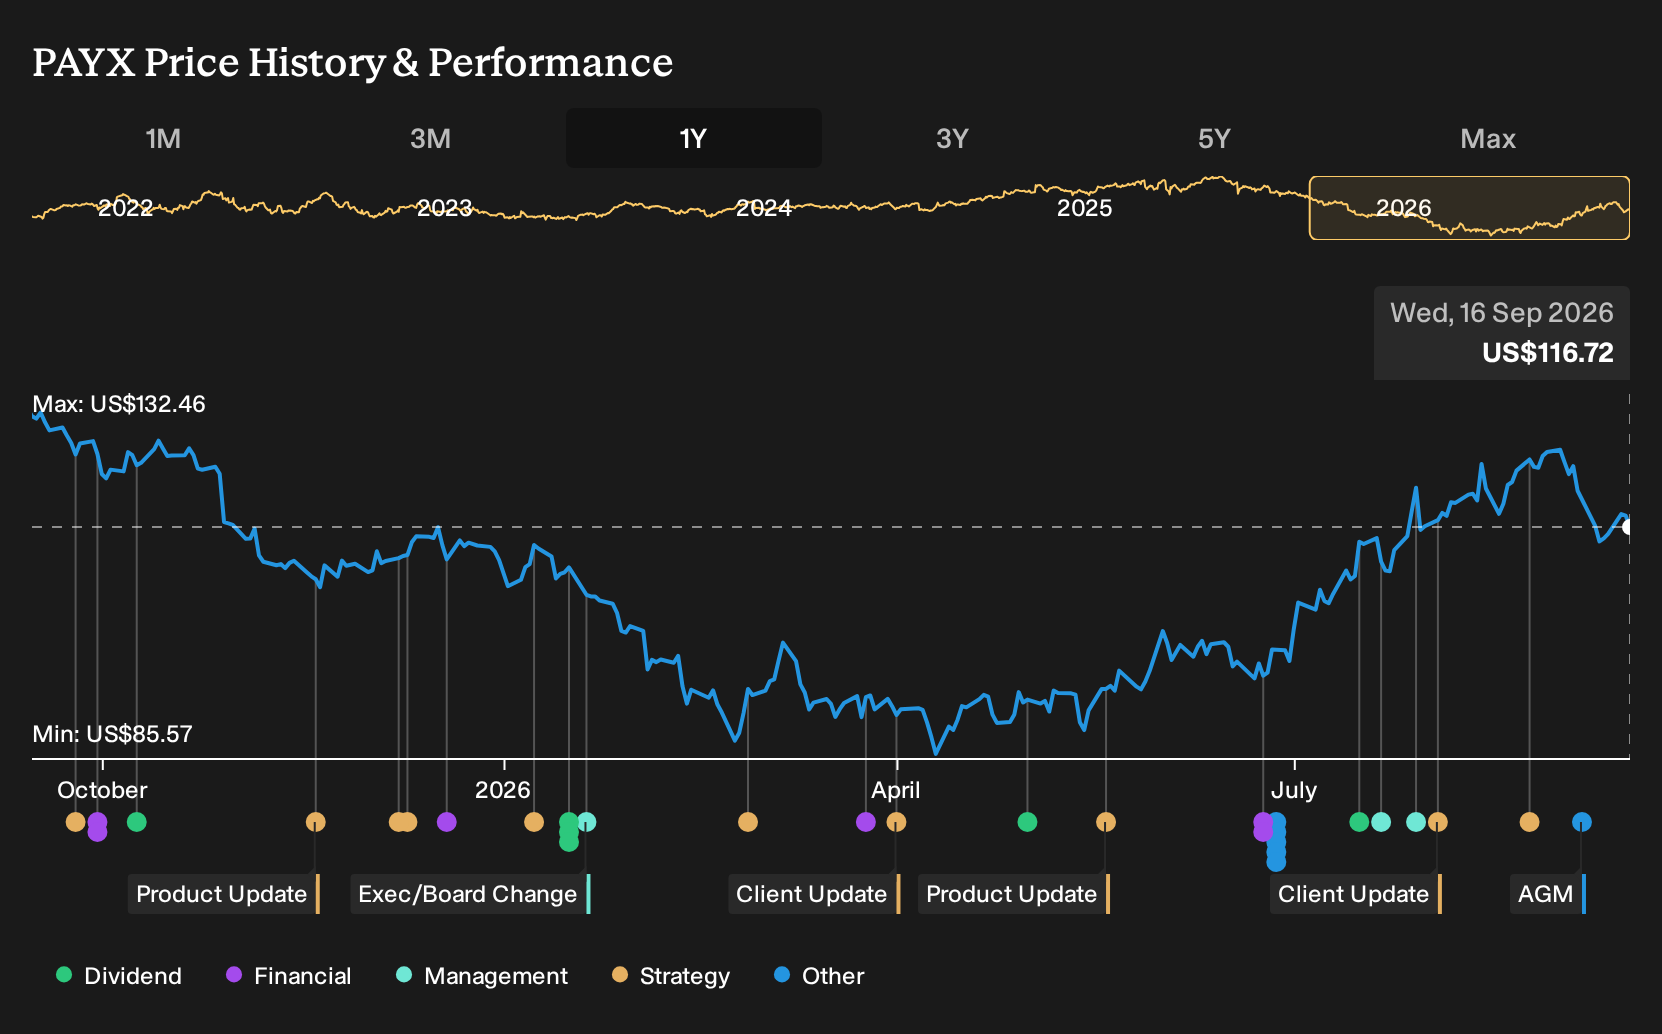
Exploring Other Perspectives
Some of the most optimistic analysts already expected Paychex to reach about US$7.7b revenue and US$2.5b earnings by 2029, helped by stronger AI monetization and Paycor synergies. You might see the WISE award and wonder if that upbeat view gains more support. Opinions vary widely, so explore several narratives before deciding what feels reasonable to you.
Explore 3 other Paychex fair value estimates, including one that suggests potential upside of up to 63% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Paychex research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Paychex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Paychex's overall financial health at a glance.
Looking For More Investment Ideas Beyond Paychex?
If the Paychex story has you thinking about portfolio balance, use the Simply Wall St screener to line up a few alternatives that match your risk and income preferences.
- For investors who want income resilience with yield, scan a focused group of potential “paycheck” generators through the 6 dividend fortresses.
- If capital preservation matters most to you right now, filter for businesses with steadier profiles using the 11 resilient stocks with low risk scores.
- When you want strong fundamentals without the crowded attention, sort through a curated pool of quieter opportunities via the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com