
Albertsons Companies (ACI) Following Meg Whitman’s Appointment, Is The Undervalued Case Back In Focus?
Albertsons Companies (ACI) just made a high profile board move by appointing Meg Whitman as Executive Chair in a newly created role that could influence how the grocer approaches technology, capital allocation and long term strategy.
Despite the headline appointment and a recent nationwide rollout of Once Upon A Coconut products across Albertsons Companies banners, the stock tells a mixed story. The 7 day share price return of 5.99% sits against a year to date share price decline of 27.44%, while the 1 year total shareholder return has fallen 28.79%, suggesting that recent momentum is improving off a weak longer term base.
Spot under-pressure supermarket plays like Albertsons Companies and compare them with other retailers showing stronger momentum and fundamentals using our curated list of solid balance sheet and fundamentals (22 results).Albertsons Companies now sits at an awkward intersection where a high profile Executive Chair and new product wins meet a share price that has trended lower. Is this business being repriced on fundamentals or on mood?
Most Popular Narrative: 11% Undervalued
Albertsons Companies trades at $12.56 against a widely followed fair value view of $14.19. This frames the current debate around execution, cost savings and digital progress rather than a simple near term earnings miss.
Modernization through technology investments, such as automation, AI-driven inventory/pricing, and centralized buying, are streamlining operations, reducing labor and supply chain costs, and positioning the company for long-term margin expansion and improved net earnings.
See why 20 investors see Albertsons Companies as 11% undervalued.
Result: Fair Value of $14.19 (UNDERVALUED)
Still, the bullish narrative around Albertsons Companies collides with real pressure from rising labor costs and ongoing market share losses, which could drag on already thin profit margins.
Find out about the key risks to this Albertsons Companies narrative.
Another View on Albertsons Companies Valuation
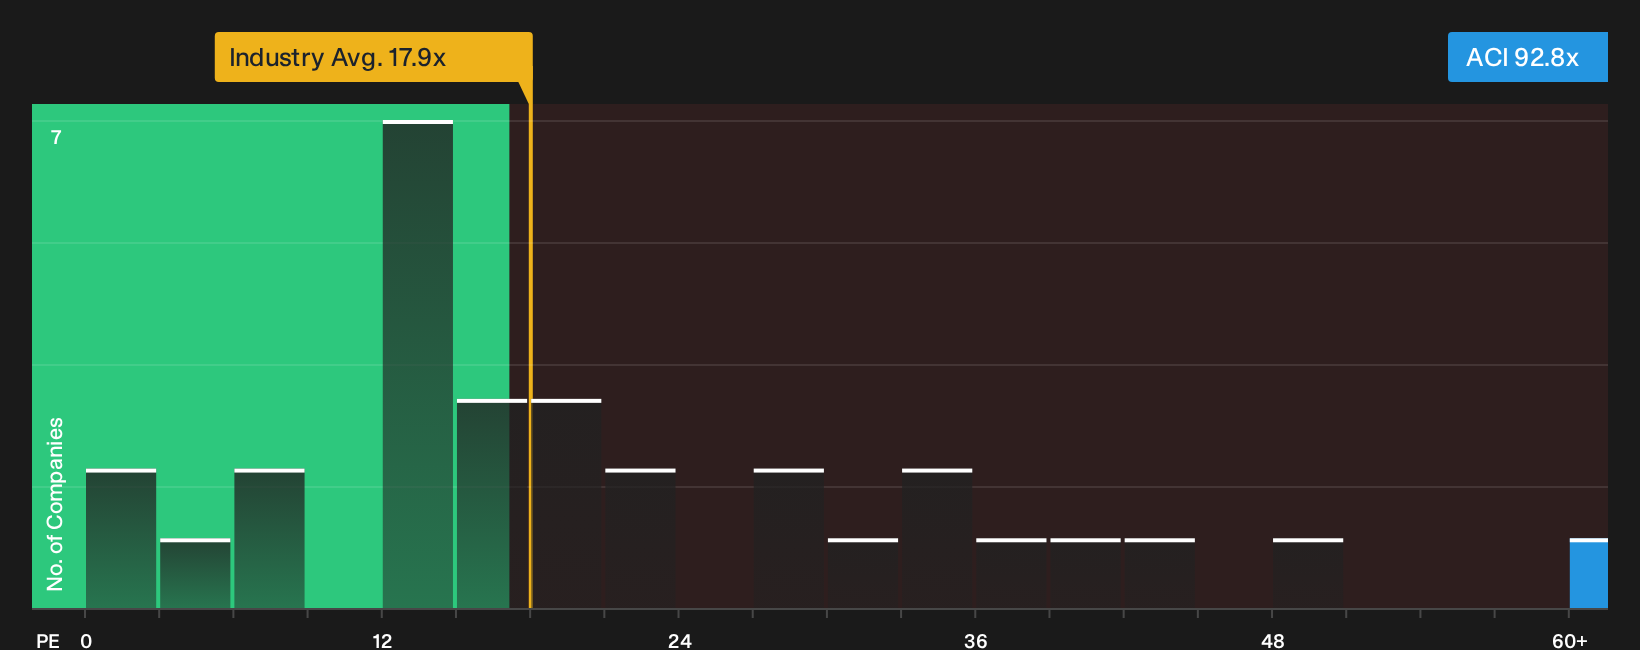
The fair value story for Albertsons Companies looks very different once you stop looking at the $14.19 target and focus on the P/E ratio instead. The stock trades on about 92.8x earnings, while the US Consumer Retailing group averages roughly 17.9x.
Even against an estimated fair ratio of 33x, Albertsons Companies screens as expensive on this simple earnings yardstick, which points to meaningful valuation risk if sentiment or profit expectations slip again. Which story do you think the market ends up believing: the discount to fair value or the premium P/E?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Albertsons Companies is split, with potential upside and clear concerns both on the table, so move quickly and stress test the data for yourself. To weigh both sides with one view, start with these 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Albertsons Companies?
Do not stop your research with Albertsons Companies. Broaden your watchlist with other businesses that line up with your risk tolerance and return goals using focused stock screens.
- Target potential mispricings by scanning for quality companies trading below estimated worth through the 33 high quality undervalued stocks.
- Identify income-focused opportunities by zeroing in on stocks that feature resilient payouts with the 6 dividend fortresses.
- Support capital preservation by concentrating on businesses that pair sturdy finances with disciplined fundamentals inside the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com