
Why UMH Properties (UMH) Is Getting Attention Today
UMH Properties (UMH) just put product design in the spotlight, returning to HUD’s Innovative Housing Showcase with two new manufactured homes that push construction formats for affordable housing into fresh territory.
For context, UMH Properties’ recent share price action has been subdued, with the stock at US$15.58 and a 30-day share price return that declined 3.47%. However, the 1-year total shareholder return of 9.46% and 3-year total shareholder return of 27.23% point to steadier long run progress, with momentum rebuilding over the past 90 days as the share price return improved 3.45%.
Spot emerging housing REIT momentum by comparing UMH Properties with our hand picked 16 high quality undiscovered gems, which pair affordable housing themes with stronger fundamentals.UMH Properties has quietly rebuilt some share price momentum while still trading at US$15.58. Does the balance of risk and potential reward still lean in favour of new buyers as the valuation case stacks up next?
Most Popular Narrative: 20% Undervalued
UMH Properties trades at $15.58 against a widely followed fair value estimate of $19.43. As a result, the narrative frames the current quote as leaving a material valuation gap on the table for investors to weigh.
The ongoing U.S. housing affordability crisis and the persistent shortage of conventional single-family and multifamily homes continue to drive high demand for quality, affordable manufactured housing, supporting strong occupancy rates and long-term rent growth, benefitting top-line revenue.
UMH's active expansion into energy-rich, high-growth regions (e.g., Marcellus and Utica Shale) and high-demand markets in the Midwest, Northeast, and Southeast is generating above-industry property appreciation and consistently strong occupancy gains, translating into higher rental income and asset value accretion.
See why 9 investors see UMH Properties as 20% undervalued.
Result: Fair Value of $19.43 (UNDERVALUED)
Still, UMH Properties leans heavily on fresh acquisitions and additional debt funding. Any deal pipeline slowdown or sustained higher interest costs could quickly cool that undervaluation story.
Find out about the key risks to this UMH Properties narrative.
Another View: What UMH’s P/E Is Telling You
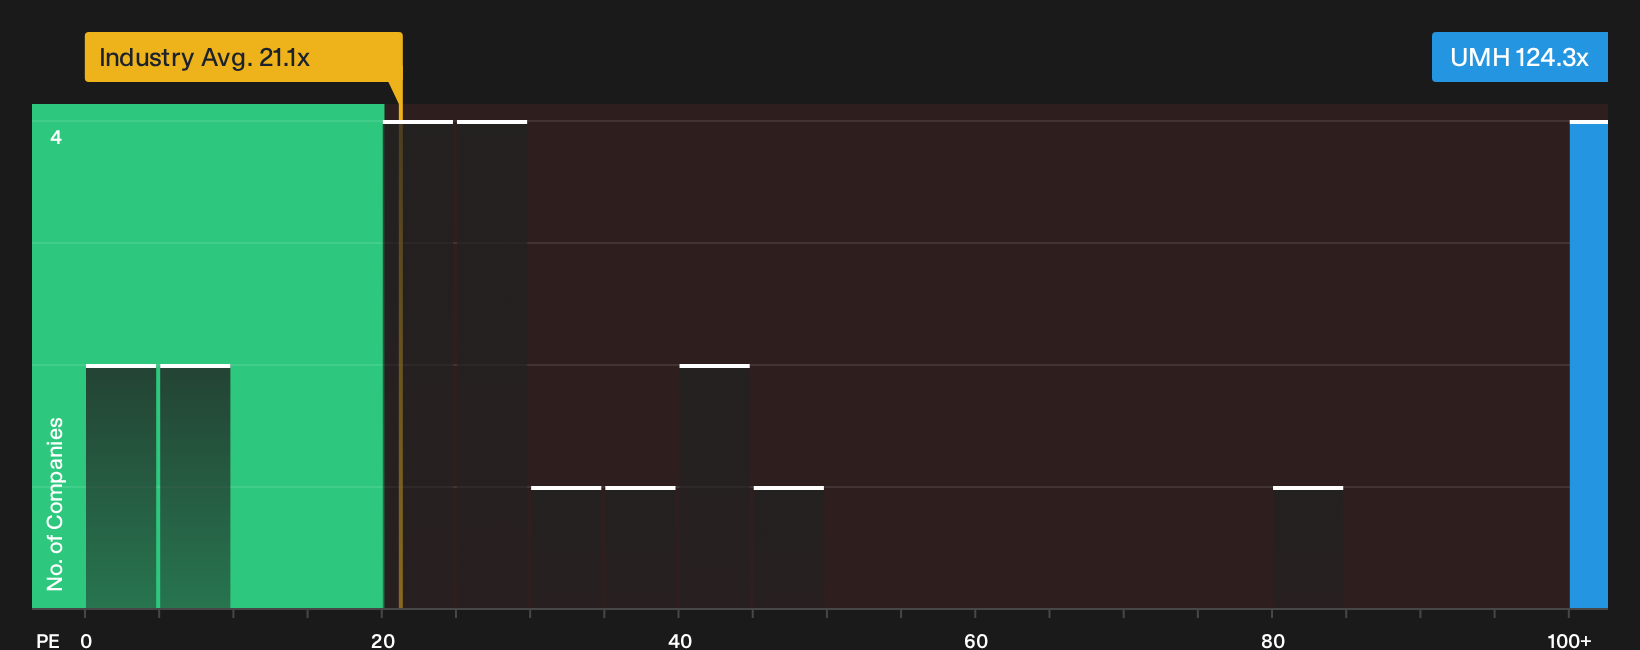
The SWS DCF model points to upside for UMH Properties, yet the simple P/E check tells a very different story. UMH trades on a 124.3x P/E, while the fair ratio is 36.7x and peers cluster nearer 45.2x and 21.1x. That gap signals real valuation risk if sentiment cools.
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on UMH Properties so far. If the valuation gap, debt profile, and housing demand story matter to you, consider acting promptly and weigh both the upside and downside by reviewing the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond UMH Properties?
If UMH Properties has sharpened your focus on value gaps and risk, do not stop here. Broaden your watchlist and pressure test your thesis across other opportunities using targeted stock screens that match your style.
- Chase mispriced opportunities before the crowd notices by reviewing the 33 high quality undervalued stocks.
- Prioritise resilience and sleep-better-at-night holdings by scanning the 11 resilient stocks with low risk scores.
- Anchor your portfolio in financially robust businesses by filtering through the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com