
S.M.A.I.O S.A. (EPA:ALSMA): When Will It Breakeven?
With the business potentially at an important milestone, we thought we'd take a closer look at S.M.A.I.O S.A.'s (EPA:ALSMA) future prospects. S.M.A.I.O S.A. provides software, implantable devices, and associated services for the surgical treatment of spinal deformities. The €38m market-cap company announced a latest loss of €2.2m on 31 December 2025 for its most recent financial year result. As path to profitability is the topic on S.M.A.I.O's investors mind, we've decided to gauge market sentiment. In this article, we will touch on the expectations for the company's growth and when analysts expect it to become profitable.
S.M.A.I.O is bordering on breakeven, according to the 2 French Medical Equipment analysts. They anticipate the company to incur a final loss in 2026, before generating positive profits of €250k in 2027. Therefore, the company is expected to breakeven just over a year from now. In order to meet this breakeven date, we calculated the rate at which the company must grow year-on-year. It turns out an average annual growth rate of 86% is expected, which is extremely buoyant. If this rate turns out to be too aggressive, the company may become profitable much later than analysts predict.
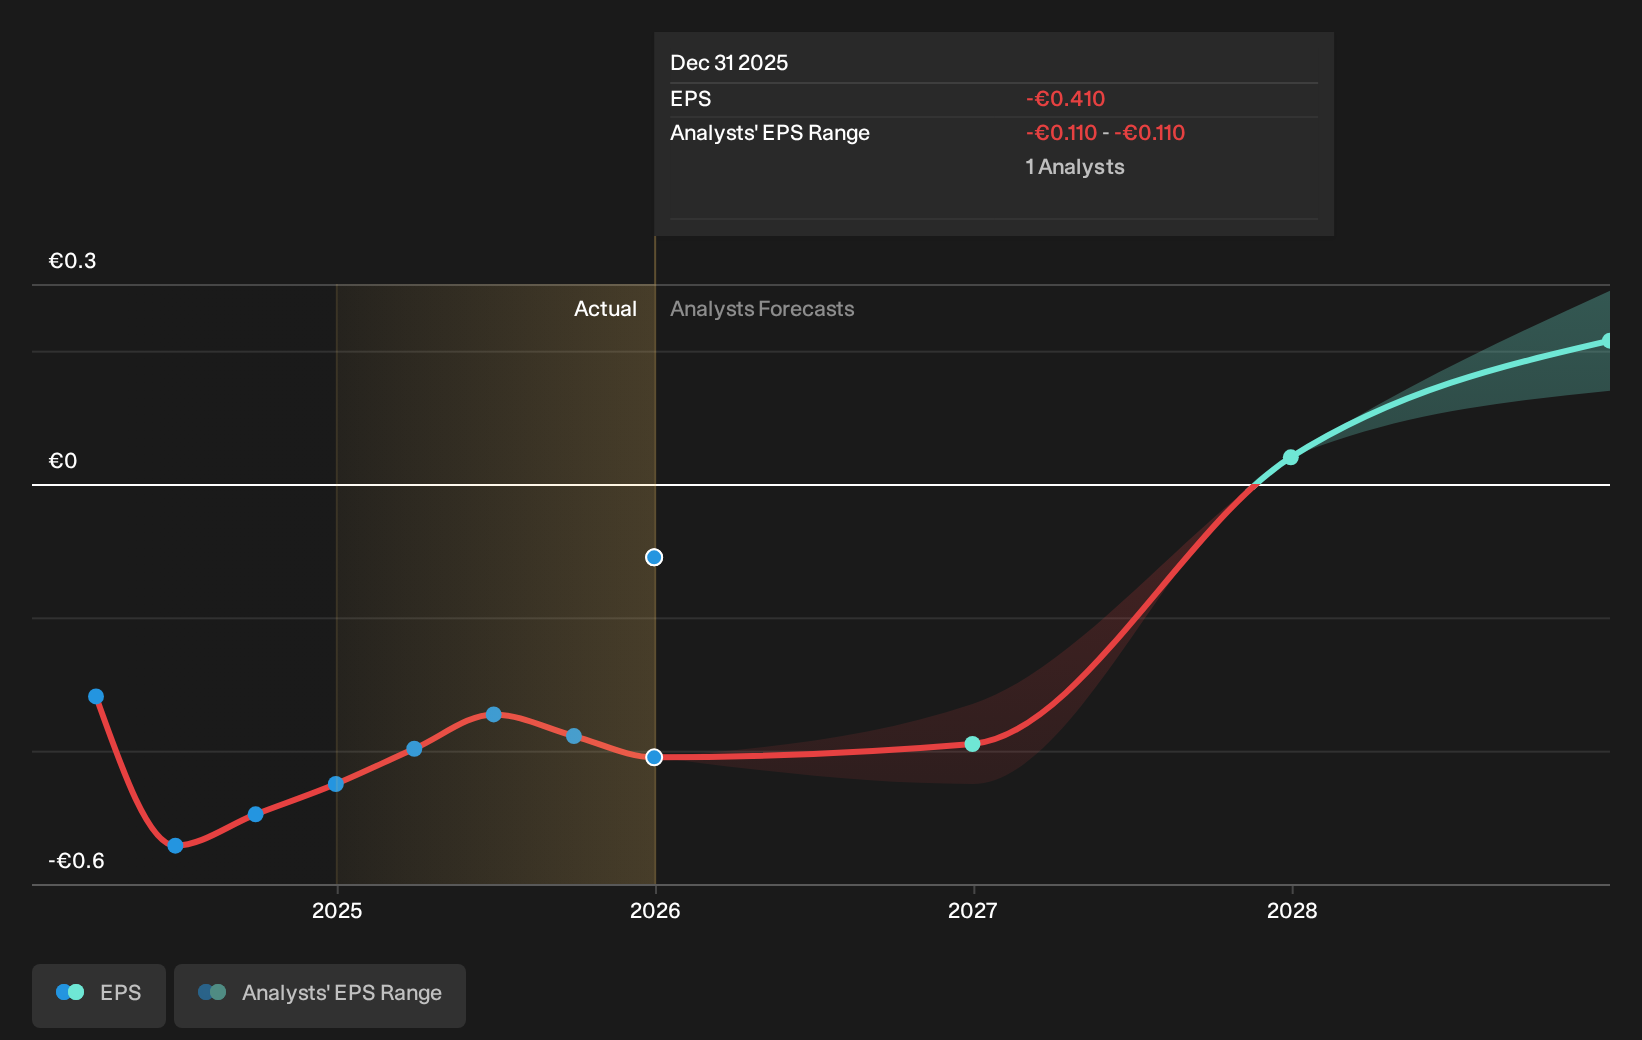
Given this is a high-level overview, we won’t go into details of S.M.A.I.O's upcoming projects, but, keep in mind that generally a high forecast growth rate is not unusual for a company that is currently undergoing an investment period.
See our latest analysis for S.M.A.I.O
One thing we would like to bring into light with S.M.A.I.O is its relatively high level of debt. Typically, debt shouldn’t exceed 40% of your equity, which in S.M.A.I.O's case is 81%. A higher level of debt requires more stringent capital management which increases the risk around investing in the loss-making company.
Next Steps:
This article is not intended to be a comprehensive analysis on S.M.A.I.O, so if you are interested in understanding the company at a deeper level, take a look at S.M.A.I.O's company page on Simply Wall St. We've also compiled a list of important aspects you should further research:
- Historical Track Record: What has S.M.A.I.O's performance been like over the past? Go into more detail in the past track record analysis and take a look at the free visual representations of our analysis for more clarity.
- Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on S.M.A.I.O's board and the CEO’s background.
- Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.