
New G STEEL Watch Might Change The Bull Case For Casio Stock
- Casio Computer Ltd. recently released the G-STEEL GST-W1000 G-SHOCK, a metal-focused model that uses multi-component construction, varied surface finishes, and solar-powered TOUGH MVT. 2 technology for precision timekeeping.
- The GST-W1000 suggests that Casio Computer Ltd. is leaning further into premium, design-focused watches that rely on in-house metalworking and nano-processing capabilities rather than competing on low-cost hardware.
- We will now look at how Casio Computer Ltd.'s investment narrative could be influenced by the premium metal-focused GST-W1000 launch.
Scan beyond Casio ComputerLtd and compare its premium watch pivot with other precision manufacturers by checking a hand picked set of 74 high quality undiscovered gems in related hardware and consumer tech.
Casio ComputerLtd Investment Narrative Recap
To own Casio ComputerLtd, you need to be comfortable with a consumer hardware group that is trying to lean more on premium watches, education tech and new electronics while still carrying legacy categories and uneven regional demand. The short term focus is whether the Timepieces segment can keep earnings momentum and support margins as other lines stay mixed.
The GST-W1000 launch points in the right direction for that watch story, but on its own it is unlikely to move near term financials in a big way. The key risk still sits in pressure on core sales and profitability in markets like China, combined with tariff exposure and intense price competition across consumer devices.
Among recent developments, the GST-W1000 reveals where Casio ComputerLtd is putting product energy. A metal focused, multi component G-STEEL with solar powered TOUGH MVT. 2 and nano processed dials fits the push toward higher value, design led SKUs that can support pricing and potentially protect margins within Timepieces.
For you as a shareholder, the relevant question is execution at scale. If models like the GST-W1000 help Casio shift mix toward premium watches, that can work alongside existing catalysts such as overseas expansion, ambassadors and specialty store growth. The flip side is clear: if demand softens or price pressure accelerates, these higher spec launches may not offset weakness in legacy lines or tariff related cost strain.
Casio Computer Ltd Earnings And Valuation Setup Behind The GST-W1000 Story
Casio Computer Ltd's current GST-W1000 push sits inside a fairly modest growth script. Analysts are working off revenue that is expected to rise by 2.6% a year over the next 3 years. That is not a high octane scenario. It is a slow grind where mix, pricing and discipline around product lines matter more than chasing headline volume at any cost.
The earnings side shows what kind of improvement the business needs to deliver while it leans into more premium metal watches. Forecasts point to profit of ¥25.8b by 2029 compared with earnings today of ¥23.9b. That is an increase of about ¥1.9b in absolute terms. The move is incremental rather than transformative, which fits a product strategy that layers higher value SKUs such as the GST-W1000 on top of a still broad and mature portfolio.
Consensus implies that for this roadmap to hold together, Casio Computer Ltd would be on roughly the same 8.3% profit margin profile over the next few years. Analysts are not factoring in a large lift in profitability from GST-W1000 style launches alone. The expectation is that better mix, tighter marketing and gradual share count reduction of about 2.91% a year do the heavy lifting instead of a sudden jump in operating efficiency.
On the market side, the numbers indicate how much belief is already priced in. The stock trades on a P/E of 20.4x today. To line up with analyst targets, that would need to drift to 16.2x applied to those 2029 earnings of ¥25.8b. That is still above the 9.7x P/E currently quoted for the wider JP Consumer Durables group. The watchmaker is therefore being treated more like a higher quality outlier within its sector rather than a plain-vanilla hardware player.
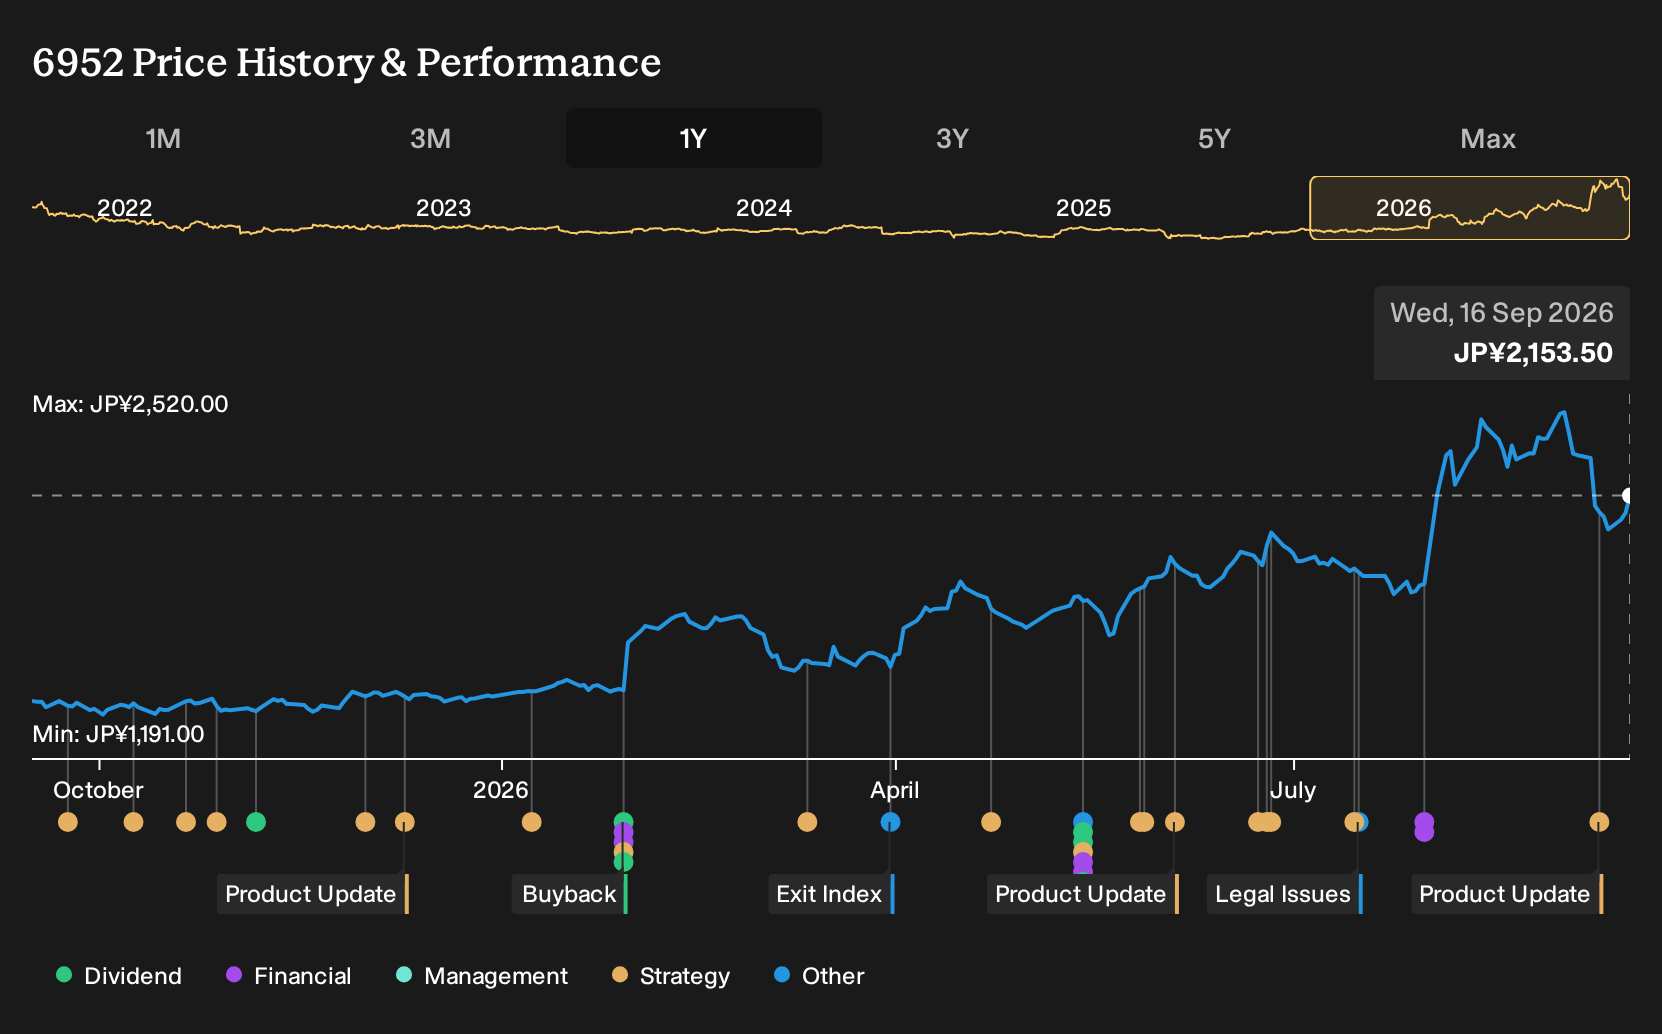
The targets themselves are not aligned. The consensus fair value marker sits at ¥1,718.75 per share, which is 28.1% below the current ¥2,201.5 price. Some analysts sit much higher at ¥2,500. Others are down at ¥1,200. That wide spread reflects the debate over whether the premium watch and EdTech stories can offset recent pressure in areas such as China, tariff exposure and more commoditised electronic devices.
Viewed alongside the GST-W1000 launch, the story is clear. Casio Computer Ltd is being judged on execution over several years, not on one metal focused G-STEEL reference. The watch is a signal of where capital, design effort and marketing spend are heading. The valuation work suggests investors are being asked to decide whether that direction is enough to support earnings that edge up rather than move sharply higher.
Casio Computer Ltd's narrative projects ¥311.6b revenue and ¥25.8b earnings by 2029, which assumes 2.6% yearly revenue growth and an earnings increase of about ¥1.9b from ¥23.9b today.
Uncover why Casio ComputerLtd's fair value indicates a 20% potential downside to its current price, suggesting that this premium may not hold.
Exploring Other Perspectives
For a contrasting view, focus on the bullish catalyst around wearables. The most optimistic Casio Computer Ltd analysts were already pencilling in ¥352.4b of revenue and ¥34.4b of earnings by 2029, assuming stronger demand for multi functional devices. A premium metal launch like the GST-W1000 could prompt those forecasts, and the bearish ones, to shift. Opinions can differ widely, so treat this as a cue to compare several narratives before deciding what the story looks like to you.
Explore another Casio ComputerLtd fair value estimate, including one that suggests as much as 28% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent view.
- A great starting point for your Casio ComputerLtd research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Casio ComputerLtd. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Casio ComputerLtd's overall financial health at a glance.
Looking For More Investment Ideas Beyond Casio Computer Ltd?
If the Casio Computer Ltd story has you thinking about where else pricing power, balance sheet strength or income resilience might show up, the Simply Wall St Screener can help you cast the net wider without getting lost in noise.
- For investors who want quality at a sensible entry point, scan a curated pool of potentially mispriced businesses through 18 high quality undervalued stocks that combine solid fundamentals with room for sentiment to catch up.
- If capital protection matters as much as upside, narrow your search to sturdier balance sheets and steadier profiles with a 12 resilient stocks with low risk scores that keeps the focus on resilience over hype.
- When the goal is to spot tomorrow's potential compounders before they are widely followed, use a targeted 74 high quality undiscovered gems to surface under-the-radar stocks with stronger financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com