
3 European Growth Stocks Insiders Own With Up To 56% ROE
As European markets face pressure from rising inflation and geopolitical tensions, the pan-European STOXX Europe 600 Index recently ended the week down by 1.66%. In this challenging environment, growth companies with high insider ownership can offer a compelling investment profile due to their potential for robust returns on equity and alignment of interests between management and shareholders.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.6% |
| MilDef Group (OM:MILDEF) | 10.3% | 31.1% |
| Kuros Biosciences (SWX:KURN) | 25.9% | 58.6% |
| KebNi (OM:KEBNI B) | 12% | 103.8% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 20.5% | 60.7% |
| CD Projekt Red (WSE:CDR) | 35.2% | 47.9% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.2% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
Let's explore several standout options from the results in the screener.
Clas Ohlson (OM:CLAS B)
Simply Wall St Growth Rating: ★★★★☆☆
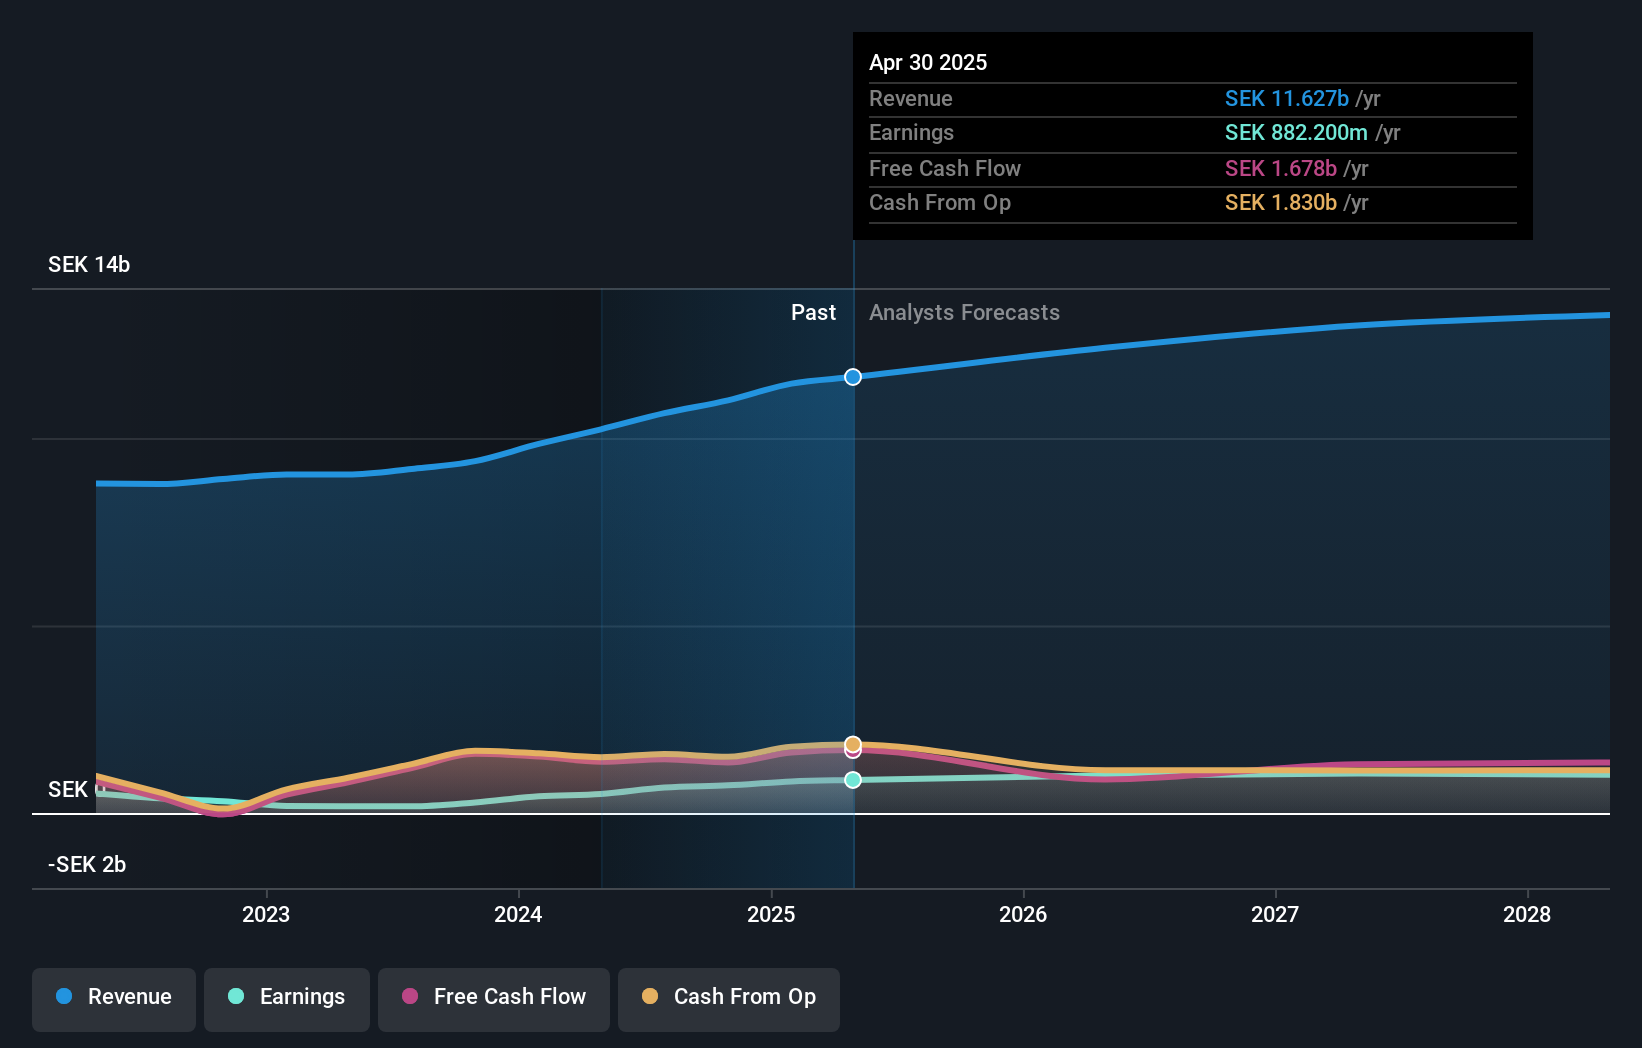
Overview: Clas Ohlson AB (publ) is a retail company that offers building, electrical, multimedia, home, and leisure products in Sweden, Norway, Finland, and internationally with a market cap of SEK27.03 billion.
Operations: The company generates revenue of SEK12.98 billion from its specialty retail segment, which includes building, electrical, multimedia, home, and leisure products across Sweden, Norway, Finland, and international markets.
Insider Ownership: 33.6%
Return On Equity Forecast: 36% (2029 estimate)
Clas Ohlson demonstrates strong growth potential, with earnings increasing by 33.8% over the past year and forecasted to grow at 9.1% annually, outpacing the Swedish market. Insider ownership remains stable with no substantial selling in recent months. Despite an unstable dividend history, a special dividend was announced recently alongside increased ordinary dividends, reflecting confidence in financial health. The company's sales have shown consistent organic growth, supported by strategic acquisitions and currency effects.
- Navigate through the intricacies of Clas Ohlson with our comprehensive analyst estimates report here.
- The valuation report we've compiled suggests that Clas Ohlson's current price could be inflated.
Nordrest Holding (OM:NREST)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Nordrest Holding AB (publ) is a foodservice company operating in Sweden and internationally, with a market cap of SEK3.35 billion.
Operations: Nordrest Holding AB (publ) generates its revenue through its operations in the foodservice industry, both within Sweden and on an international scale.
Insider Ownership: 23.8%
Return On Equity Forecast: 57% (2029 estimate)
Nordrest Holding shows promising growth potential with earnings increasing by 34% over the past year and forecasted to grow at 16.91% annually, surpassing the Swedish market's growth rate of 7.4%. Despite a slower revenue growth forecast of 9% per year, it still exceeds the market average. The company's return on equity is expected to be very high at 56.8% in three years, and it trades significantly below its estimated fair value without substantial recent insider trading activity.
- Click to explore a detailed breakdown of our findings in Nordrest Holding's earnings growth report.
- Our valuation report here indicates Nordrest Holding may be undervalued.

Oponeo.pl (WSE:OPN)
Simply Wall St Growth Rating: ★★★★☆☆
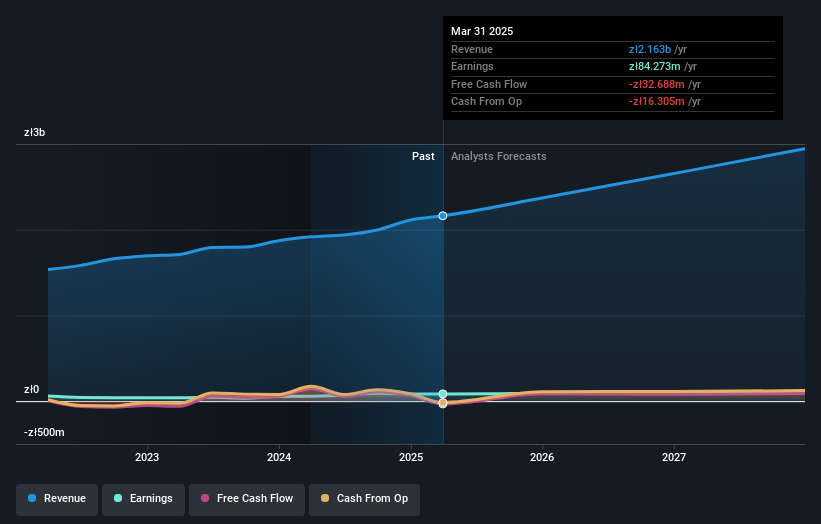
Overview: Oponeo.pl S.A. operates as an online retailer specializing in tyres and wheels for motor vehicles in Poland, with a market capitalization of PLN1.15 billion.
Operations: The company's revenue is primarily derived from the sale of tires, rims, and accessories at PLN1.99 billion, followed by bicycles and bicycle accessories at PLN608.83 million, and tools including power tools at PLN72.33 million.
Insider Ownership: 21.4%
Return On Equity Forecast: 28% (2029 estimate)
Oponeo.pl has demonstrated robust sales growth, with recent half-year sales reaching PLN 1.25 billion, up from PLN 976.53 million year-on-year. Despite a decrease in profit margins to 2.4%, earnings per share improved to PLN 3.07 from PLN 2.13, indicating solid profitability growth relative to the Polish market's average of 11.1%. However, its dividend yield of 3.42% is not well supported by free cash flow, and debt coverage remains a concern despite strong insider ownership stability.
- Delve into the full analysis future growth report here for a deeper understanding of Oponeo.pl.
- Our valuation report unveils the possibility Oponeo.pl's shares may be trading at a premium.
Taking Advantage
- Dive into all 215 of the Fast Growing European Companies With High Insider Ownership we have identified here.
- Searching for a Fresh Perspective? Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com