
PagerDuty (PD) Posts Another Profitable Quarter, Is The Valuation Running Ahead?
PagerDuty (PD) is back in focus after reporting its fifth straight quarter of GAAP profitability, trimming overlapping expenses while lifting revenue and shifting more of its AI platform to consumption-based pricing.
Recent trading tells a mixed story. PagerDuty’s share price has climbed strongly in the near term, with a 23.76% 1 month share price return and a 70.75% 3 month share price return. However, longer term total shareholder returns over 1, 3 and 5 years remain negative, suggesting current momentum is rebuilding confidence after a weaker multi year experience.
Ride PagerDuty's renewed AI and profitability story by scouting similar opportunities in our hand picked list of 75 profitable AI stocks that aren't just burning cash.Bulls point to PagerDuty’s profitability streak and AI push. Bears highlight weak multi year returns and modest revenue growth. Which story does the current valuation lean toward as momentum snaps back so quickly?
Most Popular Narrative: 15% Overvalued
PagerDuty last closed at $14.48, while the most followed narrative pegs fair value at $12.64 using a 9.52% discount rate. This sets up a tension between recent price strength and more cautious long term assumptions.
The transition from seat-based to usage-based pricing models, validated by rapid growth in usage-based product lines (60%+ year-over-year) and strong initial customer feedback, aligns future topline growth more closely with actual customer value realization. This is expected to set the stage to reaccelerate ARR growth and improve net retention as automation reduces per-seat dependency.
See why 18 investors see PagerDuty as 15% overvalued.
Result: Fair Value of $12.64 (OVERVALUED)
Still, the PagerDuty narrative can break if usage based pricing introduces choppy revenue, or if heavier competition pressures margins and slows progress on earnings.
Find out about the key risks to this PagerDuty narrative.
Another View On PagerDuty’s Valuation
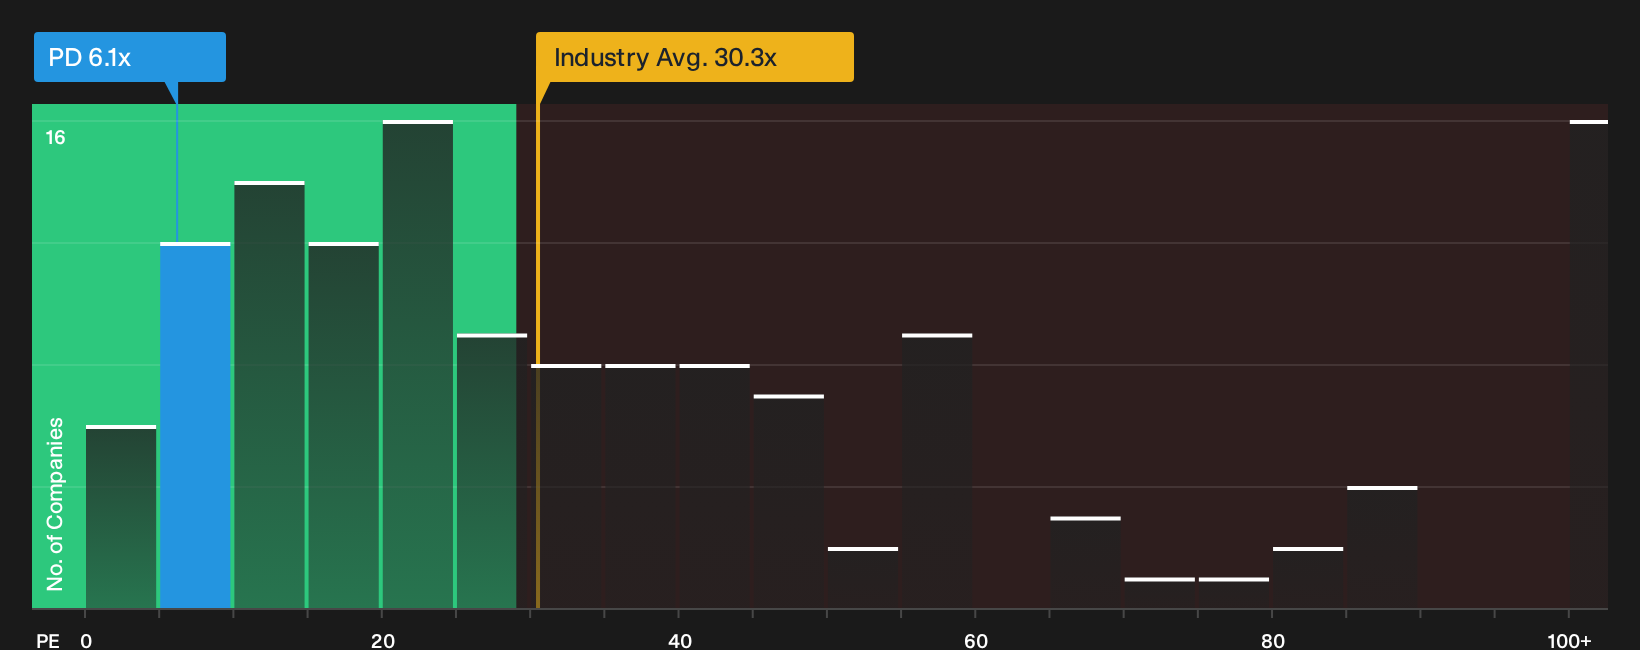
Analysts see PagerDuty as 15% overvalued on their $12.64 fair value, yet current pricing at $14.48 sits 37.6% below the Simply Wall St fair value estimate based on earnings multiples. The stock trades on a P/E of 6.1x versus 30.5x for US software peers and a fair ratio of 6.3x. Is the crowd underpricing the story or are the earnings inputs simply too flattering?
For a closer look at how this P/E gap could resolve over time, including what it might mean for upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on PagerDuty can be confusing, especially with both worries and bright spots in play. Take a moment to weigh the full picture and stress test your own thesis against the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond PagerDuty?
Do not stop with PagerDuty. Use fresh watchlist ideas from carefully filtered screeners so you are not relying on a single turnaround story or sector.
- Target quality at a discount by scanning our 33 high quality undervalued stocks that pair stronger fundamentals with pricing that has not fully caught up yet.
- Protect the downside first by focusing on a 11 resilient stocks with low risk scores that emphasizes resilient balance sheets and steadier business profiles.
- Get ahead of the crowd by reviewing a 16 high quality undiscovered gems that highlights companies with solid numbers but limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com