
Learn Why The Bull Case For STAAR Surgical Stock Could Change Following Earnings Rebound
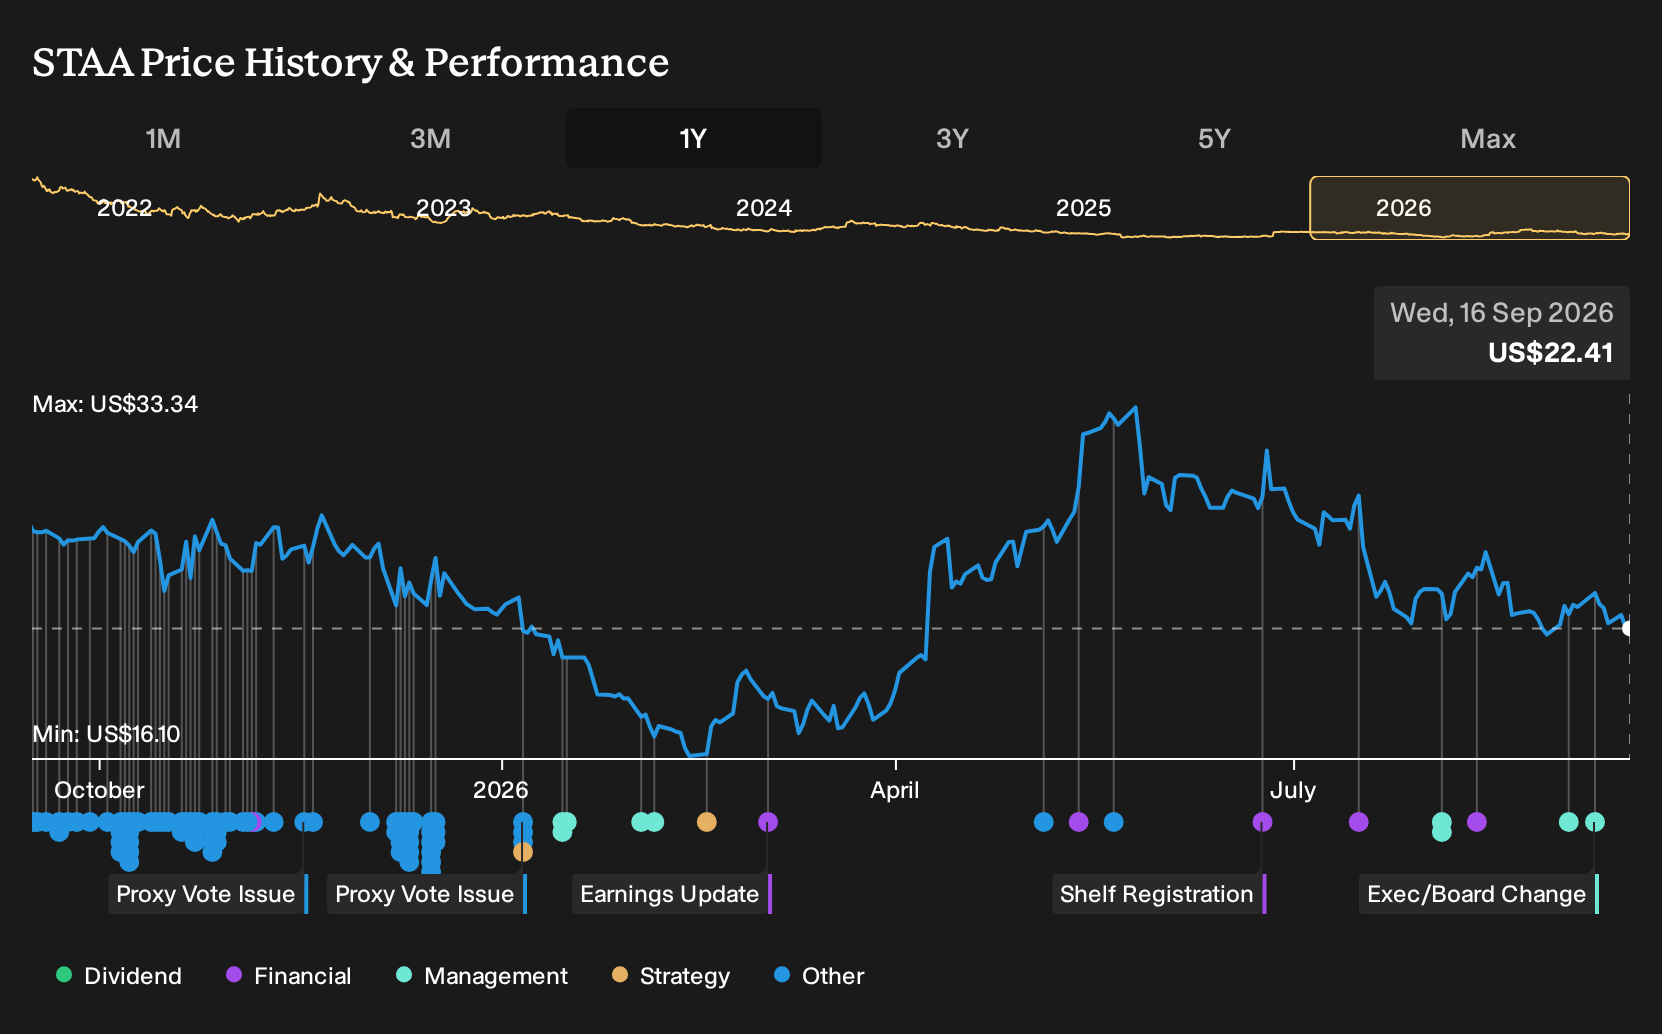
- STAAR Surgical reported quarterly net sales of US$93.5 million, with 111% year over year growth and a shift to net income, while appointing former CEO David Bailey as Chief Commercial Officer alongside Ben Park, Ph.D., as Chief Technology Officer.
- The return of Bailey, who previously drove the phakic IOL focus, FDA ICL approval and international expansion, signals an emphasis on commercial execution, building on China led revenue strength.
- We will look at how STAAR Surgical's investment narrative is reshaped by this earnings rebound and David Bailey's commercial return.
STAAR Surgical Investment Narrative Recap
To own STAAR Surgical, you need to believe that demand for phakic ICL procedures can support a sustained, profitable business even with China related volatility. The sharp earnings rebound and return to profit show what happens when volume and pricing line up. The most important short term driver is whether this higher level of activity proves repeatable rather than specific to a single quarter.
The biggest risk still sits in China concentration and the single distributor model, where any slowdown, pricing pressure, or inventory misalignment can hit visibility quickly. David Bailey’s appointment should help commercial execution, but it does not on its own remove macro, competitive, or refractive procedure growth risks.
The appointment of David Bailey as Chief Commercial Officer is the announcement that ties most tightly to these catalysts. His previous period at STAAR Surgical covered the ICL focus, FDA approval, and early Asia launches. As a result, he knows the playbook around surgeon adoption, pricing, and distributor management across multiple regions.
From an investor lens, that hire mainly affects execution risk rather than creating a new product cycle. It matters if you think near term value comes from converting current EVO and EVO+ opportunities, cleaning up China distributor inventories, and sharpening the go to market approach in the United States and Europe. If those are your key swing factors, this leadership change is highly relevant.
STAAR Surgical's narrative projects US$400.0 million revenue and US$36.5 million earnings by 2029. This assumes 11.3% yearly revenue growth and an earnings swing of roughly US$57.5 million, from a loss of US$21.0 million today to the forecast consensus earnings level.
Uncover why STAAR Surgical's fair value indicates a 32% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One optimistic twist in the alternate STAAR Surgical story is capacity expansion. The most bullish analysts were already modeling revenue of about US$450.7 million and earnings near US$53.1 million by 2029, based largely on new manufacturing output and Asia demand. Those forecasts predate David Bailey’s return, so your own view may shift as you factor this news in.
Explore 2 other STAAR Surgical fair value estimates, including one that suggests there may be as much as 33% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your STAAR Surgical research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for STAAR Surgical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate STAAR Surgical's overall financial health at a glance.
Looking For More Investment Ideas Beyond STAAR Surgical?
Once you understand STAAR Surgical's story, it can help to compare it with other opportunities that suit different risk profiles and income goals. The Simply Wall St Screener lets you quickly filter for businesses that match your own checklist rather than relying on headlines.
- If capital preservation sits high on your priority list, run a search for companies screened as having resilient balance sheets and lower risk profiles through the 11 resilient stocks with low risk scores.
- For investors who care most about financial strength and staying power, scan a curated list of solid balance sheet and fundamentals (22 results) that can anchor a long term watchlist.
- If you are hunting for fresh opportunities off the usual radar, widen your net with a 16 high quality undiscovered gems that focuses on quality fundamentals and underfollowed stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com