
West Fraser Timber (TSX:WFG) Shares Just Moved, So What Is Behind The Attention?
West Fraser Timber (TSX:WFG) just reshaped its funding mix by securing a new US$500 million three-year term loan to refinance existing debt, while also affirming a US$0.32 quarterly dividend for shareholders.
That refinancing news comes after a strong run in the share price, with West Fraser Timber posting a 7.4% 30-day share price return and an 18.1% share price return year to date. However, the 1-year total shareholder return of 3.6% shows more muted longer-term progress, suggesting momentum has picked up recently as investors reassess both growth prospects and balance sheet risk following these funding and dividend decisions.
Scan for other balance-sheet focused opportunities with refinancing room and liquidity in mind by checking the hand picked 1 resilient stocks with low risk scores alongside West Fraser Timber.
Bulls see West Fraser Timber using fresh liquidity and an ongoing dividend to support value, while bears point to recent losses on the income line. Which story do the current valuation marks lean toward?
Most Popular Narrative: 4% Undervalued
Against a last close of CA$101.90, the most followed narrative pegs West Fraser Timber’s fair value a little higher at CA$106.61. This frames the recent refinancing and dividend moves against a modest valuation cushion built on future cash flow expectations and housing demand recovery assumptions.
The accelerating global shift toward sustainable building practices and materials is expected to drive long-term demand for renewable wood products, favoring West Fraser Timber due to its focus on sustainability, which should support multi-year revenue growth as green mandates and consumer preferences grow.
Ongoing urbanization and demographic expansion, particularly in North America and Asia, are likely to support structural demand for housing, renovation, and infrastructure projects, underpinning steady volume growth and providing a catalyst for future revenue and EBITDA expansion once macro headwinds such as elevated rates subside.
See why 16 investors see West Fraser Timber as 4% undervalued.
Result: Fair Value of CA$106.61 (UNDERVALUED)
Still, this narrative can break if weak U.S. housing demand persists or if new U.S. tariffs and trade actions raise costs and squeeze profitability.
Find out about the key risks to this West Fraser Timber narrative.
Another View on West Fraser Timber Valuation
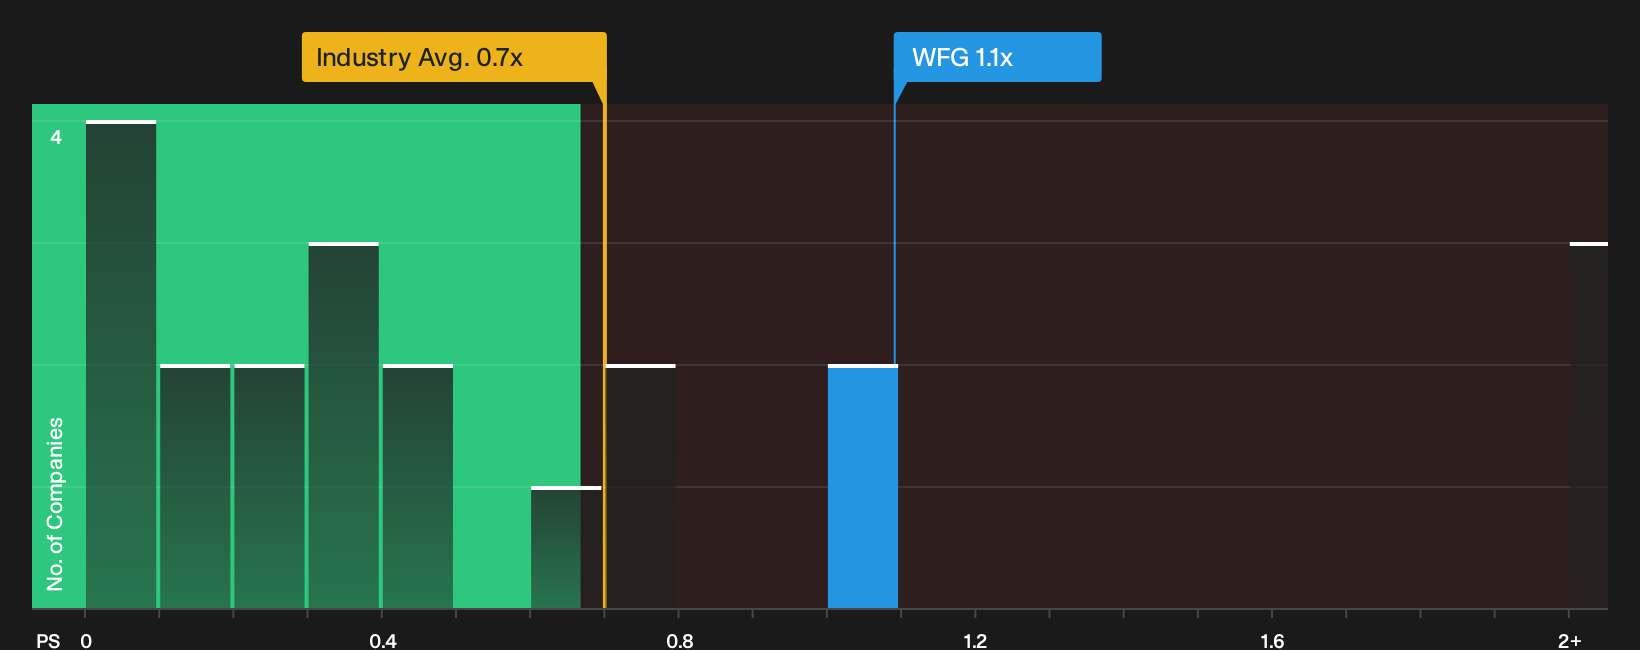
The earlier narrative framed West Fraser Timber as modestly undervalued based on analyst targets around CA$106.61. A different lens using the P/S ratio paints a more cautious picture. The stock trades at 1.1x sales compared with 0.7x for the global forestry group and a 1.3x fair ratio. Anyone paying today is accepting a richer tag than the sector while still sitting below where the fair ratio suggests the market could drift. This raises the question of whether that gap signals room for re-rating or simply additional valuation risk if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around West Fraser Timber can be useful if you turn them into your own thesis instead of following the crowd. Act quickly, pull up the key data points, and weigh both the upside and the red flags by checking the 2 key rewards and 1 important warning sign.
Looking for more West Fraser Timber sized ideas?
If West Fraser Timber has sharpened your focus on valuation and balance sheet strength, do not stop here. Broaden your watchlist now using focused ideas from the Simply Wall Street Screener so you are not relying on one stock to carry your whole plan.
- Target resilience first and scan companies with sturdy finances by reviewing the list of solid balance sheet and fundamentals (6 results).
- Hunt for pricing gaps and see which businesses our models flag as potential value opportunities in the 4 high quality undervalued stocks.
- Spot under-the-radar opportunities early by tracking the 9 high quality undiscovered gems before they gain wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com