
How New Rehab Hospital Will Impact Encompass Health (EHC) Investors
- Encompass Health has opened the 50 bed Encompass Health Rehabilitation Hospital of Lower Providence in Montgomery County, Pennsylvania, a 54,000 square foot inpatient facility that delivers intensive therapy, frequent physician oversight and 24 hour nursing care for complex rehab cases.
- The new Lower Providence hospital adds a dedicated, high acuity site with advanced rehab technologies and in house services, reinforcing Encompass Health’s focus on serving demand for medically complex stroke, brain injury and orthopedic recovery in an underserved region.
- Next, the focus shifts to how Encompass Health’s new 50 bed Lower Providence facility could influence the longer term investment narrative.
Encompass Health Investment Narrative Recap
To own Encompass Health, you need to believe that inpatient rehab stays relevant even as care shifts toward outpatient and at home options, and that the operator can keep filling higher acuity beds without giving up pricing power. The Lower Providence opening fits that belief by adding capacity in a region that has been described as underserved, but on its own it is not a major short term catalyst.
The bigger near term swing factor is still execution on the broader build out pipeline while managing wages and staffing. Each new hospital like Lower Providence brings extra labor needs, start up costs and utilization risk. If recruitment lags or reimbursement rules tighten, those pressures could weigh on margins before new beds fully contribute.
The Lower Providence hospital is the clearest recent operational milestone. It directly ties to the catalyst of expanding inpatient rehabilitation capacity for complex stroke, brain injury and orthopedic cases. For investors focused on how Encompass Health converts demographic demand into revenue, this is one of the clearer examples of the playbook in action.
The same update also highlights the flip side. A 50 bed, 54,000 square foot facility with advanced technology, in house services and amenities represents a meaningful commitment of capital and staffing. For investors monitoring cash generation, debt levels and labor tightness, the key question is how efficiently Encompass Health ramps these new sites while limiting cost creep and underutilization.
Encompass Health's current analyst narrative points to revenues of US$7.9b and earnings of US$806.1m by 2029, built on an assumed 8.4% yearly revenue growth rate and an earnings increase of about US$202.4m from earnings today of US$603.7m.
Discover how Encompass Health's fair value indicates a 20% potential upside to its current price that may not last much longer.
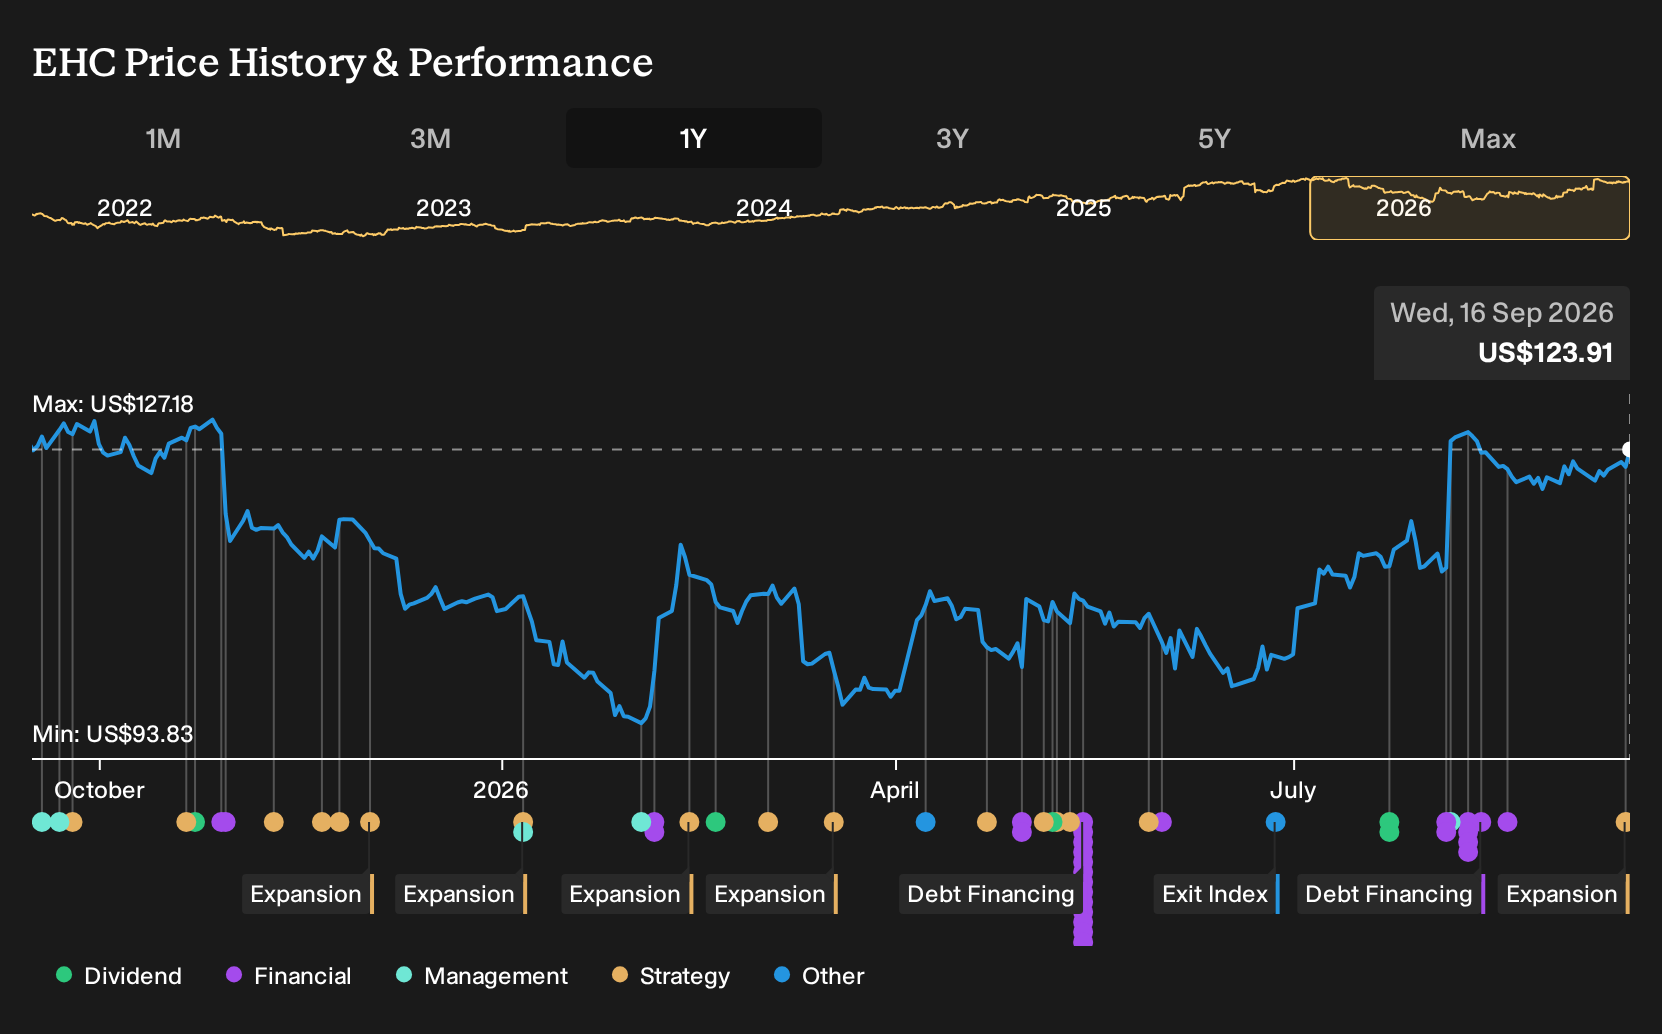
Exploring Other Perspectives
The Simply Wall St Community currently offers 4 fair value estimates for Encompass Health, spanning roughly US$99 to US$148 per share, so opinions already stretch from cautious to optimistic. When you set that against risks around labor shortages, heavy build out spending and Medicare dependence, you get a wide field of possible outcomes. Use these contrasts to test your own thesis and explore how differently other private investors view the same stock.
Explore 3 other Encompass Health fair value estimates, including one that suggests there may be as much as 20% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Encompass Health research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Encompass Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Encompass Health's overall financial health at a glance.
Looking For More Ideas Beyond Encompass Health?
If the Encompass Health story has sharpened your thinking, use that momentum to scan a wider field of potential opportunities. A focused screener helps you filter by the traits you care about most, instead of scrolling through endless tickers hoping something catches your eye.
- If you care most about financial resilience and balance sheet strength, start with a curated list of solid balance sheet and fundamentals (22 results) that can handle tougher conditions without relying heavily on optimism.
- For readers hunting for quality at a reasonable entry point, review a hand picked group of 33 high quality undervalued stocks that combine robust fundamentals with price tags that may be out of sync with their underlying metrics.
- Income focused investors who want payouts that look more durable than average can work through a targeted set of 6 dividend fortresses offering yields from companies with stronger than usual financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com