
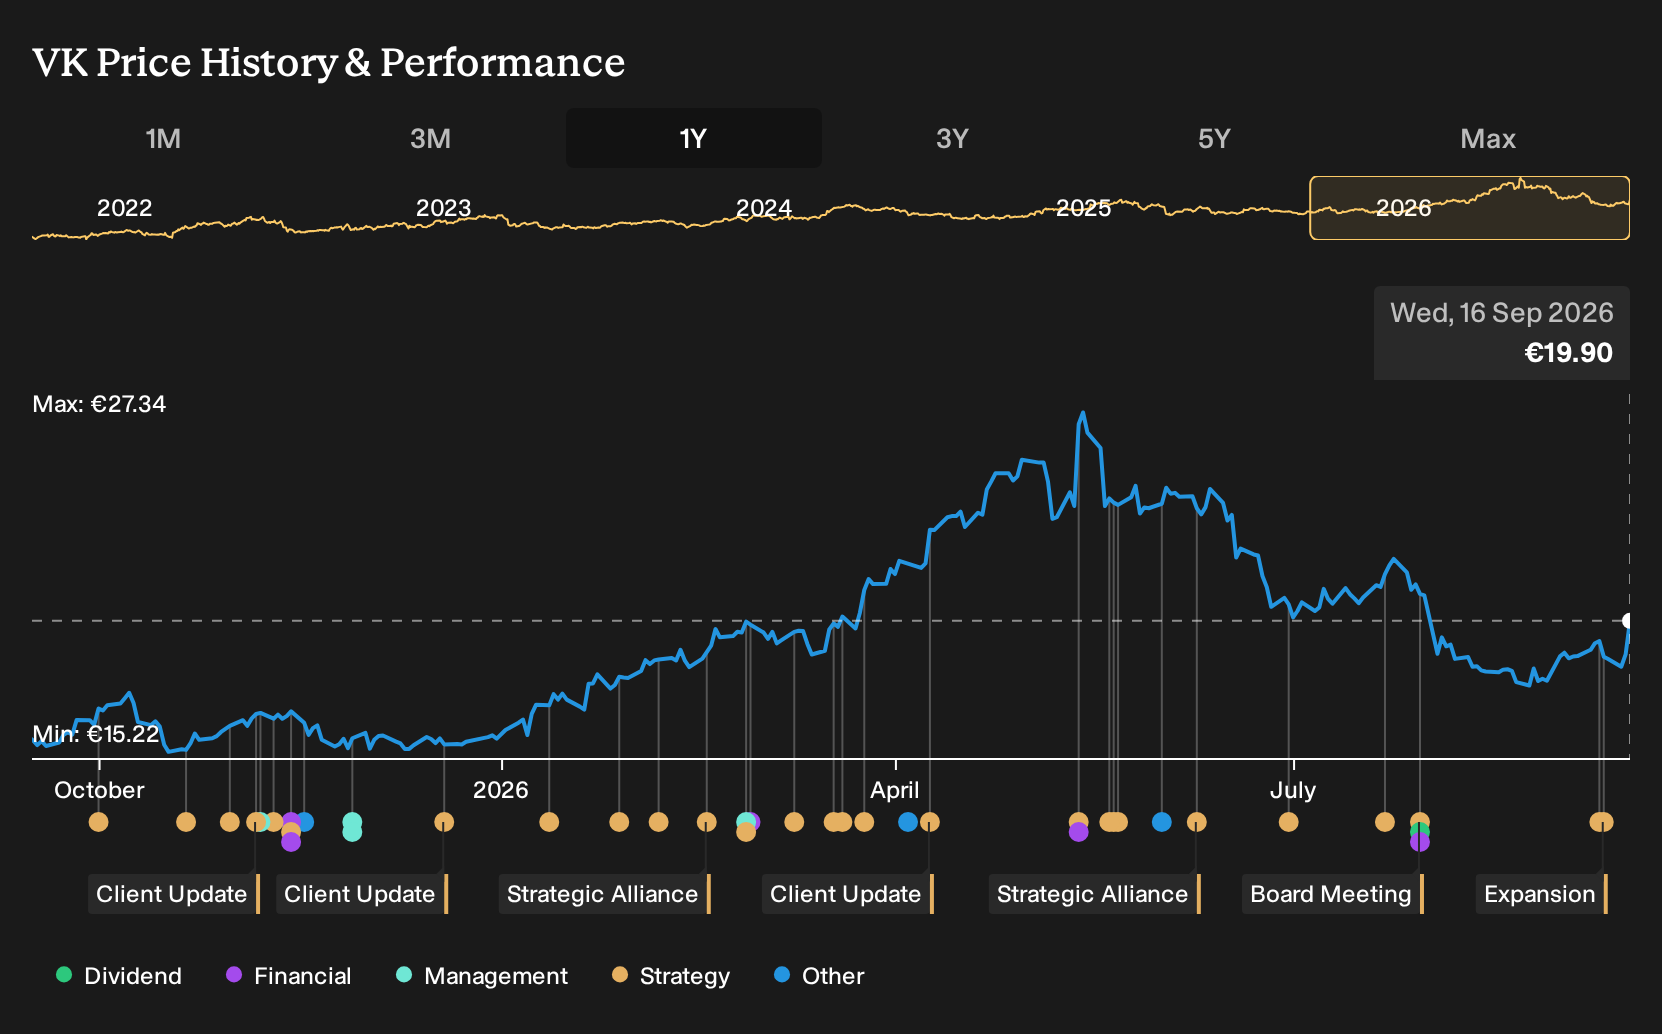
Why Vallourec Stock Is Up 6.4% And What's Next After Sepia 2 Contract Win
- Vallourec recently announced a major contract from Subsea7 to supply around 130 kilometers of sour service carbon steel line pipe and thermal insulation coating for Petrobras’ Sepia 2 ultra deepwater project in Brazil, with manufacturing and coating concentrated at its Jeceaba and Serra facilities.
- The award gives Vallourec the entire carbon steel line pipe and external coating scope through a single integrated offer. This underscores how its Brazilian industrial base and insulation technology are being used as a full-service hub for complex offshore developments.
- We will now look at how Vallourec’s investment narrative is influenced by securing full-scope line pipe supply on Petrobras’ Sepia 2 project.
Scan beyond Vallourec’s Petrobras win and line up other offshore infrastructure plays by reviewing the curated 91 nuclear energy infrastructure stocks, which could benefit from similar long-horizon energy investment cycles.
Vallourec Investment Narrative Recap
To own Vallourec, you need to be comfortable with a business tied closely to long cycle oil and gas spending, while also leaning into higher value tubular and insulation solutions. The Sepia 2 win reinforces that story by putting its Brazilian mills and coating assets to work on complex deepwater projects, which speaks directly to execution on premium work.
In the short term, the key swing factor is still how efficiently Vallourec runs its high fixed cost plants and keeps margins resilient through any order volatility. The biggest risk remains heavy exposure to hydrocarbons and potential pricing pressure if capacity exceeds demand. The new contract looks helpful but not thesis changing by itself.
The recent groundbreaking at Serra for the Proxxima and Goldilocks (GDLX) insulation line is closely linked to the Petrobras news. Sepia 2 relies on Vallourec’s deepwater insulation know how, and Serra is the physical site where this capability is being scaled for future projects in Brazil and abroad.
For you as a shareholder, that expansion links directly to the main catalyst analysts focus on. Higher margin premium products, especially subsea solutions, support the idea of better structural profitability from 2026 onward. Execution risk is clear, however. Serra needs to ramp on time and at planned cost, or the benefit to cash generation and returns could be delayed.
Vallourec's analyst story hinges on revenue reaching $5.7b and earnings of $713.1m by 2029, supported by an expected 10.7% yearly increase in revenue and a move from $403.5m in earnings today to that $713.1m level, which implies an earnings uplift of about 1.8x.
Uncover why Vallourec's fair value indicates a 29% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on Vallourec leans hard into the geothermal and low carbon story. The most optimistic analysts were already penciling in $6.3b of revenue and $856.3m of earnings by 2029, far above consensus. You can read that as a bet that contracts like Sepia 2 might gradually reshape the narrative from oil risk toward premium energy infrastructure.
Explore 3 other Vallourec fair value estimates, including one that suggests potential upside of up to 123% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Trust your own research and judgment.
- A great starting point for your Vallourec research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Vallourec. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vallourec's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vallourec?
If the Vallourec story has you thinking about position sizing and sector exposure, it can help to set it alongside a wider watchlist built around clear filters.
- For investors who want income to play a bigger role, consider screening for companies described as 161 dividend fortresses that might support a more yield focused portfolio.
- If capital preservation and a steadier ride matter most to you, look at businesses flagged as 104 resilient stocks with low risk scores to see which ones align with your comfort level.
- For readers hunting for underfollowed opportunities with stronger fundamentals, review the 619 high quality undiscovered gems that could complement a position in Vallourec.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com