
Is Regional Awards Recognition Altering The Investment Case For Adeia Stock (ADEA)?
- Adeia Inc. recently received Asia Pacific Outstanding Company of the Year 2025–2026, while vice president of licensing Steve Kim was honored as Outstanding Executive of the Year, recognizing business performance and leadership in the region.
- The dual awards highlight how Adeia’s licensing operations and executive bench are viewed in the Asia-Pacific market, an important geography for expanding its intellectual property royalty base and deepening customer relationships.
- We will now explore how Adeia’s Asia Pacific Outstanding Company recognition might influence the existing investment narrative around its licensing model.
Scan how Adeia’s Asia-focused licensing story compares with other intellectual property plays by checking our handpicked 16 high quality undiscovered gems with strong fundamentals that are still flying under most investors’ radar.
Adeia Investment Narrative Recap
Adeia investors need to be comfortable owning a pure licensing platform that lives or dies on the relevance of its patent portfolio and the durability of its contracts. The short term swing factor is still execution on large renewals and new deals in media and semiconductors, while the biggest near term risk sits in customer concentration and evolving IP rules.
The Asia Pacific Outstanding Company award is flattering but does not materially alter those drivers on its own. It mainly supports the idea that Adeia is gaining operational traction in a region that already contributes meaningful royalty revenue, which could modestly help the pipeline story rather than rewrite it.
With no new formal filings tied directly to this recognition, the most relevant context comes from Adeia's earlier focus on expanding semiconductor and OTT licensing. Those efforts depend on signing multi year agreements and keeping its IP portfolio aligned with real world deployment in data centers, consumer devices and streaming.
The Asia Pacific awards intersect with those catalysts by highlighting execution in a geography that hosts many semiconductor customers and device makers. For a shareholder, the practical question is whether stronger regional relationships help offset risks such as slower forecast revenue growth, rising legal spend and a maturing patent base over the next few years.
What The Current Analyst Forecasts Assume For Adeia
Adeia investors are being asked to underwrite a set of expectations that point to relatively steady top line performance but softer profitability over time. Analysts in the current consensus have revenue staying broadly flat, while margins are modeled to slip from 26.1% today to 23.2% over the next three years.
The projections anchor on earnings moving from $122.7 million today to $108.1 million by 2029, which implies an earnings decline of $14.6 million over that period. Those profits, paired with an expected 0.7% annual increase in the share count, feed into a 2029 earnings per share figure of $0.98 that analysts are using as the base for their price targets.
On this framework, the consensus view is that Adeia could be earning $108.1 million on $465.3 million of revenue in 2029. For that to support an analyst target price of $43.00 per share, the stock would need to trade on a P/E of 57.9x those future earnings, compared with 22.5x today and a current US Software sector P/E of 30.7x.
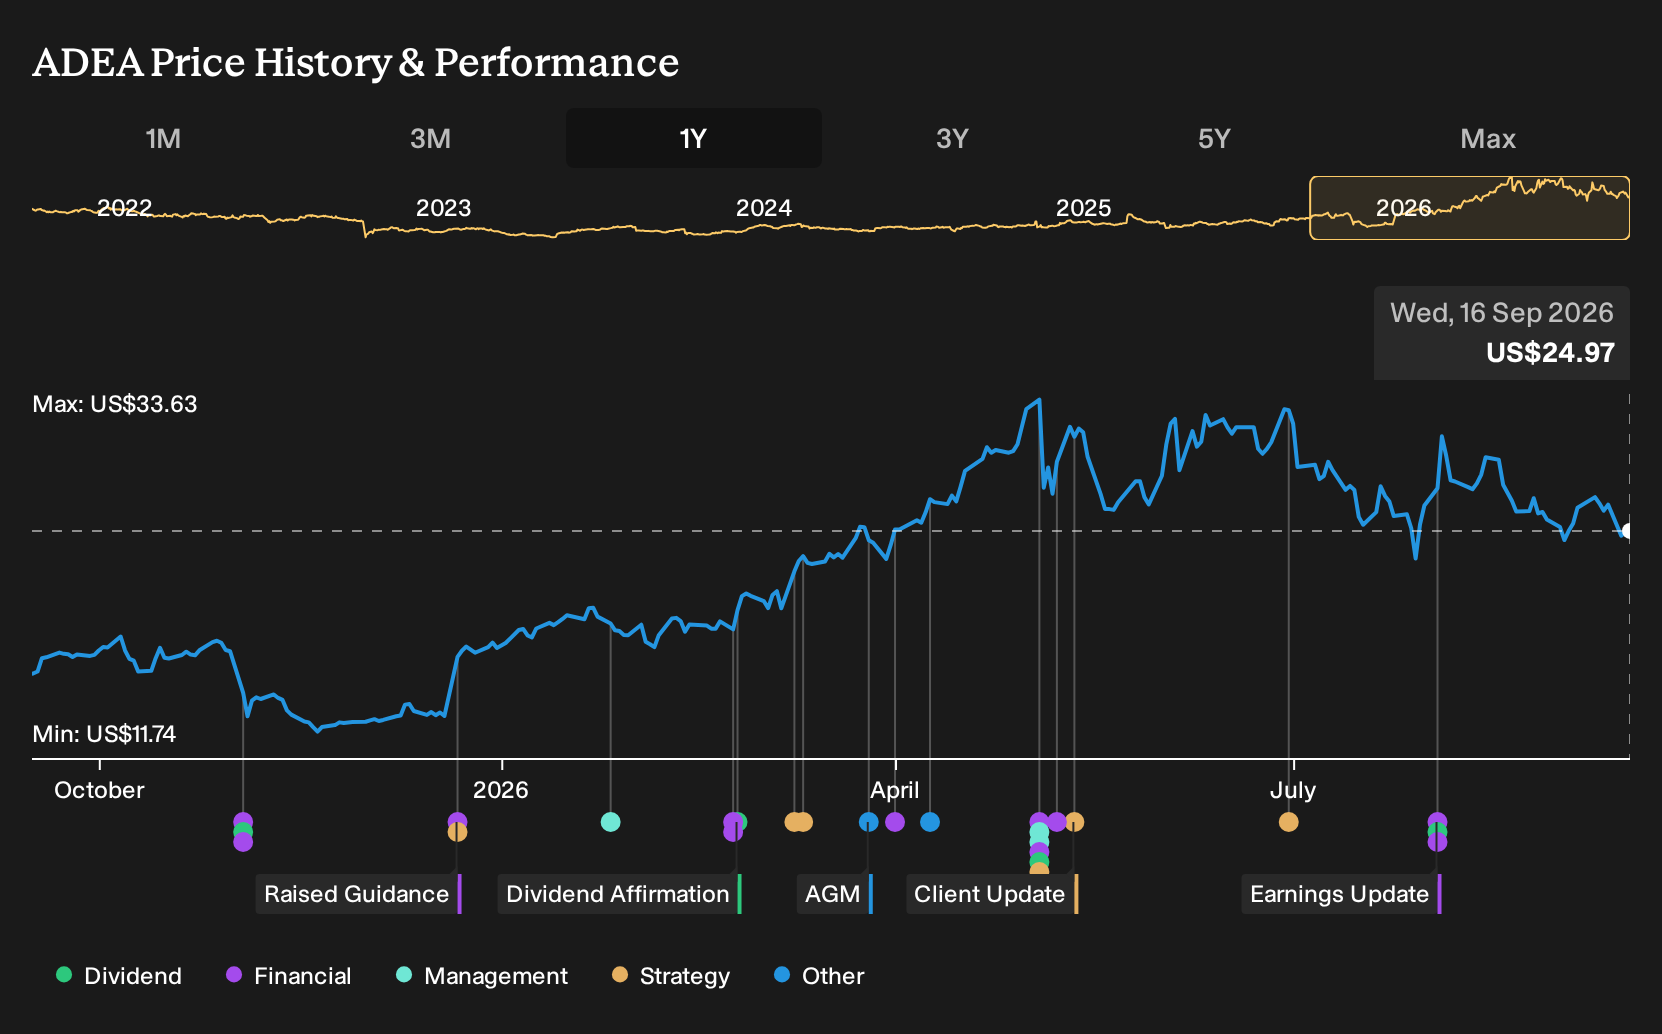
Against a current share price of $24.98, the $43.00 target sits 41.9% higher, with individual estimates ranging from $39.00 on the low end to $50.00 on the high end. The key tension for readers is that this valuation framework sits alongside forecasts that already bake in shrinking margins and lower earnings rather than a rising earnings base.
Adeia's narrative projects $465.3 million revenue and $108.1 million earnings by 2029. This implies flat revenue over the period and an earnings decrease of $14.6 million from $122.7 million today.
Uncover why Adeia's fair value indicates a 72% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You are seeing two very different stories about Adeia. Consensus leans on steady licensing and Asia traction, while the most cautious analysts worry more about shrinking legacy media deals. That group was only penciling in about $476.5 million of revenue and $112.0 million of earnings for 2029. Today's Asia Pacific awards could eventually shift those views, so consider them as moving pieces and explore several angles before deciding what the story looks like for you.
Explore 4 other Adeia fair value estimates, including one that suggests as much as 23% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Adeia research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Adeia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Adeia's overall financial health at a glance.
Looking For More Investment Ideas Beyond Adeia?
If the Adeia story has you thinking about how to balance potential upside with risk, it can help to line it up against other opportunities that match your own preferences for value, income or resilience.
- For readers who care most about buying quality at a reasonable entry point, start with a focused set of 33 high quality undervalued stocks that pair fundamentals with attractive pricing.
- If capital preservation and steadier business profiles rank higher on your list, concentrate on our 11 resilient stocks with low risk scores to see which stocks score well on resilience.
- When balance sheet strength is the priority, shortlist companies from the list of solid balance sheet and fundamentals (22 results) and stress test them against your own return expectations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com