
What Enpro (NPO) Earnings Upgrades Mean For Shareholders
- Enpro reported an improving earnings outlook, with full year earnings estimates raised by 4.5% in recent months and revenue growth guidance for 2026 set in a 10% to 14% range.
- The business has also outperformed a declining Business Services sector so far this year, which suggests that Enpro’s focus on higher value Technology Services and recurring industrial demand is resonating despite broader sector weakness.
- Now the focus turns to how this upgraded earnings trajectory at Enpro could reshape the longer term investment narrative around its growth profile.
Scan beyond Enpro and review a curated group of peers that also pair upgraded outlooks with resilient business models through the following screener: 33 high quality undervalued stocks.
Enpro Investment Narrative Recap
To own Enpro, you need to be comfortable with an industrial technology group leaning into higher value sealing and surface solutions tied to semiconductors, life sciences and aerospace, while still carrying exposure to choppy commercial vehicle and wafer equipment cycles. The recent uplift in full year earnings expectations and 2026 revenue growth guidance in the 10% to 14% range points to management leaning into that higher mix rather than pulling back.
The near term swing factor is execution on capacity expansions in places like Arizona, Milpitas and Taiwan, and translating those assets into profitable orders without letting operating costs run away. The biggest risk remains that these end markets stay soft or volatile while Enpro carries elevated spend, which could keep profit margins under pressure if demand falls short.
The most relevant update for this story is the company’s decision to set 2026 revenue growth guidance in that 10% to 14% band. That is a clear operational marker for how management sees demand for its Sealing Technologies and Advanced Surface Technologies franchises, especially in semiconductor, aerospace and life sciences related work.
For you as an investor, that guidance ties directly into the key catalysts and execution questions. It sharpens focus on whether Enpro can fill new capacity, grow recurring aftermarket and refurbishment activity, and keep a grip on expenses in the face of FX swings and prior one off charges that weighed on reported earnings quality and recent net margin compression.
Enpro Consensus Targets In Context
Enpro's current analyst framework points to revenue of about US$1.6b and earnings of roughly US$278.0m by 2029, built on an assumed 9.2% yearly revenue growth rate and an earnings step up of about US$234m from US$44.1m today.
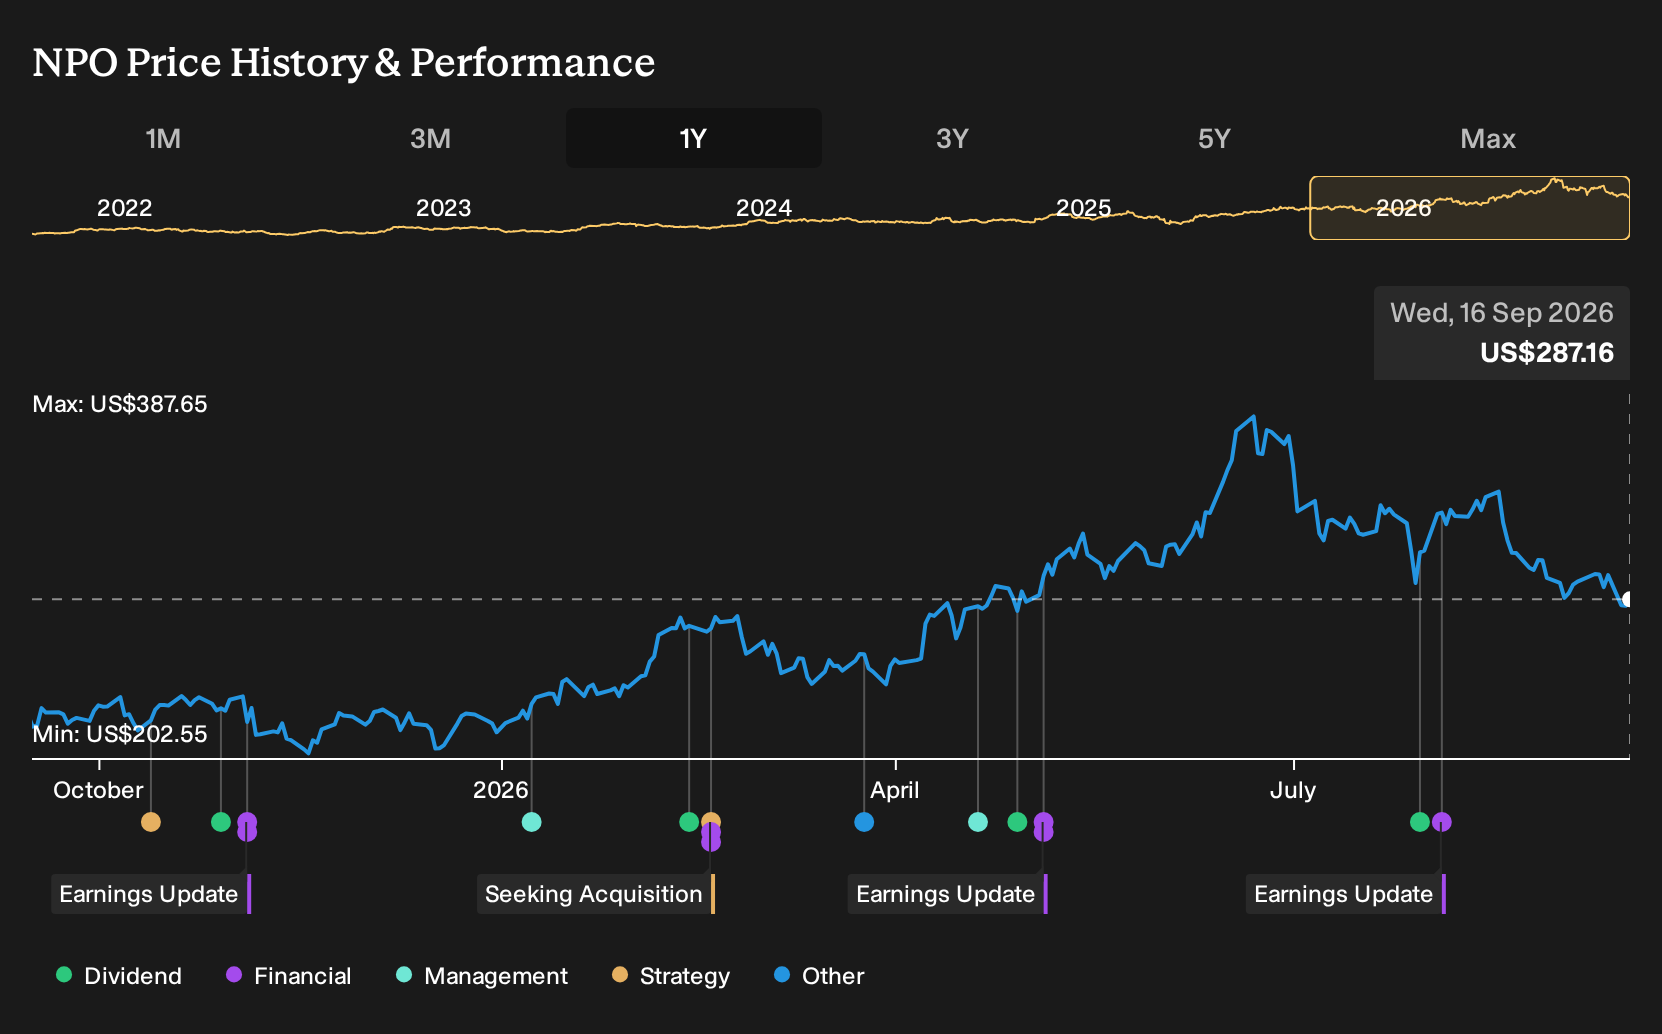
Uncover how Enpro's fair value indicates a 36% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between about US$368 and US$390, which signals little internal disagreement yet still leaves plenty of room for your own judgment. Set those views against Enpro’s exposure to cyclical commercial vehicle and semiconductor equipment demand, and decide how much volatility you are willing to accept.
Explore another Enpro fair value estimate, including one that suggests it could be worth just $368.10.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Enpro research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Enpro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enpro's overall financial health at a glance.
Looking For More Investment Ideas Beyond Enpro?
Once you have a view on Enpro, it can help to cross check that thinking against other companies that match the kind of quality, income, or risk profile you prefer. The Simply Wall St Screener gives you a quick way to line up different options side by side and see which ones fit your goals.
- If capital preservation and smoother returns matter most to you, start with a basket of 11 resilient stocks with low risk scores that score well on resilience.
- If you prefer companies that can fund themselves and keep investing without stretching the balance sheet, narrow your search to a list of solid balance sheet and fundamentals (22 results) that can handle tougher conditions.
- If you want to widen your watchlist beyond widely followed stocks, scan a curated pool of 16 high quality undiscovered gems that pair strong fundamentals with lower profile coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com