
DigitalOcean Stock Has The Bull Case Changed After $725 Million AI Hardware Financing
- DigitalOcean Holdings entered into a new $725 million equipment finance facility maturing in 2030 to fund GPU, CPU, and related hardware for its AI-Native Cloud platform, with an additional accordion option of up to $300 million subject to lender commitments.
- The funding structure is designed to align hardware cash outflows with revenue, which is important for how DigitalOcean balances heavy AI infrastructure needs with cash flow management and capital efficiency.
- This article reviews how DigitalOcean’s investment narrative is affected by using long-dated equipment financing to scale its AI-Native Cloud capacity.
Compare how DigitalOcean Holdings’ long term GPU financing approach stacks up against other AI capacity builders by scanning our hand picked 60 AI infrastructure stocks for potential peers and alternatives.
DigitalOcean Holdings Investment Narrative Recap
To own DigitalOcean Holdings, you need to believe the AI Native Cloud push can keep attracting developers and digital native enterprises while the firm manages capital intensity and competition from hyperscalers. The new US$725 million equipment facility speaks directly to that belief. It gives DigitalOcean a way to scale GPU and CPU capacity without heavy upfront cash strain.
The near term swing factor still sits in AI and higher value customers. Progress here could support revenue growth and help offset earnings that analysts expect to decline over the next 3 years. The biggest risk is straightforward. AI infrastructure adoption or pricing may not keep pace with the level of spending, which could pressure margins and free cash flow.
The equipment financing announcement ties closely to the AI story already in motion. Management has talked about AI and ML revenue growing very quickly and about strong demand from cost conscious customers moving from larger cloud providers. This facility is effectively the hardware backbone for that thesis, aligning with the focus on GPU droplets, bare metal GPUs and AI workloads.
For you as a shareholder, the key issue is execution. The business is investing heavily into gear that supports AI services such as the Gradient AI platform and agents, while analysts still model declining earnings and highlight competition and net dollar retention just under 100% as watchpoints. The facility does not change those risks. It increases the importance of getting AI capacity filled efficiently and priced with discipline.
DigitalOcean Holdings' current analyst narrative points to US$2.7b in revenue and US$287.2 million in earnings by 2029. That profile assumes revenue growth of 42.3% per year and an earnings increase of about US$50 million from the US$236.8 million reported today.
Uncover why DigitalOcean Holdings' fair value points to a 44% potential upside to its current price. This opportunity could narrow quickly if sentiment shifts.
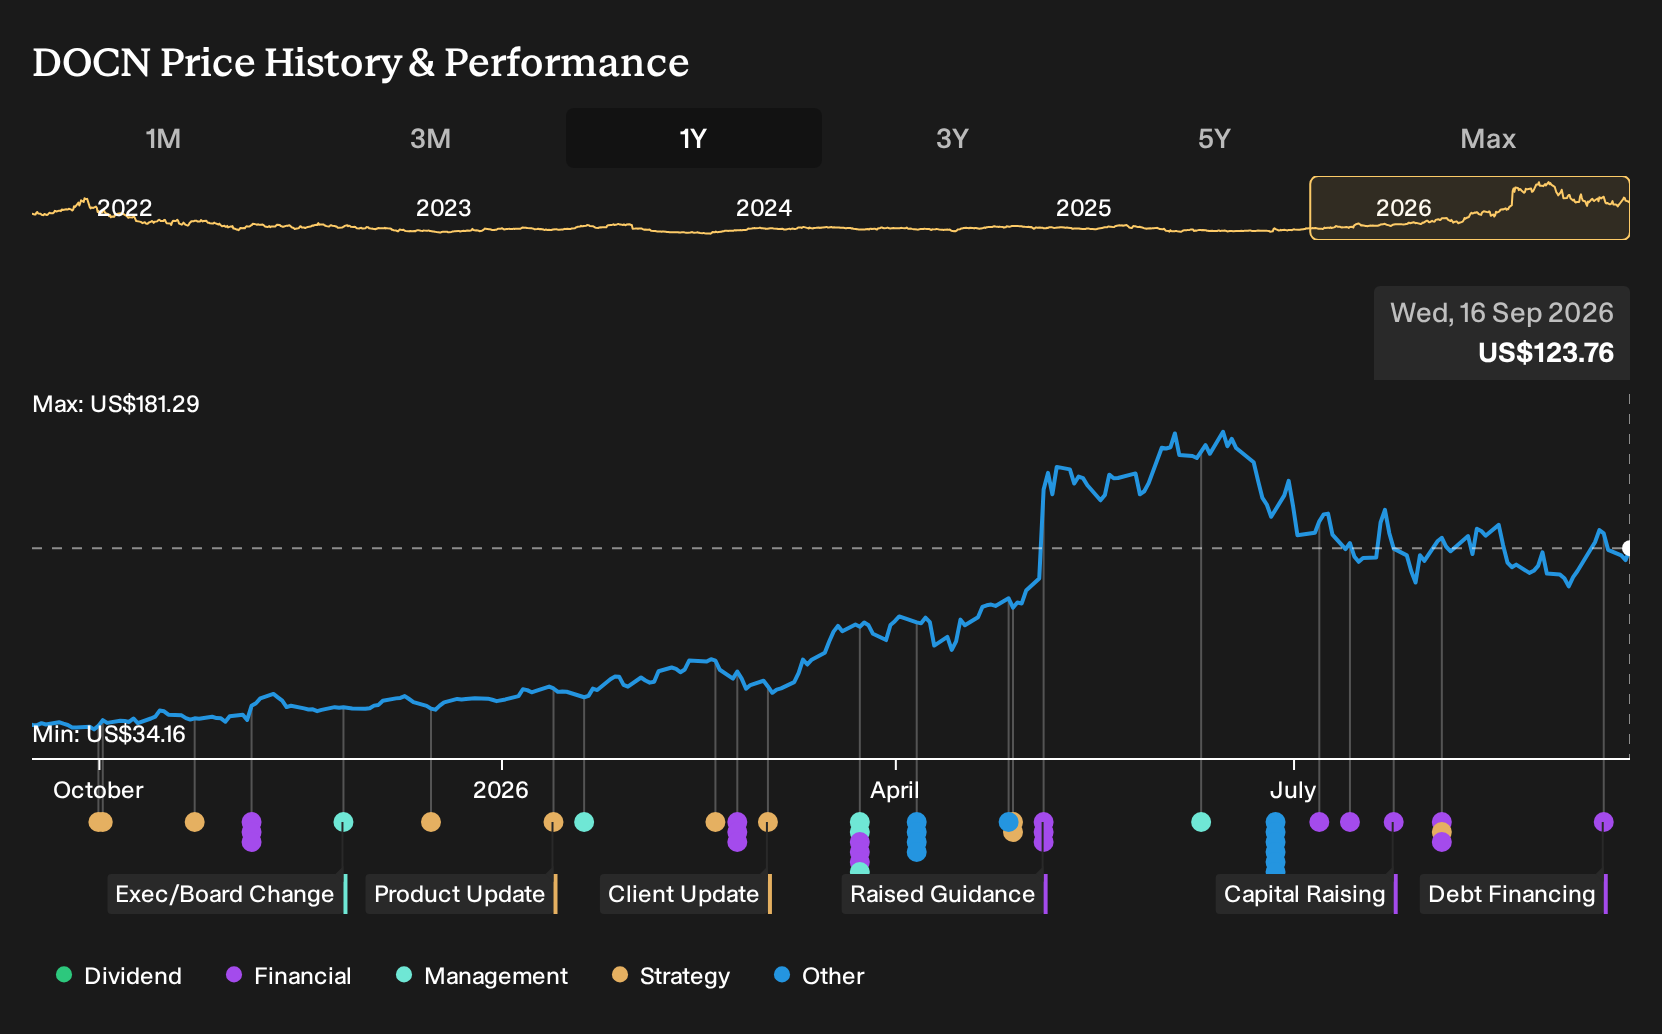
Exploring Other Perspectives
Some of the lowest analysts focus on margin risk instead. They model profit margins sliding toward 0.6% and earnings near US$17.0 million by 2029, even on roughly US$2.8b of revenue. That is far more pessimistic than consensus on DigitalOcean Holdings. Those views were set before this financing, so expectations could shift.
Explore 4 other DigitalOcean Holdings fair value estimates, including one that suggests it could be worth just $119.38.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your DigitalOcean Holdings research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for DigitalOcean Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DigitalOcean Holdings' overall financial health at a glance.
Looking for more investment ideas beyond DigitalOcean Holdings?
If DigitalOcean Holdings' AI Native Cloud story has you thinking about where else capital intensive growth or resilient cash generation might show up, it can help to scan a broader field of stocks that match different risk and return profiles.
- If you prefer compact companies with room to grow and stronger financial footing than the typical micro cap peer, then start with 11 elite penny stocks with strong financials as a way to spot candidates for deeper research.
- If value and balance sheet strength matter most to you, use the list of solid balance sheet and fundamentals (22 results) to quickly zero in on businesses that pair financial resilience with earnings support.
- If you are looking to back high quality operators that are less picked over by the crowd, scan the 16 high quality undiscovered gems and build a watchlist before attention catches up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com