
Damo: China's advanced packaging will reach 100 billion by 2029, equipment vendors are superior to packaging and testing factories, and ACM Research (ACMR.US) is the first to be launched
The Zhitong Finance App learned that Morgan Stanley released a research report saying that China's advanced packaging is still an AI-driven long-term growth track, but there is a differentiation between the growth in the scale of the industry and the increase in profits of packaging and testing plants.
Damo pointed out that the profit of sealing and testing plants depends on whether production capacity can be filled, and the income of equipment vendors depends on whether production capacity is under construction. Therefore, they prefer equipment vendors over sealing and testing plants, and those that increase their share in the sealing and testing process are preferred. The industry view remains “attractive”. Among the four major targets in this round of production expansion, ACM Research is the only major listed company among Damo's preferred stocks compared to US stocks.
The market size will reach 100 billion yuan in 2029
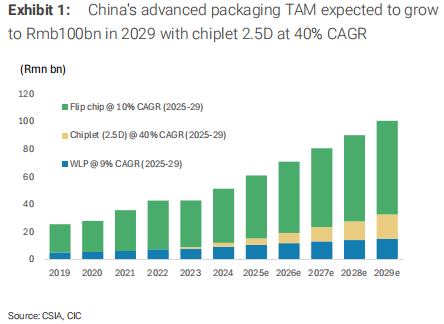
Research estimates that China's advanced packaging market will reach about RMB 100 billion in 2029, with a compound growth rate of about 13% from 2025 to 2029. Among them, Chiplet/2.5D grew the fastest, with a scale of about 17.7 billion yuan in 2029, with a compound growth rate of 40%; the growth rates of flip and wafer-level packaging were only 10% and 9%, respectively, during the same period.
Damo pointed out that the demand for computing power density, memory bandwidth, and heterogeneous integration of AI accelerators continues to increase, and in the context of limited access to advanced process front-end equipment, package-driven performance improvements have higher strategic value for China.
There is a moderate risk of excess
Research estimates that China's 2.5D annual production capacity will increase from 120,000 pieces in 2025 to 436,000 pieces in 2027, which is about 16% of overseas (mainly TSMC) production capacity. Many manufacturers, such as Changdian Technology, Tongfu Microelectronics, Huatian Technology, and Ningbo Silicon Electronics, are simultaneously expanding production. Combined with long equipment delivery times and domestic AI supply chain card demand, companies generally tend to “build production capacity first and then wait for orders.”
The demand side is constrained by advanced process yield and HBM supply: the bank expects Chinese manufacturers to ship 4.9 million AI GPUs in 2027, with about 21 good products per tablet and an overall yield of 85%, corresponding to the demand for about 277,000 wafers; while the domestic HBM3E has about 3 to 4 million units, which can only support 75 to 1 million GPUs, the rest still depends on overseas supply. According to comprehensive estimates, the industry's capacity utilization rate in 2027 is only about 63%. Furthermore, domestic production capacity mostly started with CoWoS-S, and next-generation products are shifting to CowOS-L, or there is a structural mismatch of “S-type overcapacity and L-type production capacity is tight”.
Equipment vendors can benefit more than test manufacturers
Damo said that regardless of whether the new sealing and testing capacity can eventually achieve ideal returns, the production capacity construction itself requires advance equipment investment; at the same time, the 2.5D/3D migration has brought an increase in processes such as fine RDL, TSV, wafer-level processing, temporary bonding, TCB, and hybrid bonding, and the value of equipment corresponding to the unit production capacity will rise accordingly. According to the data, the capital expenditure of global sealing and testing plants increased 65% year-on-year in 2025, and is expected to increase 67% in 2026, accounting for an all-time high.
The bank preferred ACM Research (ACMR.US) and ASMPT: The former benefited from wet processes such as electroplating and cleaning. Advanced packaging revenue (excluding ECP) increased 153% year-on-year in the second quarter of 2026, and received the first mass production order for 510 x 515 mm panel-level electroplating equipment from mainland Chinese customers; the latter is a TCB and hybrid bonding leader. The advanced packaging business revenue reached a record high of US$339 million in the first half of 2026, accounting for 30% of the group's revenue.
Short-term contributions of 3DIC, HBM, and CPO may be overestimated
The bank believes that the three technologies have significant strategic significance, but the profit contribution of the past two years has fallen short of market expectations. Among them, 3DIC is constrained by cost and compound yield, making it difficult to scale up during the year. The Chinese market size is only tens of millions of dollars in the next 2 to 3 years — although Huawei has applied logic stacking technology on its flagship processors and proposed a goal of reaching an equivalent 1.4 nanometer density by 2031; although HBM has the greatest potential demand, the packaging value remains mainly within the storage ecosystem, making it difficult for independent packaging and testing plants to directly benefit; large-scale CPO deployment is more likely to fall from 2027 to 2028.
Major beneficiaries of US stocks
Specifically, Damo gave ACM Research (ACMR.US) an increase in holdings rating. The target price was 130 US dollars, which implied about 94% upward space compared to the closing price of 66.9 US dollars on September 15. The risk-reward ratio was 6.3, ranking first among all targets.
This company's card position is in the process of rapidly increasing the strength of several equipment — wet processes such as electroplating and cleaning, which happen to be the steepest increase in the value of equipment per unit production capacity in 2.5D/3D and panel level packages. The fundamentals are already being realized: in the second quarter of 2026, its advanced packaging revenue (excluding ECP) increased 153% year over year, and it also shipped the 2000th electroplating chamber during the quarter; more importantly, it received a mass production order for the first 510 x 515 mm horizontal panel level electroplating equipment from a mainland Chinese customer, which meant that its panel-level package moved from “close to mass production” to “real mass production”. Furthermore, ACM Research Group is listed on NASDAQ, but its main production capacity and customers are in China, and it has the dual attributes of replacing US stocks with domestic products.