
What EQ Resources (ASX:EQR)'s U.S. Tungsten Plant Stake Means For Shareholders
- EQ Resources has agreed to acquire a 10% interest in a U.S. joint venture that aims to restart the 4,000 tonne per year Springer tungsten processing plant in Nevada, operated by The Elmet Group alongside Blue Moon Metals.
- The move gives EQ Resources an operating foothold in the North American critical minerals chain, adding tungsten processing exposure beyond its Australian base and directly linking the business to U.S. end demand.
- The next phase will center on how EQ Resources' planned role in restarting the Nevada tungsten plant could influence the broader investment narrative.
Scan other potential beneficiaries of the critical minerals push alongside EQ Resources by reviewing the hand picked 28 best rare earth metal stocks that could sit on the right side of future supply tightness.
What Is EQ Resources' Investment Narrative?
To own EQ Resources you need to buy into a tungsten focused growth story that hinges on getting projects built, processing plants running and offtake demand aligned with that capacity. The Springer joint venture stake fits that thesis by giving the group a small but direct link into U.S. critical minerals flows rather than relying only on Australian and European exposure. The key near term question is not the 10% interest on paper. It is whether management can execute across multiple assets while still unprofitable and working through capital hungry development plans.
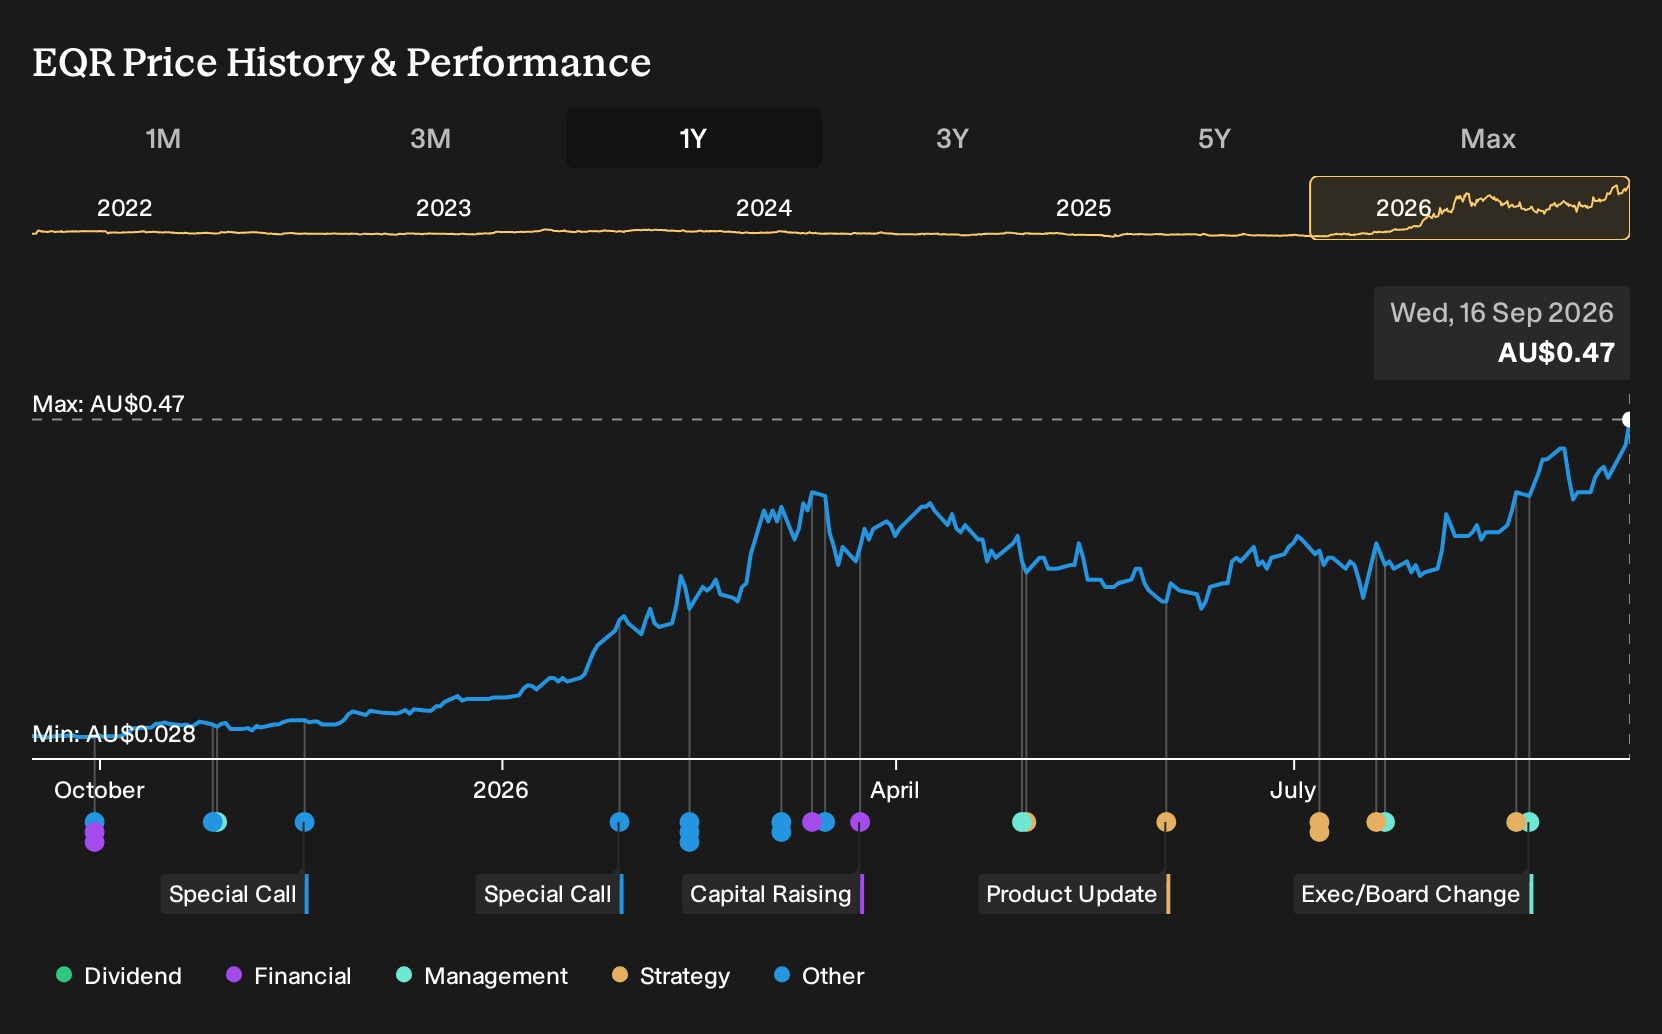
Short term catalysts still revolve around project ramp up, delivery against aggressive revenue and earnings forecasts, and any funding decisions after a period where shareholders have experienced substantial dilution. The Nevada plant restart adds another moving part. It potentially improves market access if U.S. tungsten demand tightens but also adds operational and coordination risk with partners. With the share price already sharply higher over the past year and trading on an elevated P/S multiple versus peers, execution missteps or slower than expected profitability could matter more than headline growth forecasts.
Even so, there is a less comfortable side to the EQ Resources story once you dig into how that growth might actually be funded and …
There's only one way to know the right time to buy, sell or hold EQ Resources. Head to Simply Wall St's company report for the latest analysis of EQ Resources's Fair Value.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span a wide band, from 0.25x to 2.69x the current EQ Resources share price. That kind of spread shows how far apart private investors can sit on expectations. The Nevada tungsten restart news has not been factored in, so you are seeing pre announcement views. Use that gap as a prompt to test your own thesis and compare it with several contrasting opinions.
Explore 2 other EQ Resources fair value estimates, including one that suggests as much as 45% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your EQ Resources research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for EQ Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EQ Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond EQ Resources?
Once you have formed a view on EQ Resources, broaden your watchlist by using the Simply Wall St Screener to spot other companies that fit the kind of risk and return profile you prefer.
- If capital protection is your priority, scan a basket of companies with resilient financial profiles using the 3 resilient stocks with low risk scores available on the screener.
- For investors who care most about rock solid finances, start with a list of solid balance sheet and fundamentals (12 results) and see which businesses hold up best under scrutiny.
- If you are hunting for under followed opportunities with room for a stronger market profile, sift through a curated set of 15 high quality undiscovered gems that could deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com