
Waka Partnership Could Be A Big Deal For OSL Group Stock (SEHK:863)
- OSL Group announced a collaboration with Waka that integrates its institutional stablecoin infrastructure into Waka’s settlement rails for Africa to global trade corridors, enabling regulated stablecoin to USD conversion and USD payouts for underserved cross border commerce.
- The tie up gives OSL Group deeper access to emerging market payment flows where traditional banking has been limited, directly linking its regulated stablecoin services to real economy supplier payments and business collections across African markets.
- We will now look at how OSL Group’s investment narrative is affected by this Waka partnership that targets Africa linked stablecoin payments.
OSL Group Investment Narrative Recap
To own OSL Group, you need to believe regulated stablecoins keep gaining traction in real world payments and that the firm can turn its global rails into fee rich, repeat transaction flows. The Waka partnership points in that direction by wiring OSL deeper into Africa to global trade corridors, but on its own it does not remove the short term focus on cutting losses and managing cash.
The biggest near term swing factor remains whether OSL Group can grow payment volume and stabilise operating costs before its reported cash runway tightens further. Key risk still sits with heavy spend on expansion, licensing and M&A while the group is loss making, plus regulatory changes that could slow activity in some jurisdictions.
The appointment of Wang Zheng as company secretary and authorised representative sits in the background of this payments push but still matters for investors watching execution. With a board that has seen high turnover and relatively low independence, stronger corporate governance and listing compliance experience can help OSL Group manage a widening regulatory footprint and complex cross border operations.
For catalysts, clean governance and tight compliance support the same thesis as the Waka deal. OSL Group wants to be the regulated bridge between stablecoin rails and institutional grade settlement. If governance and legal processes keep up with new licenses, acquisitions and products, the business has a better chance of converting partnerships into sustainable payment revenues while containing regulatory and integration risk.
OSL Group's narrative projects HK$1.5b revenue and HK$136.0 million earnings by 2029. This assumes 46.3% yearly revenue growth and an earnings swing of HK$522.8 million from a loss of HK$386.8 million today.
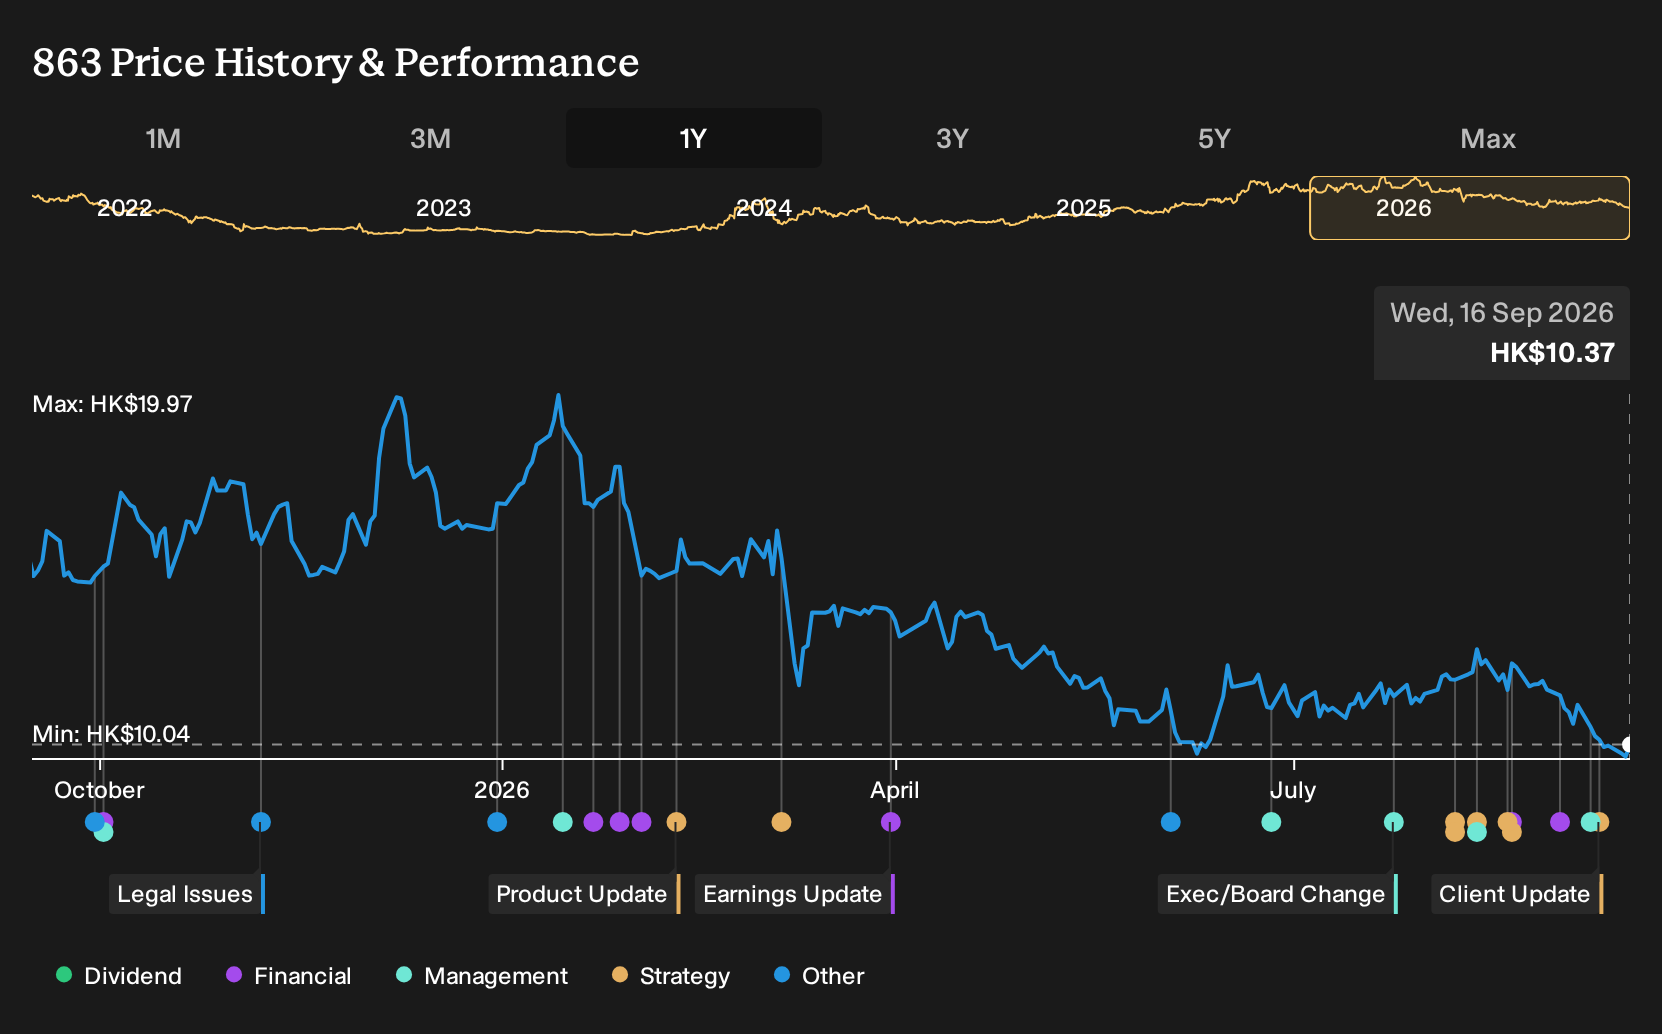
Discover why OSL Group's fair value indicates an 82% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between HK$18.62 and HK$18.86 per share, so you are not seeing wild valuation extremes yet. Those views were formed before the Waka deal and the governance reshuffle. If stablecoin adoption, regulation or cost control surprise, your own view on OSL Group could diverge sharply, so explore multiple community perspectives before drawing conclusions.
Explore another OSL Group fair value estimate, including one that suggests it could be worth just HK$18.62!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider going with your own instincts.
- A great starting point for your OSL Group research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for OSL Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OSL Group's overall financial health at a glance.
Looking for more OSL Group style investment ideas?
If the OSL Group story has you thinking about where else cross border payments, regulation and balance sheet strength intersect, the Simply Wall St Screener can help you broaden your watchlist without drowning in tickers.
- For investors who want income that does more of the heavy lifting, scan a universe of payout focused companies through 160 dividend fortresses that already clear a 5% yield hurdle.
- If capital preservation matters as much as upside, filter for sturdier businesses with lower risk profiles by starting with the 104 resilient stocks with low risk scores.
- To hunt for underfollowed opportunities with solid fundamentals, cast a wider net across our 619 high quality undiscovered gems that many investors may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com