
Undiscovered Gems In Global Markets For September 2026
As global markets navigate a landscape marked by rising oil prices and inflation concerns, small-cap stocks have faced increased volatility, with indices like the Russell 2000 experiencing notable declines. Amid these challenges, investors may find opportunities in undiscovered gems that exhibit resilience and potential for growth despite broader market pressures.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.39% | 25.87% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| C-Rad | NA | 13.57% | 13.83% | ★★★★★★ |
| GROUPE SFPI | 18.02% | 4.25% | -29.76% | ★★★★★★ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Aqualis | 33.30% | 22.28% | -18.13% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
VBG Group (OM:VBG B)
Simply Wall St Value Rating: ★★★★★☆
Overview: VBG Group AB (publ) is a company that develops, manufactures, markets, and sells industrial products globally with a market capitalization of approximately SEK7.83 billion.
Operations: VBG Group generates revenue primarily from three segments: Mobile Thermal Solutions (SEK2.81 billion), Truck & Trailer Equipment (SEK1.64 billion), and RINGFEDER Power Transmission (SEK1.09 billion).
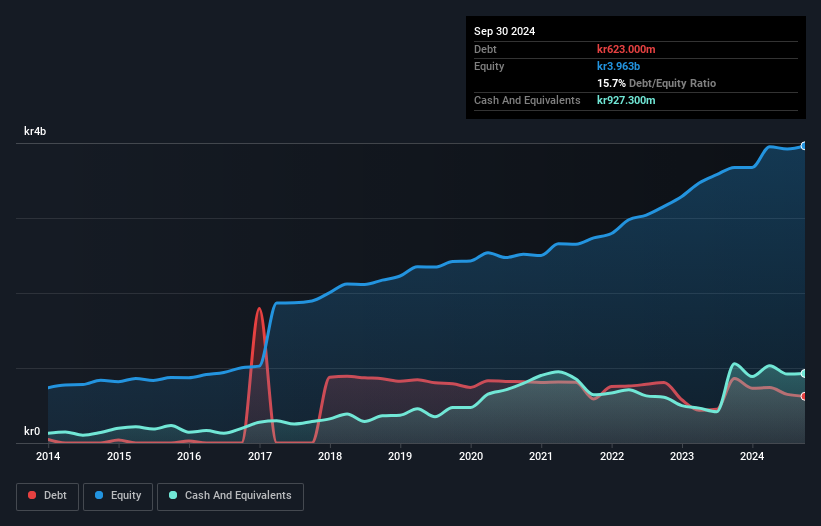
VBG Group, a notable player in the machinery sector, has shown a robust earnings growth of 4.5% over the past year, outpacing the industry average. The company's net debt to equity ratio stands at a satisfactory 17.4%, indicating prudent financial management despite an increase from 30.6% over five years. Its interest payments are well-covered by EBIT with a coverage of 14 times, reflecting strong operational performance and high-quality earnings. Trading at approximately 53.6% below its estimated fair value suggests potential upside for investors, although recent leadership changes and market shifts towards electrification present challenges ahead.
Almawarid Manpower (SASE:1833)
Simply Wall St Value Rating: ★★★★★★
Overview: Almawarid Manpower Company specializes in recruitment services for both domestic and expatriate labor, catering to domestic workers and temporary employment agencies in Saudi Arabia, with a market cap of SAR1.96 billion.
Operations: The company's revenue is primarily derived from three segments: Corporate (SAR2.40 billion), Individual (SAR328.44 million), and Hourly (SAR213.35 million).
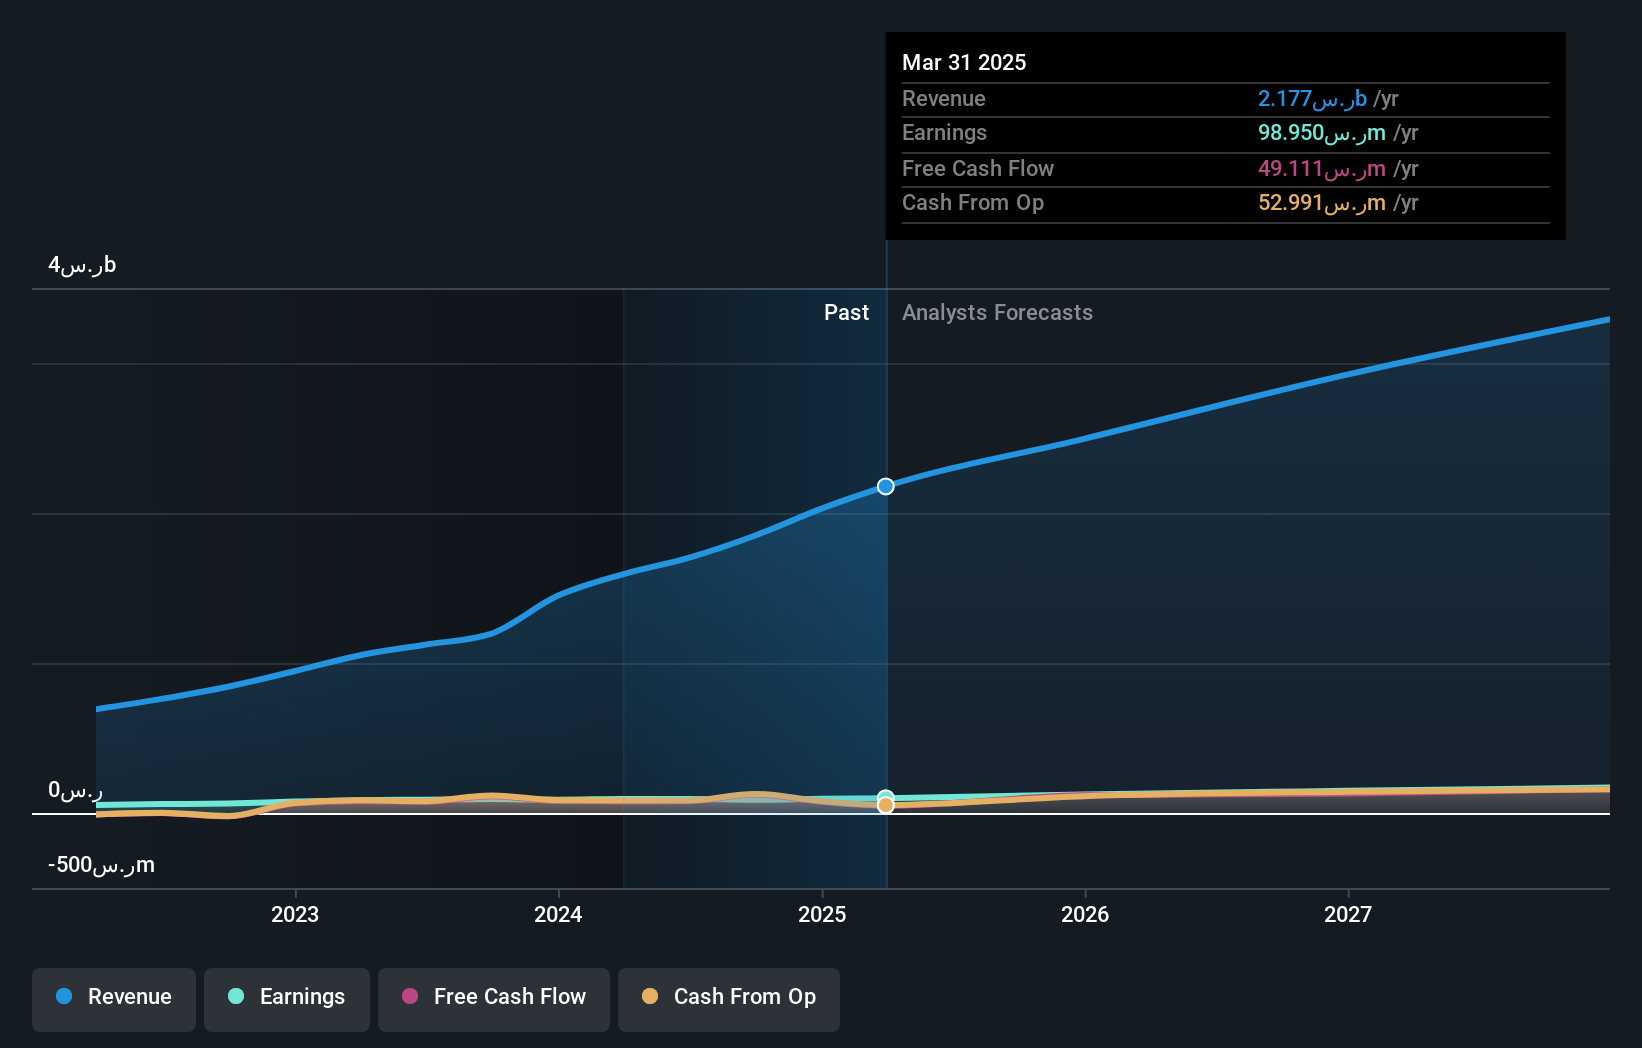
Almawarid Manpower, a relatively small player in the industry, is showing promising financial health with earnings growth of 65% over the past year, outperforming the Professional Services industry average of 39.2%. Trading at a significant discount of 69.3% below its estimated fair value and being debt-free enhances its appeal. The recent quarter saw sales climb to SAR 783.19 million from SAR 624.36 million last year, while net income rose to SAR 50.03 million from SAR 32.38 million previously, reflecting robust operational performance. With a forecasted revenue growth rate of approximately 9.56% annually, it seems poised for continued expansion in its sector.
- Click to explore a detailed breakdown of our findings in Almawarid Manpower's health report.
Explore historical data to track Almawarid Manpower's performance over time in our Past section.
Sodick (TSE:6143)
Simply Wall St Value Rating: ★★★★★★
Overview: Sodick Co., Ltd. is a company that develops, manufactures, and sells numerical control electric discharge machines (EDMs) both in Japan and internationally, with a market cap of approximately ¥81.96 billion.
Operations: Sodick generates revenue primarily from its Machine Tool Business, which accounts for ¥67.34 billion. The Industrial Machinery and Food Machinery segments contribute ¥10.39 billion and ¥6.94 billion, respectively, to the overall revenue stream.
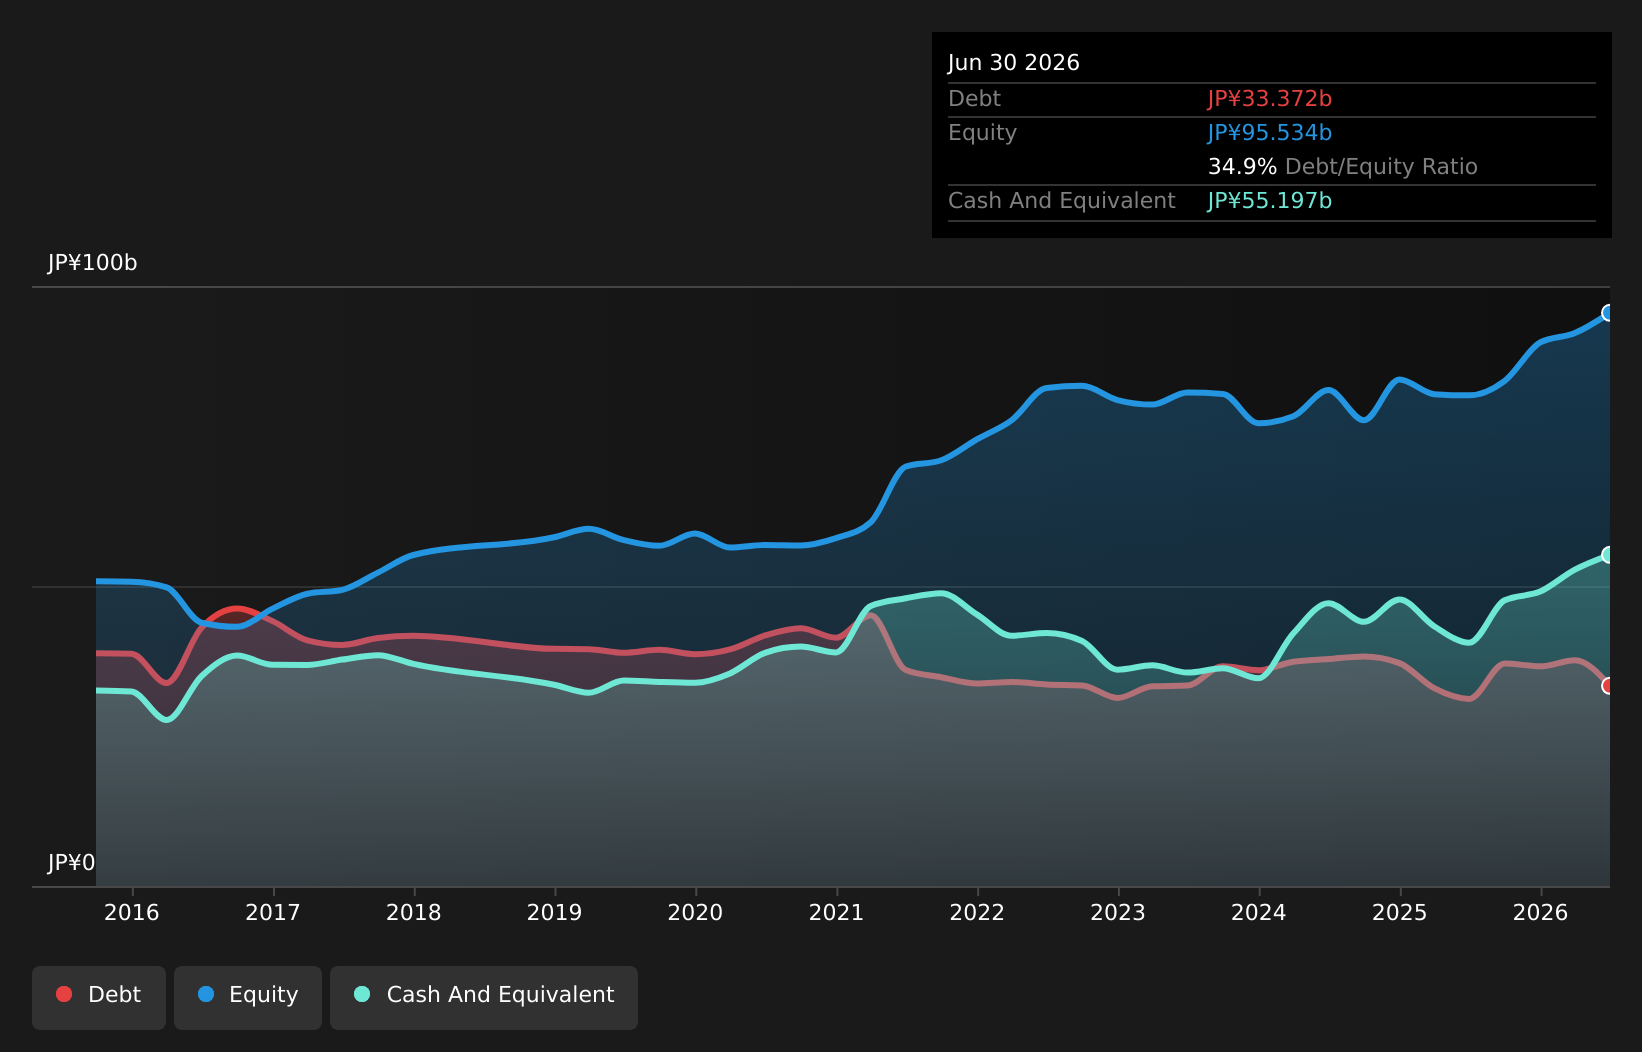
Sodick, a nimble player in the machinery sector, has seen its earnings soar by 68% over the past year, outpacing industry growth. The company's debt to equity ratio improved from 51.5% to 34.9% in five years, reflecting prudent financial management. Recently reported half-year sales hit JPY 46.92 billion compared to JPY 37.98 billion last year, while net income jumped to JPY 3.98 billion from JPY 1.09 billion a year ago. With strong demand for EDMs in Greater China and favorable currency movements boosting results, Sodick's revised guidance anticipates robust net sales and operating profit for the fiscal year ending December 2026.
- Delve into the full analysis health report here for a deeper understanding of Sodick.
Evaluate Sodick's historical performance by accessing our past performance report.
Summing It All Up
- Discover the full array of 167 Global Undiscovered Gems With Strong Fundamentals right here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com