
Global's September 2026 Stocks Possibly Trading Below Estimated Fair Value
In September 2026, global markets have been marked by heightened volatility, driven by escalating geopolitical tensions in the Middle East and rising oil prices, which have fueled inflation concerns and influenced monetary policy expectations. Amidst these challenges, investors are increasingly focused on identifying stocks that may be trading below their estimated fair value as a potential opportunity to navigate the current economic landscape. In such an environment, a good stock is often characterized by strong fundamentals and resilience to external pressures.
Top 10 Undervalued Stocks Based On Cash Flows
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Sulzer (SWX:SUN) | CHF146.80 | CHF288.52 | 49.1% |
| Shizuki Electric (TSE:6994) | ¥1172.00 | ¥2299.64 | 49% |
| P.S.P. Specialties (SET:PSP) | THB7.70 | THB14.85 | 48.1% |
| PAL GROUP Holdings (TSE:2726) | ¥1490.00 | ¥2880.38 | 48.3% |
| KSB SE KGaA (XTRA:KSB) | €914.00 | €1765.43 | 48.2% |
| Koninklijke BAM Groep (ENXTAM:BAMNB) | €11.68 | €23.14 | 49.5% |
| Dongwon Industries (KOSE:A006040) | ₩36050.00 | ₩70862.49 | 49.1% |
| Cheil Worldwide (KOSE:A030000) | ₩17370.00 | ₩34046.66 | 49% |
| Boliden (OM:BOL) | SEK522.40 | SEK1016.43 | 48.6% |
| AK Medical Holdings (SEHK:1789) | HK$4.855 | HK$9.60 | 49.4% |
Here we highlight a subset of our preferred stocks from the screener.
Neway Valve (Suzhou) (SHSE:603699)
Overview: Neway Valve (Suzhou) Co., Ltd. is engaged in the research, development, production, and sale of industrial valves both in China and internationally, with a market cap of CN¥33.82 billion.
Operations: The company generates its revenue primarily from the valve industry, amounting to CN¥8.26 billion.
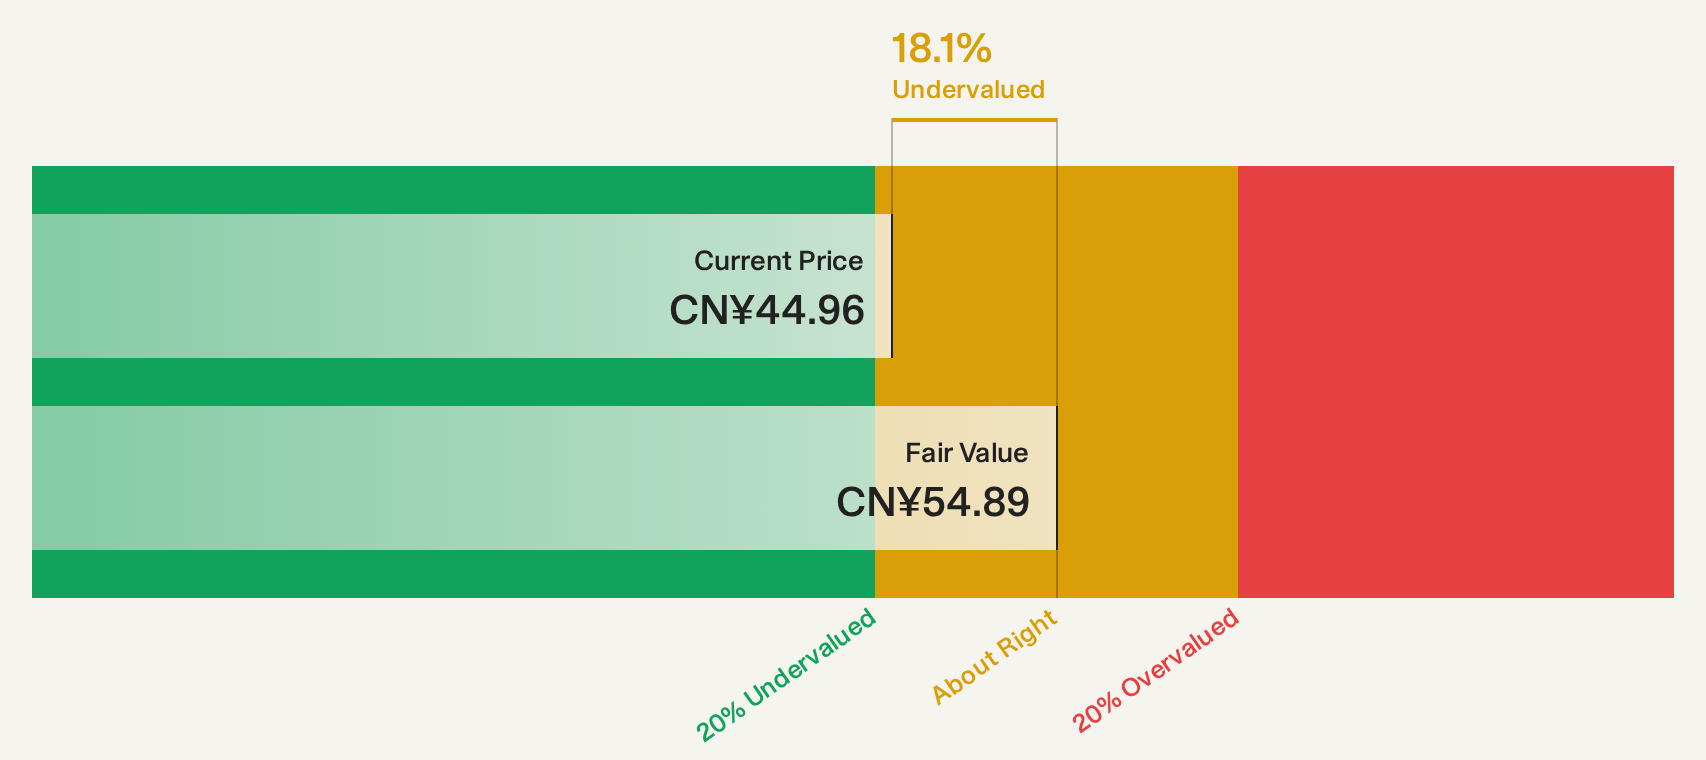
Estimated Discount To Fair Value: 19.3%
Neway Valve (Suzhou) reported strong earnings growth, with net income rising to CNY 733.38 million for the first half of 2026. The stock is trading at 19.3% below its estimated fair value and below future cash flow value, though not significantly so. While revenue and earnings are forecasted to grow slower than the market, analysts agree on a potential price increase of 55.9%, making it an attractive option based on current valuations.
- Upon reviewing our latest growth report, Neway Valve (Suzhou)'s projected financial performance appears quite optimistic.
- Unlock comprehensive insights into our analysis of Neway Valve (Suzhou) stock in this financial health report.
International Games SystemLtd (TPEX:3293)
Overview: International Games System Co., Ltd. engages in the planning, design, research, development, manufacturing, marketing, servicing, and licensing of arcade, online, and mobile games across Taiwan, the United Kingdom, Curacao, and Malta with a market cap of NT$199.52 billion.
Operations: The company generates revenue from its Online Games Division, which accounts for NT$17.74 billion, and its Business Game Division, contributing NT$6.01 billion.
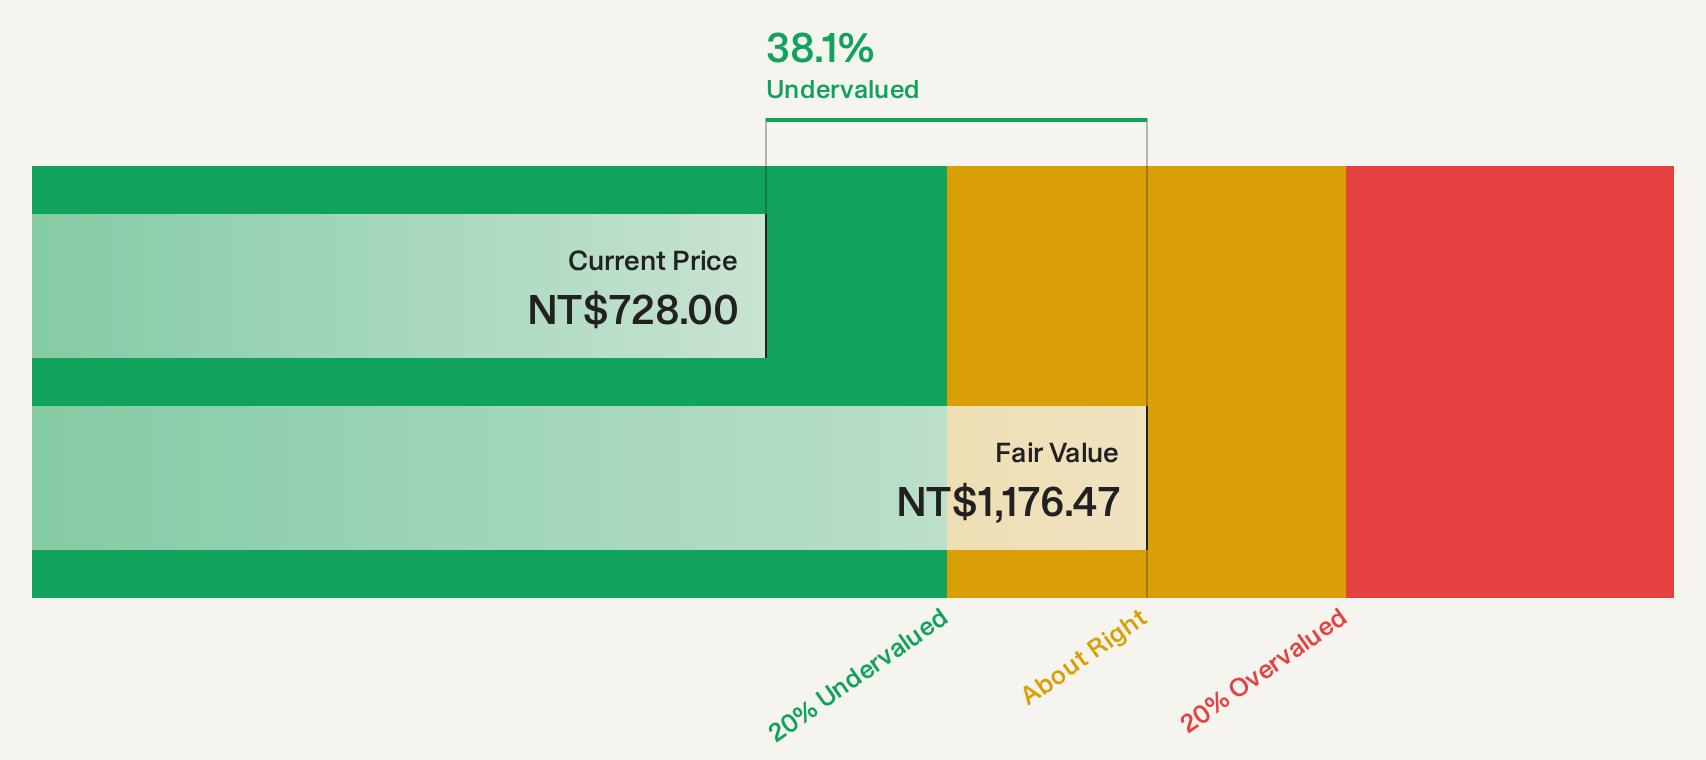
Estimated Discount To Fair Value: 38.3%
International Games System Ltd. reported strong earnings growth with net income reaching TWD 3.27 billion in Q2 2026, up from TWD 2.44 billion a year ago. The stock trades at a significant discount of over 20% below its estimated future cash flow value and is priced at NT$723 compared to an estimated fair value of NT$1171.92. Despite slower forecasted revenue and profit growth than the market, analysts predict a potential price rise of 36.8%.
- Our expertly prepared growth report on International Games SystemLtd implies its future financial outlook may be stronger than recent results.
- Dive into the specifics of International Games SystemLtd here with our thorough financial health report.
Terumo (TSE:4543)
Overview: Terumo Corporation manufactures and sells medical products and equipment globally, including in Japan, Europe, China, the United States, and Asia, with a market cap of ¥3.31 trillion.
Operations: The company's revenue is primarily derived from its Cardiac and Vascular Company segment at ¥706.74 billion, followed by the Medical Care Solutions Company at ¥222.32 billion, and the Blood and Cell Technologies Company at ¥240.17 billion.
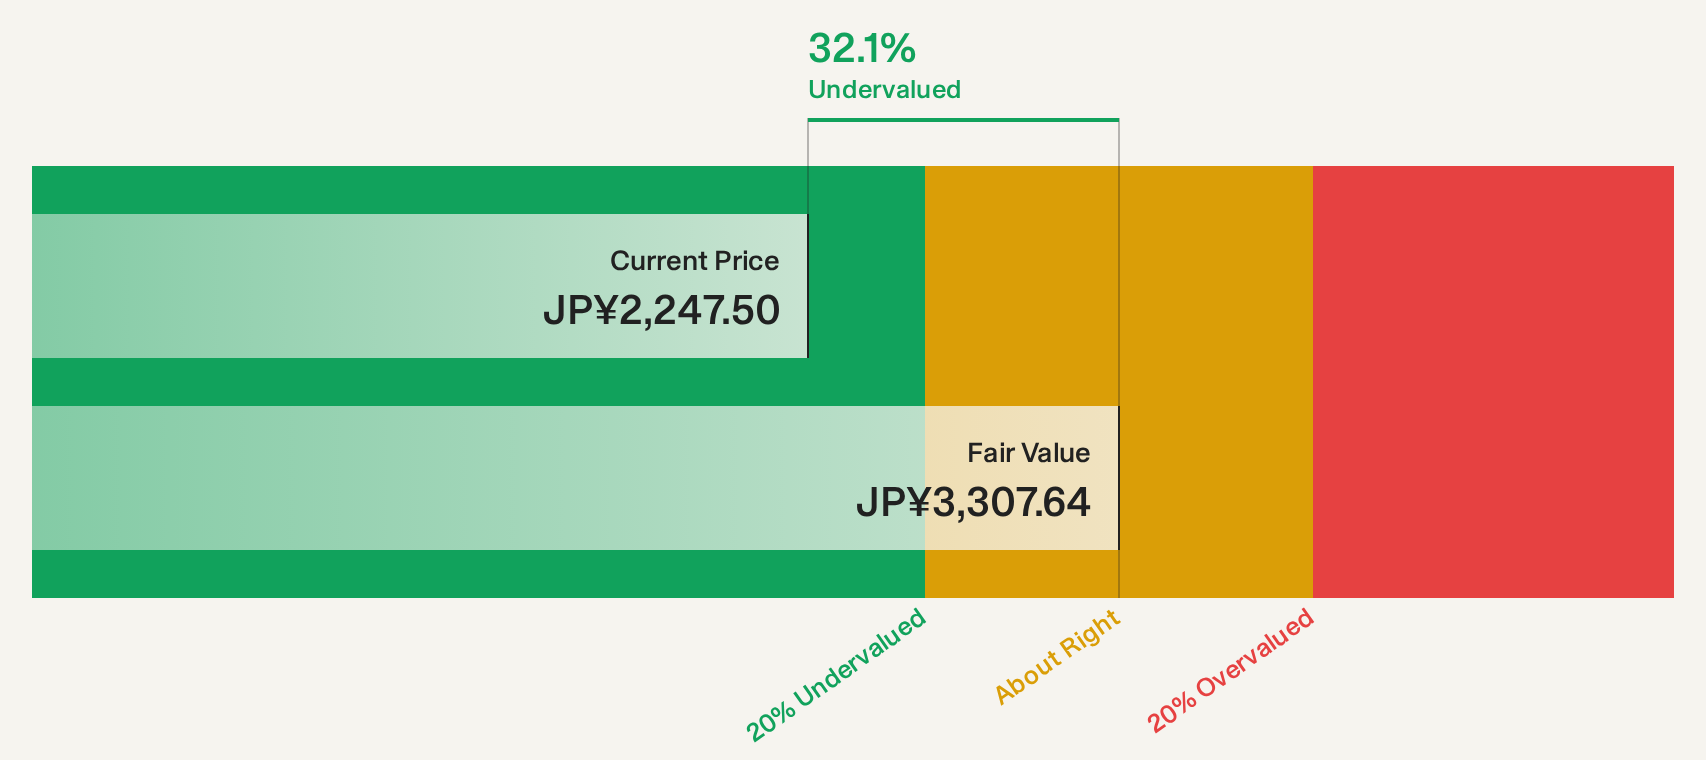
Estimated Discount To Fair Value: 30.7%
Terumo Corporation's stock is trading at ¥2290, significantly below its estimated future cash flow value of ¥3306.1, representing a discount of over 20%. Despite slower forecasted revenue and earnings growth compared to the Japanese market, recent upward revisions in profit guidance due to U.S. tariff refunds and settlement proceeds highlight financial resilience. Analysts agree on a potential price increase of 35.8%, with the stock trading at 30.7% below its fair value estimate.
- Our earnings growth report unveils the potential for significant increases in Terumo's future results.
- Take a closer look at Terumo's balance sheet health here in our report.
Where To Now?
- Gain an insight into the universe of 107 Undervalued Global Stocks Based On Cash Flows by clicking here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com