
Will Earnings Beat Change Sotera Health (SHC) Narrative
- Sotera Health recently reported robust second quarter 2026 results, with revenue supported by all three segments, and raised its full-year outlook on the back of pricing, volume mix, and efficiency gains.
- Management is now actively evaluating M&A focused on Sterigenics and other sterilization services. This signals a push to scale a core earnings engine while still managing ongoing ethylene oxide regulatory and litigation exposure.
- We will now examine how Sotera Health's stronger guidance shapes the existing investment narrative that leans on volume growth and cash generation.
Compare Sotera Health's acquisition push with other potential compounders by scanning our curated 16 high quality undiscovered gems that may be quietly building scale and cash generation of their own.
Sotera Health Investment Narrative Recap
Sotera Health may appeal to shareholders who believe sterilization and lab testing will continue to generate steady demand and that the company can convert that demand into cash, even with heavy compliance spending. The raised full-year outlook relies on pricing, mix, and efficiency, so in the near term the main catalyst remains execution on margins and cash conversion rather than pure volume.
The biggest risk still lies with ethylene oxide regulation and litigation, as well as the elevated capital spending tied to emissions controls. The renewed M&A push does not materially change that in the near term. It mainly adds another layer of capital allocation decisions that investors need to track relative to leverage and free cash flow.
The most relevant development is management’s indication that Sotera Health is actively evaluating M&A focused on Sterigenics and broader sterilization services. This is significant because Sterigenics already accounts for most of the segment’s revenue and is central to many of the volume and margin factors investors monitor, including higher throughput and better asset utilization.
Each tuck-in deal can be viewed as a potential swing factor for execution on those catalysts and on risk. Acquisitions that increase ethylene oxide exposure could heighten regulatory and legal concentration risk, while assets tilted toward other sterilization modalities may help diversify that exposure. In either case, the outcome of this strategy will be reflected in utilization, margins, and debt coverage over time.
Sotera Health's narrative projects US$1.4b revenue and US$321.4 million earnings by 2029. This implies 5.8% yearly revenue growth and roughly US$157.9 million earnings increase from US$163.5 million today.
Uncover why Sotera Health's fair value indicates an 18% potential upside to its current price that may not last much longer.
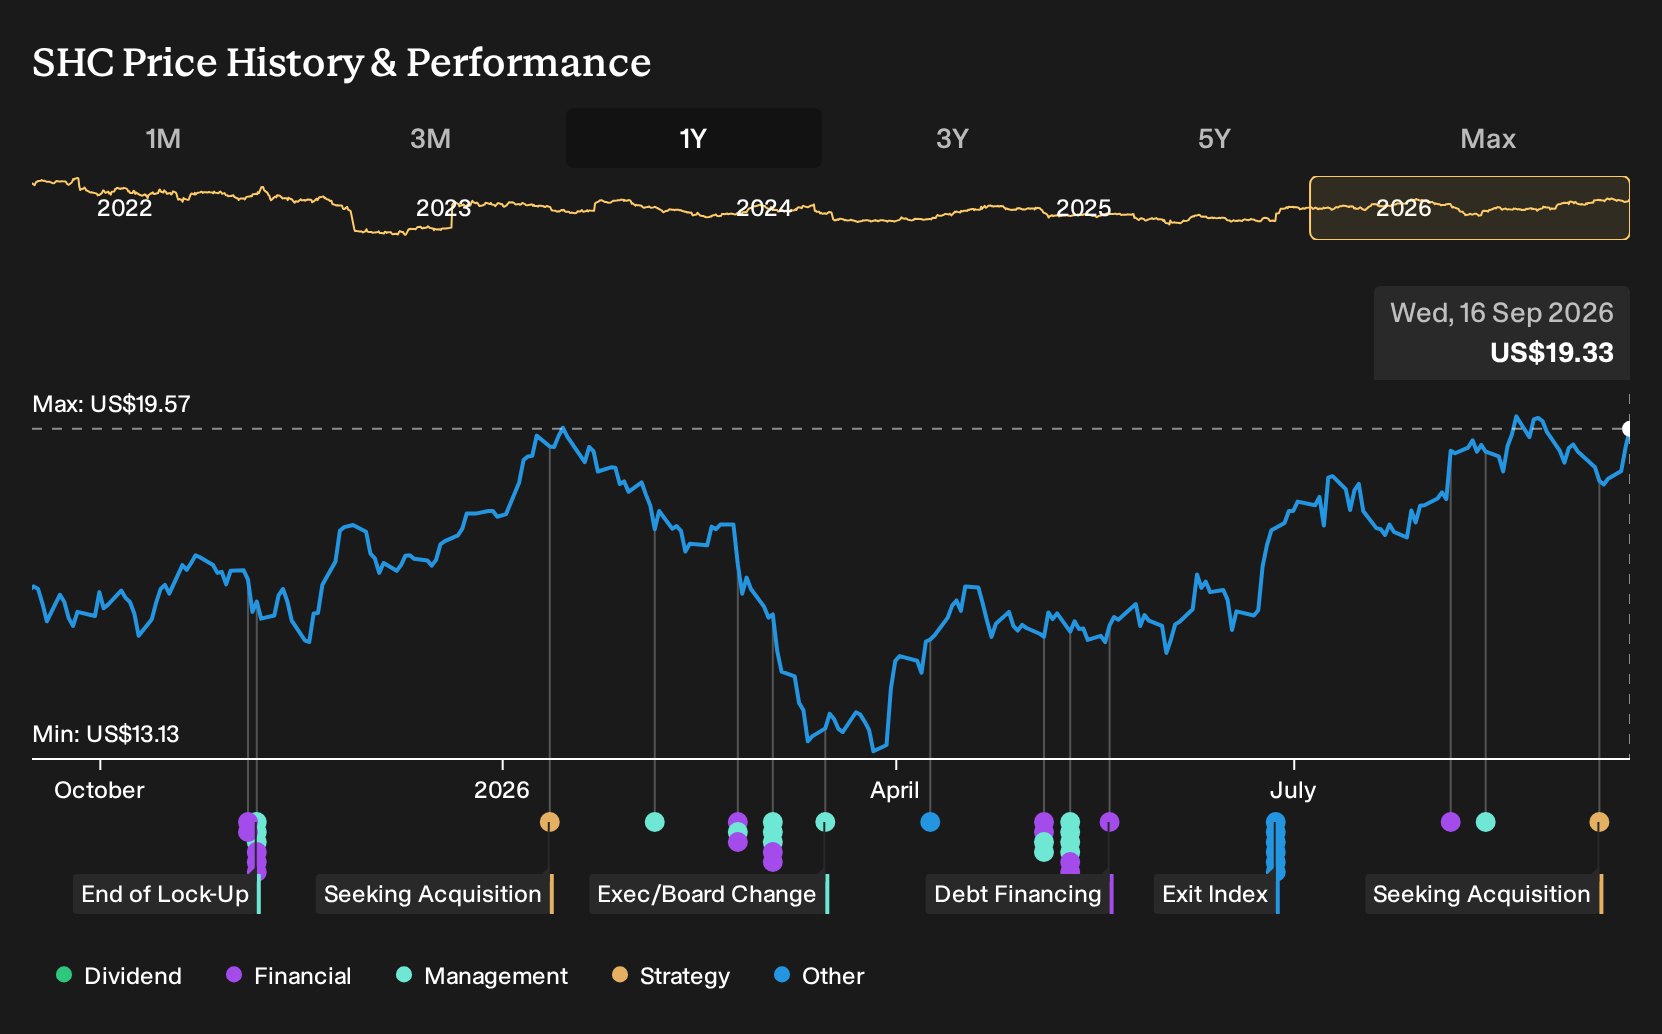
Exploring Other Perspectives
For Sotera Health, the real fork in the road some analysts focused on was Nordion’s Cobalt 60 supply risk. The most cautious group was already penciling in revenue growth of 5.6% a year and about US$280.7 million in 2029 earnings. That is a much gloomier story than consensus. These views were set before the new M&A comments, so you may want to compare them and decide which version of the future feels more realistic to you.
Explore another Sotera Health fair value estimate, including one that suggests it could be worth just $22.72.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sotera Health research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sotera Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sotera Health's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sotera Health?
If the Sotera Health story has sharpened your thinking on risk, cash generation, and balance sheet strength, it can be useful to test that framework on a wider watchlist. Use the Simply Wall St screener to line up other businesses against the same questions you are asking here and spot opportunities that fit your style.
- For investors hunting for strong fundamentals without taking on excessive financial strain, start with a list of solid balance sheet and fundamentals (22 results) that can handle pressure when conditions change.
- If capital preservation and a smoother ride matter most to you, filter for a 11 resilient stocks with low risk scores that screens well on quality and volatility.
- If you prefer to focus on potential mispricing and quality together, rather than just a cheap P/E, scan a 33 high quality undervalued stocks that pairs financial strength with undemanding valuations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com