
Metalsource Mining (CSE:MSM) Is In A Good Position To Deliver On Growth Plans
Just because a business does not make any money, does not mean that the stock will go down. By way of example, Metalsource Mining (CSE:MSM) has seen its share price rise 211% over the last year, delighting many shareholders. But the harsh reality is that very many loss making companies burn through all their cash and go bankrupt.
So notwithstanding the buoyant share price, we think it's well worth asking whether Metalsource Mining's cash burn is too risky. For the purposes of this article, cash burn is the annual rate at which an unprofitable company spends cash to fund its growth; its negative free cash flow. Let's start with an examination of the business' cash, relative to its cash burn.
How Long Is Metalsource Mining's Cash Runway?
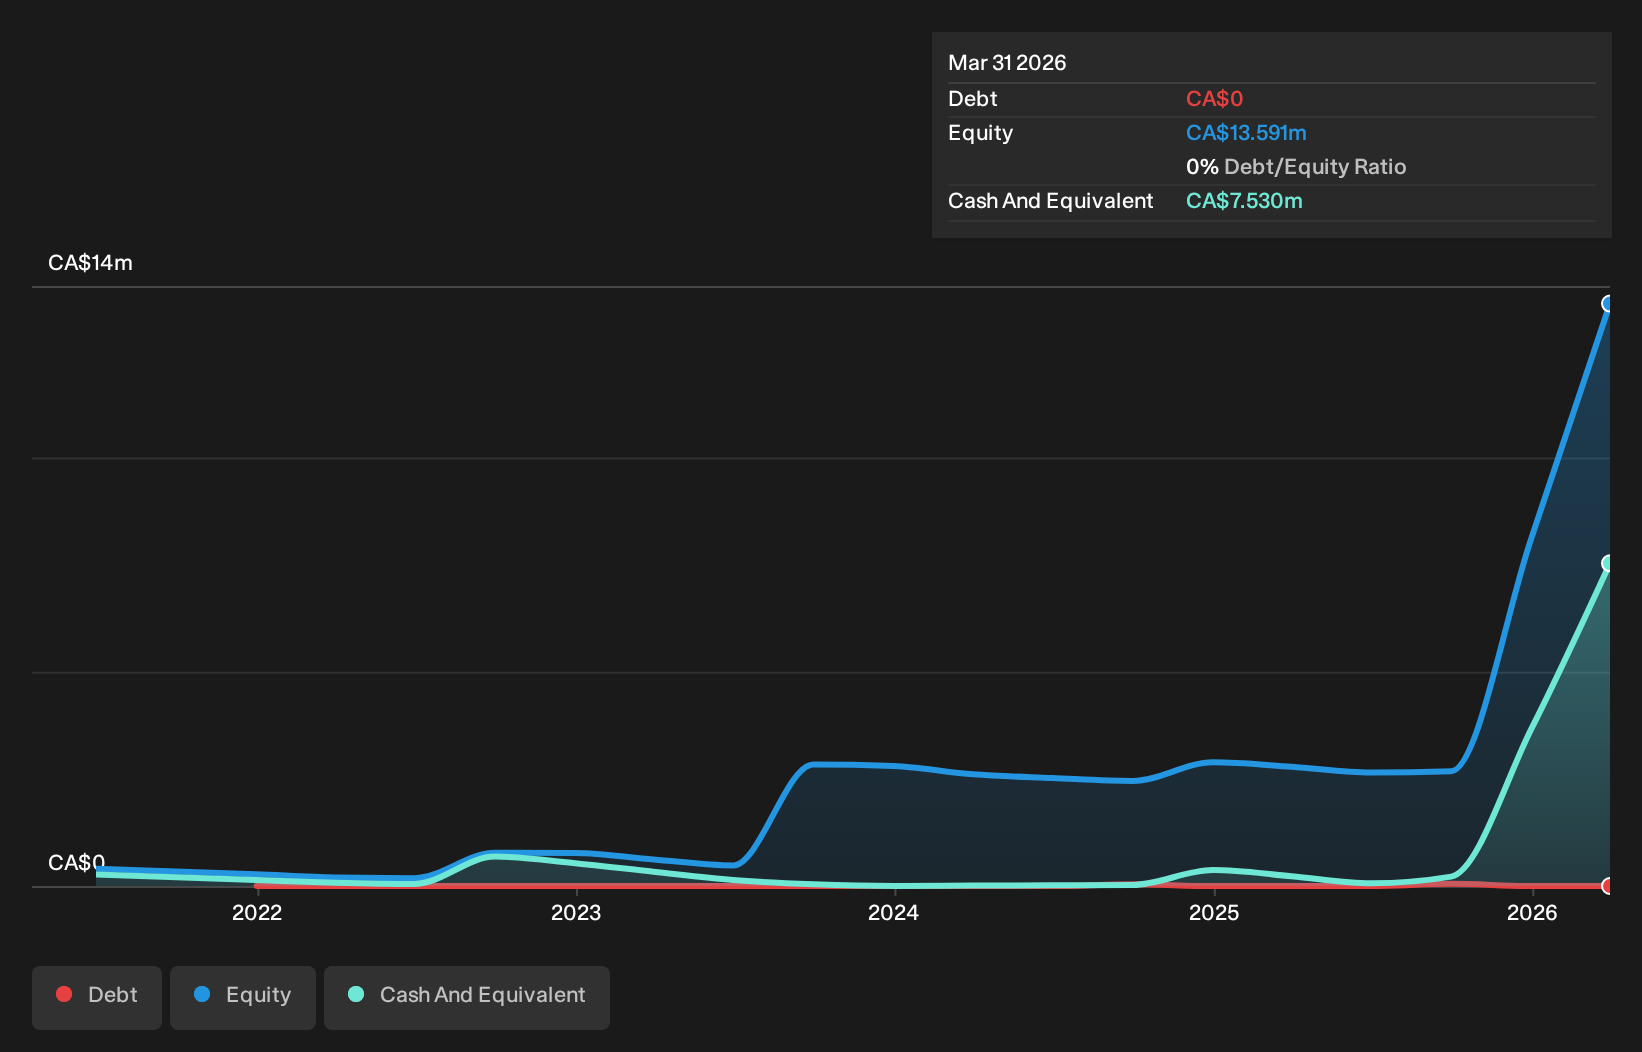
A company's cash runway is calculated by dividing its cash hoard by its cash burn. In March 2026, Metalsource Mining had CA$7.5m in cash, and was debt-free. In the last year, its cash burn was CA$4.0m. Therefore, from March 2026 it had roughly 22 months of cash runway. While that cash runway isn't too concerning, sensible holders would be peering into the distance, and considering what happens if the company runs out of cash. Depicted below, you can see how its cash holdings have changed over time.
See our latest analysis for Metalsource Mining
How Is Metalsource Mining's Cash Burn Changing Over Time?
Because Metalsource Mining isn't currently generating revenue, we consider it an early-stage business. Nonetheless, we can still examine its cash burn trajectory as part of our assessment of its cash burn situation. Remarkably, it actually increased its cash burn by 628% in the last year. With that kind of spending growth its cash runway will shorten quickly, as it simultaneously uses its cash while increasing the burn rate. Admittedly, we're a bit cautious of Metalsource Mining due to its lack of significant operating revenues. So we'd generally prefer stocks from this list of stocks that have analysts forecasting growth.
How Easily Can Metalsource Mining Raise Cash?
While Metalsource Mining does have a solid cash runway, its cash burn trajectory may have some shareholders thinking ahead to when the company may need to raise more cash. Companies can raise capital through either debt or equity. Many companies end up issuing new shares to fund future growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Metalsource Mining has a market capitalisation of CA$63m and burnt through CA$4.0m last year, which is 6.4% of the company's market value. Given that is a rather small percentage, it would probably be really easy for the company to fund another year's growth by issuing some new shares to investors, or even by taking out a loan.
How Risky Is Metalsource Mining's Cash Burn Situation?
On this analysis of Metalsource Mining's cash burn, we think its cash burn relative to its market cap was reassuring, while its increasing cash burn has us a bit worried. Cash burning companies are always on the riskier side of things, but after considering all of the factors discussed in this short piece, we're not too worried about its rate of cash burn. Taking a deeper dive, we've spotted 4 warning signs for Metalsource Mining you should be aware of, and 3 of them are a bit unpleasant.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of interesting companies, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.