
Mitsubishi Electric (TSE:6503) Gains Quantum Backing Following A Fresh Undervalued Narrative
Mitsubishi Electric (TSE:6503) just secured government-backed support for two post-5G quantum computing R&D projects, a move that puts its advanced hardware work firmly in focus for anyone tracking the stock.
Recent trading has been choppy for Mitsubishi Electric, with the share price down about 15% over the past month and roughly 15% lower over 90 days, even though the year-to-date share price return is positive and the 1-year and multi-year total shareholder returns are very strong. A cluster of announcements in September, including the NEDO backed quantum projects, new heat pump technology, data center cooling products and EU certified safety controllers, shows the business leaning into high demand areas such as factory automation, energy efficiency and computing infrastructure. This helps explain why long term total shareholder returns have been so much stronger than the shorter term share price moves.
Scan beyond Mitsubishi Electric and find other potential beneficiaries of the same themes in factory automation, data centers and quantum hardware with our curated list of 60 AI infrastructure stocks.
Mitsubishi Electric has given back a chunk of recent gains, even while its long run record and fresh quantum and data center news remain strong. Is most of the upside already priced in, or is it not yet reflected?
Most Popular Narrative: 25% Undervalued
Mitsubishi Electric last closed at ¥5,149, while the most followed narrative sets fair value closer to ¥6,892. This points to a sizeable valuation gap that investors are now weighing against the recent pullback and fresh project wins.
Sustained growth in the Infrastructure and Factory Automation Systems businesses is underpinned by robust global demand for automation, digital transformation, and AI-driven investments in manufacturing and logistics. Recent record-high quarterly revenues and margins signal that Mitsubishi Electric is well-positioned to capture further top-line and operating profit expansion as industrial automation accelerates.
See why 5 investors see Mitsubishi Electric as 25% undervalued.
Result: Fair Value of ¥6,892 (UNDERVALUED)
Still, the bullish Mitsubishi Electric story can crack if lower cost Asian rivals squeeze pricing in factory automation, or if US China trade frictions raise tariff and supply chain costs.
Find out about the key risks to this Mitsubishi Electric narrative.
Another Angle On Mitsubishi Electric’s Value
The latest narrative leans on analyst targets and earnings forecasts to argue Mitsubishi Electric is about 25% undervalued. A different approach tells a cooler story. Our DCF model, which prices the shares off projected future cash flows, points to a value of ¥4,049.27, below the recent ¥5,149 share price and therefore screens as overvalued.
That gap between a bullish earnings-based fair value and a more conservative cash flow view leaves a simple question: Which set of assumptions do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
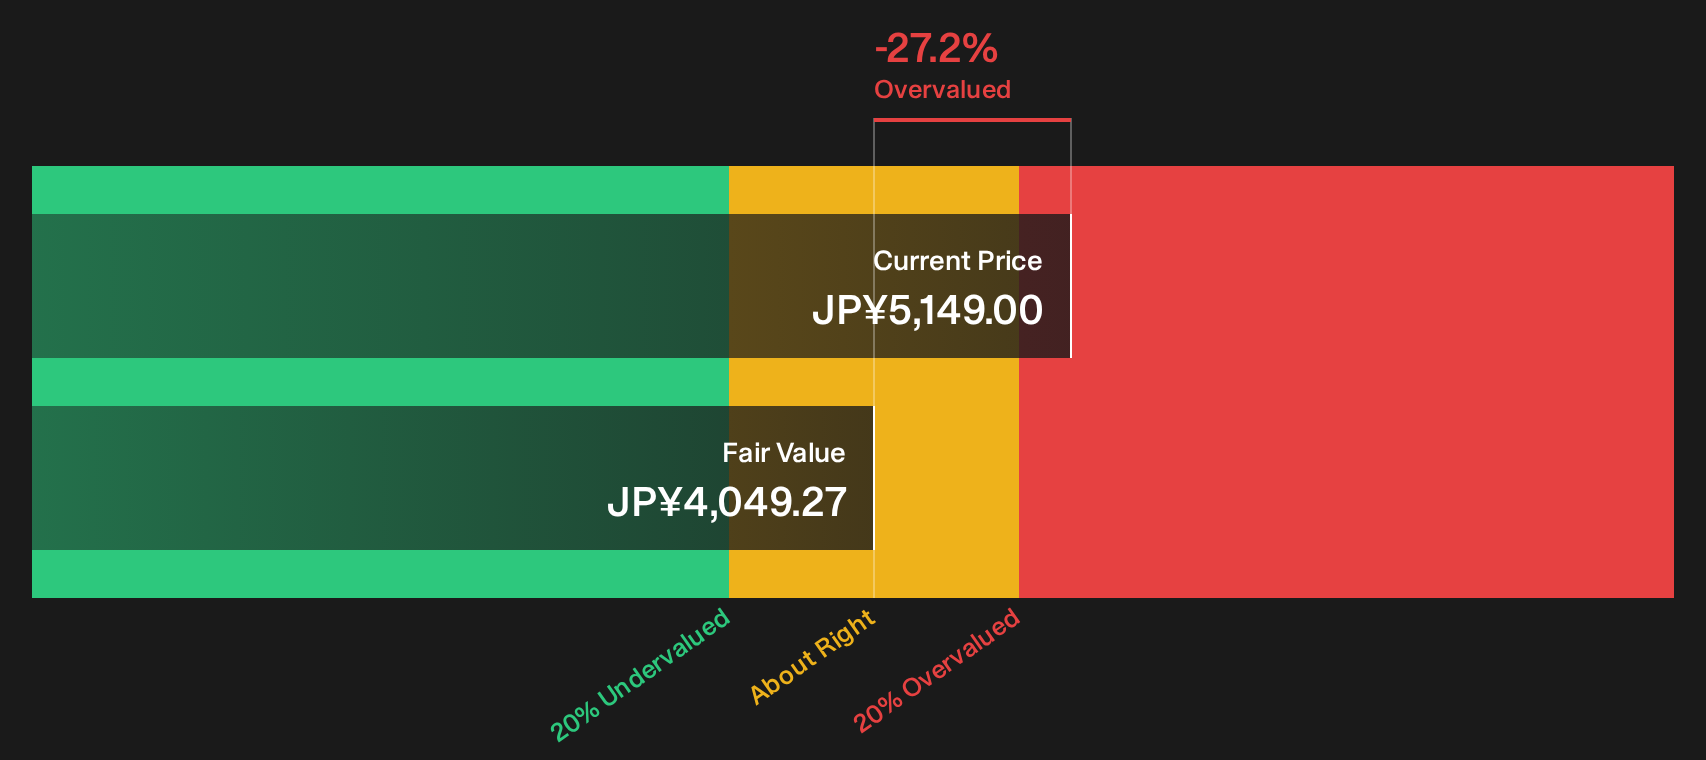
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsubishi Electric for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split view on Mitsubishi Electric has you torn, use that tension as a prompt to act quickly, review the underlying data, and consider both perspectives by studying the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Mitsubishi Electric?
If Mitsubishi Electric has sharpened your focus on quality opportunities, do not stop here. Use curated screeners to surface other stocks that match your standards and time frame.
- Target dependable income streams by scanning companies that meet your yield and stability criteria through the 15 dividend fortresses.
- Hunt for quality at a discount by reviewing companies flagged as potential bargains using the 17 high quality undervalued stocks.
- Prioritise resilience and capital protection by filtering for lower risk profiles with the 12 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com