
How Investors May Respond To PUMA (XTRA:PUM) Chief Commercial Officer Steps Down
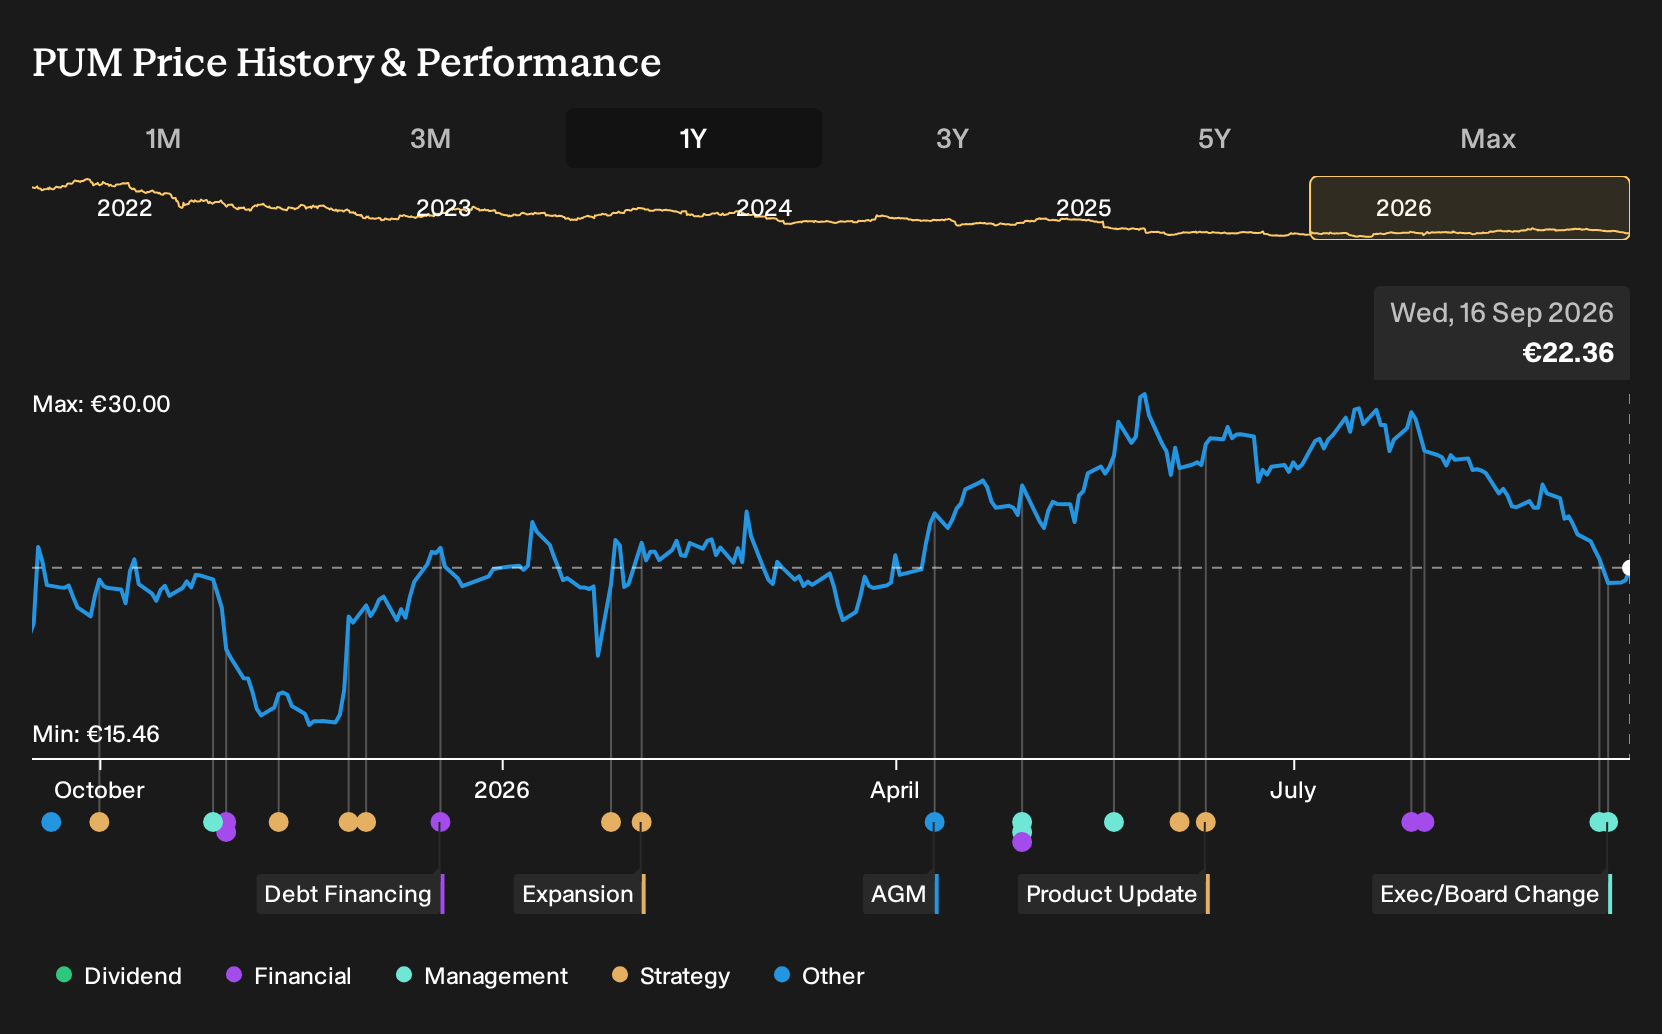
- PUMA announced that long serving Chief Commercial Officer Matthias Baeumer stepped down from the Management Board in September 2026. CEO Arthur Hoeld temporarily took over sales oversight, and industry veteran Steve Cecchini joined as Senior Vice President Sports Marketing.
- The reshuffle concentrates commercial and marketing responsibility around the CEO at a time when PUMA is still working through a multiyear transformation with significant wholesale, inventory and channel execution demands.
- We will look at how PUMA’s investment narrative is affected by Matthias Baeumer’s departure and the consolidation of commercial oversight.
PUMA Investment Narrative Recap
To own PUMA, you need to be comfortable with a multiyear clean up that is pressuring sales while aiming for higher quality revenue from better wholesale segmentation and more direct to consumer. In the near term, the key issue remains execution on the three year transformation while managing high working capital and debt so cash generation does not get squeezed.
The CCO exit concentrates commercial and marketing oversight with Arthur Hoeld at a time when wholesale partners are already cautious and Greater China faces ANTA related disruption. If the transition runs smoothly, the short term catalyst around distribution reset and brand heat remains intact. If it complicates partner relationships or product focus, the main risk increases.
The appointment of Steve Cecchini as Senior Vice President Sports Marketing is tightly linked to this leadership shift. PUMA is leaning on high visibility partnerships in football, HYROX, running and motorsport, and Cecchini brings recent experience managing complex global football deals. Effective sports marketing is central to rebuilding demand for NITRO and other premium performance lines.
For you as an investor, the operational question is whether this hire improves execution on existing catalysts rather than adds new ones. Better partnership management and sharper product storytelling could support the planned move away from discounting and mass merchants, which matters when PUMA is carrying about €2.1b of inventory and is working to stabilise margins.
PUMA's current analyst script points to revenues of €8.0b and earnings of €202.4m by 2029, based on an assumed 3.8% yearly increase in revenue and an earnings swing of about €839.8m from a loss of €637.4m today.
Uncover why PUMA's fair value indicates a 31% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses less on PUMA’s brand push and more on earnings quality. The most cautious analysts, who were already modelling revenue of about €7.9b and earnings of €146.3m by 2029, see a slower margin recovery. They worry that leadership changes could add fresh execution questions and that this might shift those already downbeat forecasts further.
Explore 6 other PUMA fair value estimates, including one that suggests it could be worth just €22.30.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your PUMA research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PUMA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PUMA's overall financial health at a glance.
Looking for more investment ideas beyond PUMA?
If the PUMA story has sharpened your thinking and you want to line it up against a broader watchlist, the Simply Wall St Screener can help you quickly surface other stocks that fit your preferred mix of quality, risk and income.
- If capital preservation comes first for you, start with companies that screen well on resilience using the 104 resilient stocks with low risk scores.
- If you care most about strong fundamentals and cleaner balance sheets, filter for sturdier businesses through the list of solid balance sheet and fundamentals (194 results).
- If income is a priority, focus on higher yielding payers by checking out the 161 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com