
Canadian Utilities (TSX:CU) Lifts Dividend As Regulated Growth Story Keeps Undervaluation In View
Canadian Utilities (TSX:CU) has reaffirmed its focus on regulated power and gas networks and energy transition projects, while lifting its dividend again for 2026, despite weaker net income reported in the prior year.
Recent trading has been choppy. Canadian Utilities’ share price slipped 5.88% over the past month and is down 2.26% over the last quarter. It still carries an 18.16% year to date share price return and a 40.79% 1 year total shareholder return, indicating momentum that has cooled in the short term but remained stronger over a longer stretch as investors respond to the dividend increase and renewed focus on regulated and energy transition assets.
Scan beyond Canadian Utilities and compare it with a hand picked 2 dividend fortresses that are also leaning on income strength and regulated cash flows.
The pullback raises a simple tension: Are investors reassessing Canadian Utilities’ fundamentals, or has sentiment swung after a strong multi year run and fresh dividend news, leaving the valuation out of sync with the business?
Most Popular Narrative: 7.6% Undervalued
On the most followed view of Canadian Utilities, the fair value of CA$54.71 sits above the last close at CA$50.56. This puts the recent pullback against a story that still leans slightly in favour of upside.
Substantial investment in grid modernization and expansion, including major projects like the Central East Transfer-Out and the 90% contracted Yellowhead pipeline, positions Canadian Utilities to capitalize on rising power and gas demand from electrification and industrial growth. This supports future increases in rate base and long-term revenue growth. Proactive investments in infrastructure resiliency, such as wildfire mitigation, composite poles and undergrounding, address the need for grid reliability in the face of climate-driven severe weather. These measures improve asset protection and can justify higher rate-based capital spending, with positive impacts on allowed returns and long-term earnings.
See why 39 investors see Canadian Utilities as 8% undervalued.
Result: Fair Value of CA$54.71 (UNDERVALUED)
Still, the story around Canadian Utilities can change quickly if Alberta regulators push through unfavourable rulings or if large capital projects strain debt and future cash flows.
Find out about the key risks to this Canadian Utilities narrative.
Another View On Canadian Utilities’ Valuation
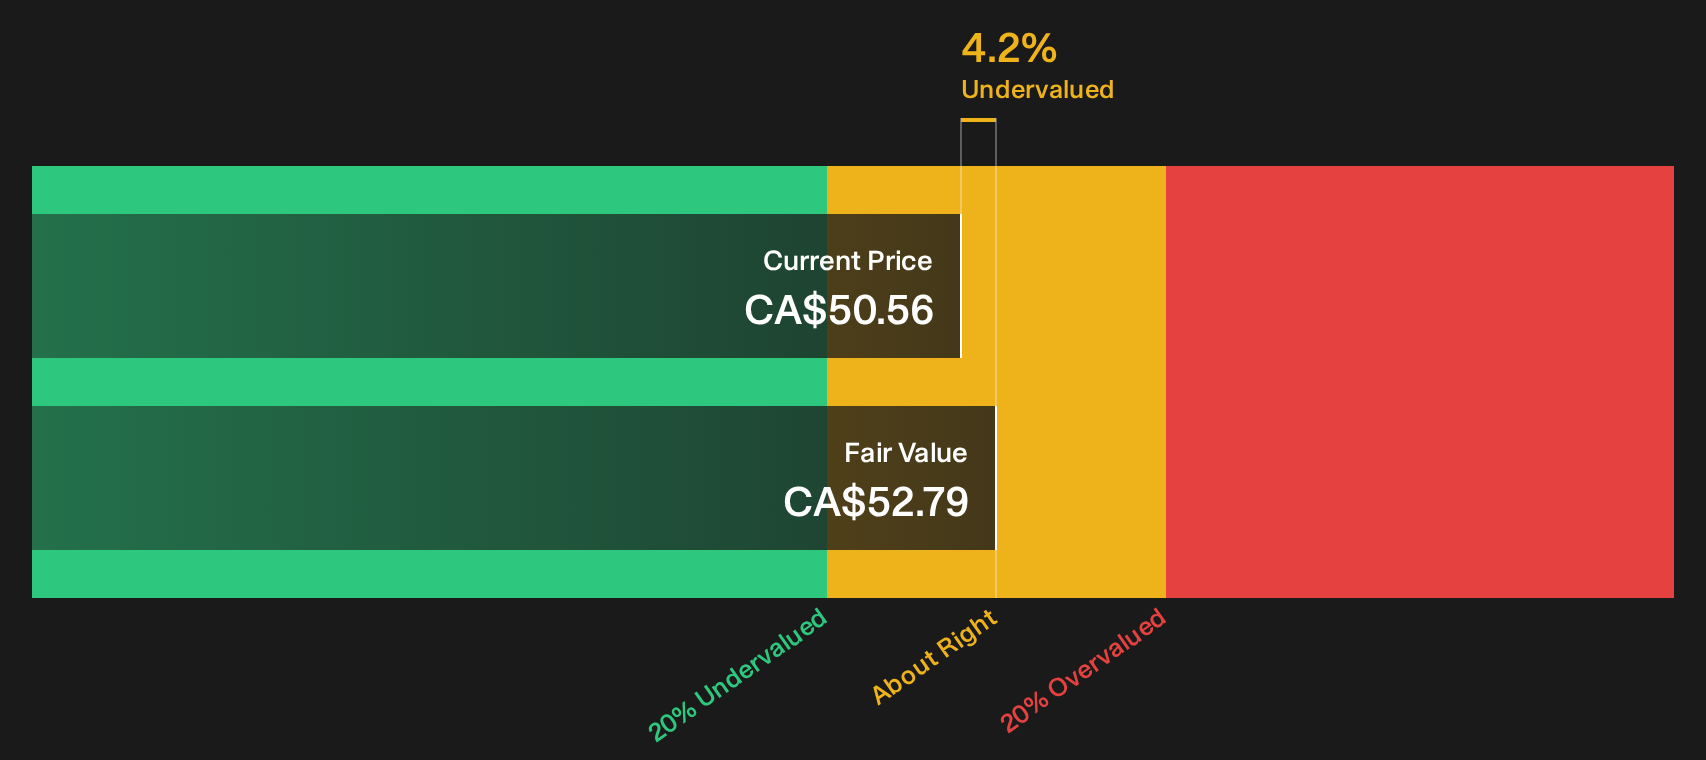
Analysts see Canadian Utilities as about 4.2% below an estimated fair value of CA$52.79 using the SWS DCF model, which also points to the shares as undervalued. If both the DCF work and the 7.6% discount to fair value align, the main debate may be more about the forecasts that feed those models than about the models themselves.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Canadian Utilities rarely stay undecided for long. Move quickly, review the numbers yourself, and weigh the 2 key rewards and 4 important warning signs.
Looking for more Canadian Utilities investment ideas?
If you want a stronger watchlist beyond Canadian Utilities, use the Simply Wall St screener to spot fresh opportunities before the crowd catches on.
- Target dependable income streams by scanning a curated 2 dividend fortresses that focus on resilience and consistency.
- Hunt for potential mispricing with a 4 high quality undervalued stocks that combine solid fundamentals with attractive starting valuations.
- Protect your downside first by concentrating on a 1 resilient stocks with low risk scores that prioritize balance sheet strength and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com