
Is JFK Lounge Opening Altering The Investment Case For Air France KLM (ENXTPA:AF)?
- In September 2026, Air France-KLM confirmed that Air France shifted all New York-JFK flights to the new Terminal One and opened its largest international lounge, a two-level, 29,000+ square foot space serving premium and eligible SkyTeam travelers.
- The move concentrates high-yield traffic in a flagship hub. This may strengthen Air France-KLM’s premium offering and support loyalty among La Première, Business and Flying Blue Elite Plus customers.
- We will now look at how Air France-KLM’s investment narrative could be shaped by this new premium lounge hub at JFK.
What Is Air France-KLM's Investment Narrative?
To own Air France-KLM, you need to buy into a fairly simple idea. This is a full service carrier trying to squeeze more value from high paying travelers while keeping a multi brand, multi continent network running reliably. The new JFK Terminal One lounge fits that story. It is an operational bet on premium demand, pricing power on core transatlantic routes, and stickier Flying Blue loyalty, rather than a move that suddenly changes the near term numbers on a €34.2b revenue base.
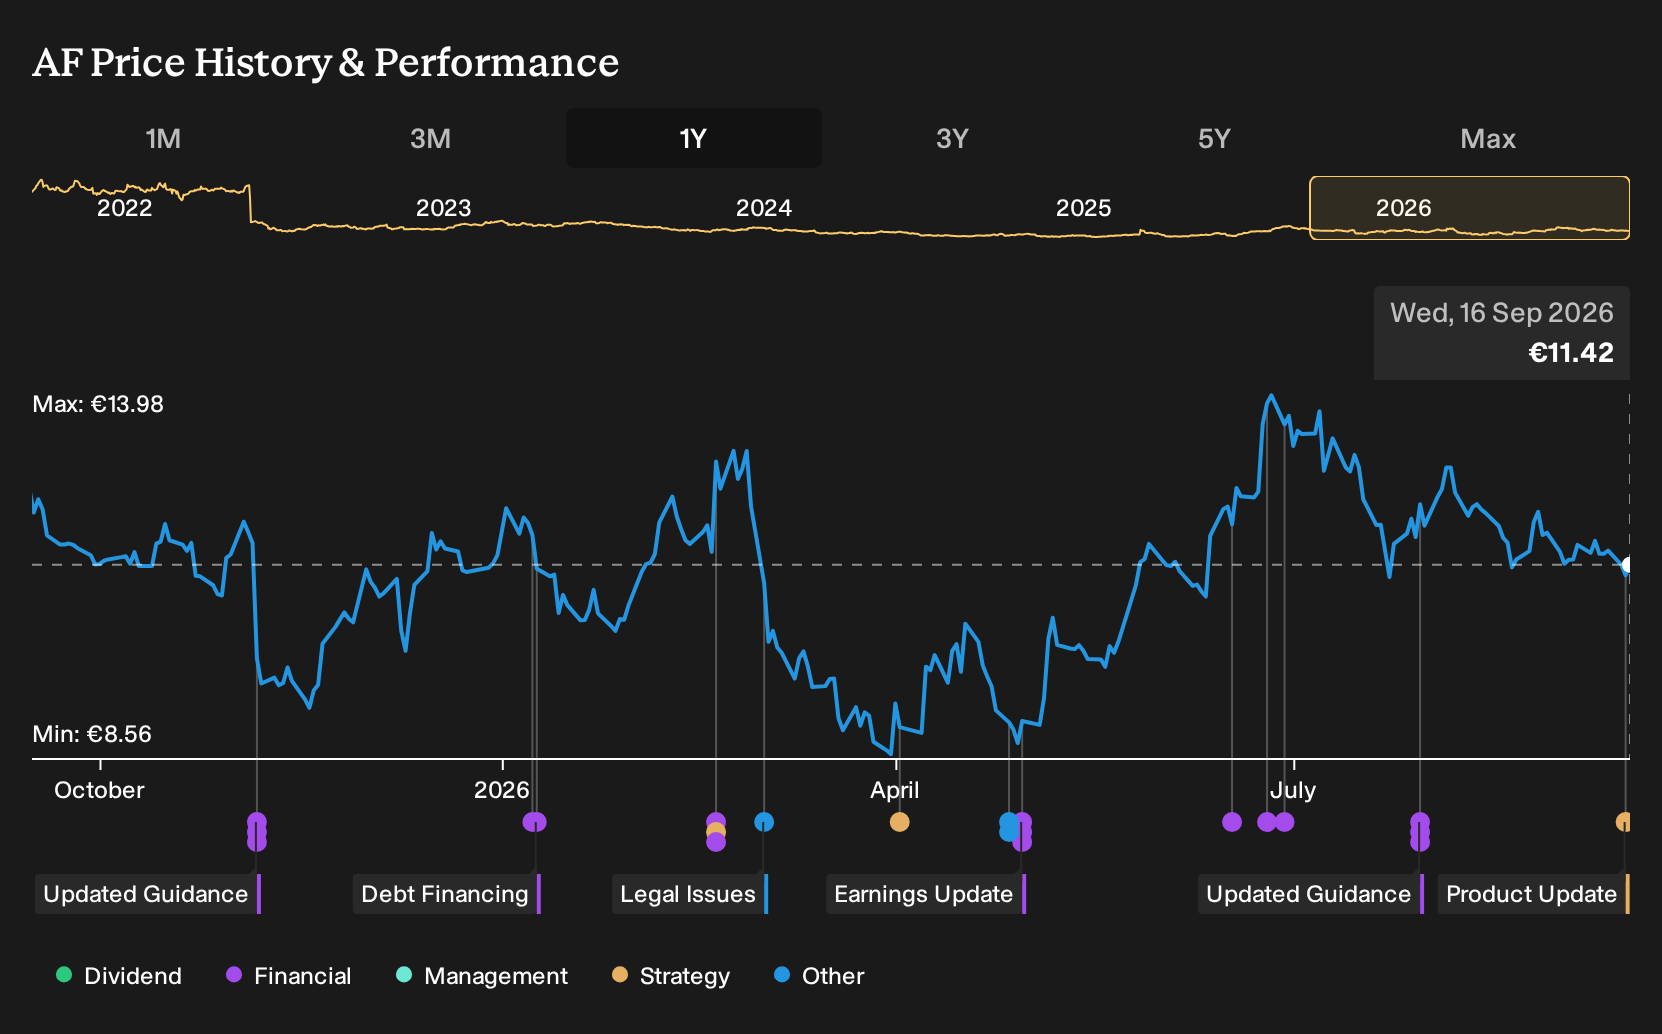
In the short term, the bigger questions remain execution on capacity, cost discipline in a capital intensive fleet, and how steadily the group converts that 3.2% net margin into consistent free cash flow while carrying higher risk funding and debt. The stock has lagged over 1, 3 and 5 years even with earnings growth and a low 2.8x P/E, so this lounge investment reads more as a signal of premium focus than a material catalyst on its own.
Still, there is one operational pressure point that can quickly matter more than any new lounge if it moves the wrong way...
There's only one way to know the right time to buy, sell or hold Air France-KLM. Head to Simply Wall St's company report for the latest analysis of Air France-KLM's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community contributes two fair value estimates for Air France-KLM, stretching from €12.67 to about €57.69. That is a wide gap for the same stock. These views were formed before the JFK lounge launch and terminal move, so you should compare them with how you think premium travel spending and network quality could influence future performance.
Explore another Air France-KLM fair value estimate, including one that suggests it could be worth just €12.67.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Air France-KLM research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Air France-KLM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Air France-KLM's overall financial health at a glance.
Looking For More Investment Ideas Beyond Air France-KLM?
Once you have a view on Air France-KLM, it can help to compare it with other companies that share some of the same qualities you care about, whether that is value, resilience, or income. The Simply Wall St Screener is a quick way to surface stocks that match those preferences so you can build a watchlist that fits your own risk and return targets.
- For investors hunting for income resilience, check out 161 dividend fortresses that combine higher yields with a focus on stability.
- If capital preservation matters most to you, start with 104 resilient stocks with low risk scores that score well on Simply Wall St’s risk metrics.
- When you want quality businesses that the market may be overlooking, scan through 619 high quality undiscovered gems with strong fundamentals and room to get noticed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com