
How Investors Are Reacting To Nokian Tyres Stock As New Winter Tire Launches
- Nokian Tyres plc marked the 90th anniversary of its Hakkapeliitta winter tire family with the launch of the Nokian Tyres Hakkapeliitta 01. The tire offers On Demand Grip, lower road wear, reduced noise and improved ice and wet grip compared with the Hakkapeliitta 10.
- The Hakkapeliitta 01 reflects Nokian Renkaat Oyj’s effort to push higher value winter products. It uses adaptive stud technology and comfort features to support its premium positioning in demanding cold weather segments.
- We will now look at how Nokian Renkaat Oyj’s investment narrative could be influenced by the Hakkapeliitta 01 On Demand Grip launch.
Nokian Renkaat Oyj Investment Narrative Recap
To own Nokian Renkaat Oyj, you need to believe the tire maker can keep shifting its mix toward higher value winter, all season and 18 inch plus products while executing on its 2029 targets of €1.8b to €2b in net sales and stronger margins. The key near term swing factor is execution in Passenger Car Tyres, which recently moved from a segment loss to a 5.5% operating margin on higher net sales.
The main risk is that weaker demand in Central Europe and North America or softer pricing power slows that margin plan and leaves interest coverage tight. The Hakkapeliitta 01 launch helps the product story but does not, on its own, change the biggest short term catalyst or the core risk around earnings progression and balance sheet headroom.
The Hakkapeliitta 01, with On Demand Grip and lower road wear, fits directly into Nokian Renkaat Oyj’s push to raise the share of premium winter and 18 inch plus tires, which already accounts for 51% of sales by value. It is one of several recent product launches, alongside lines such as Snowproof 3P, that support the company’s mix upgrade efforts.
For catalysts, this matters because the long term plan to lift segment EBITDA by €220 million and reach over 24% margin by 2029 leans heavily on pricing and mix, not just volume. The operational test is straightforward. Products like Hakkapeliitta 01 need to hold their price points even if European and North American tire markets stay soft, or the uplift analysts model into future earnings may prove hard to reach.
Nokian Renkaat Oyj's current narrative points to forecast revenues of €1.8b and consensus earnings of €150.8 million by 2029, built on analyst assumptions of 7.5% yearly revenue growth and an earnings uplift of about €131 million from earnings today of €19.5 million.
Discover why Nokian Renkaat Oyj's fair value indicates a 16% potential downside to its current price, which leaves little room for error.
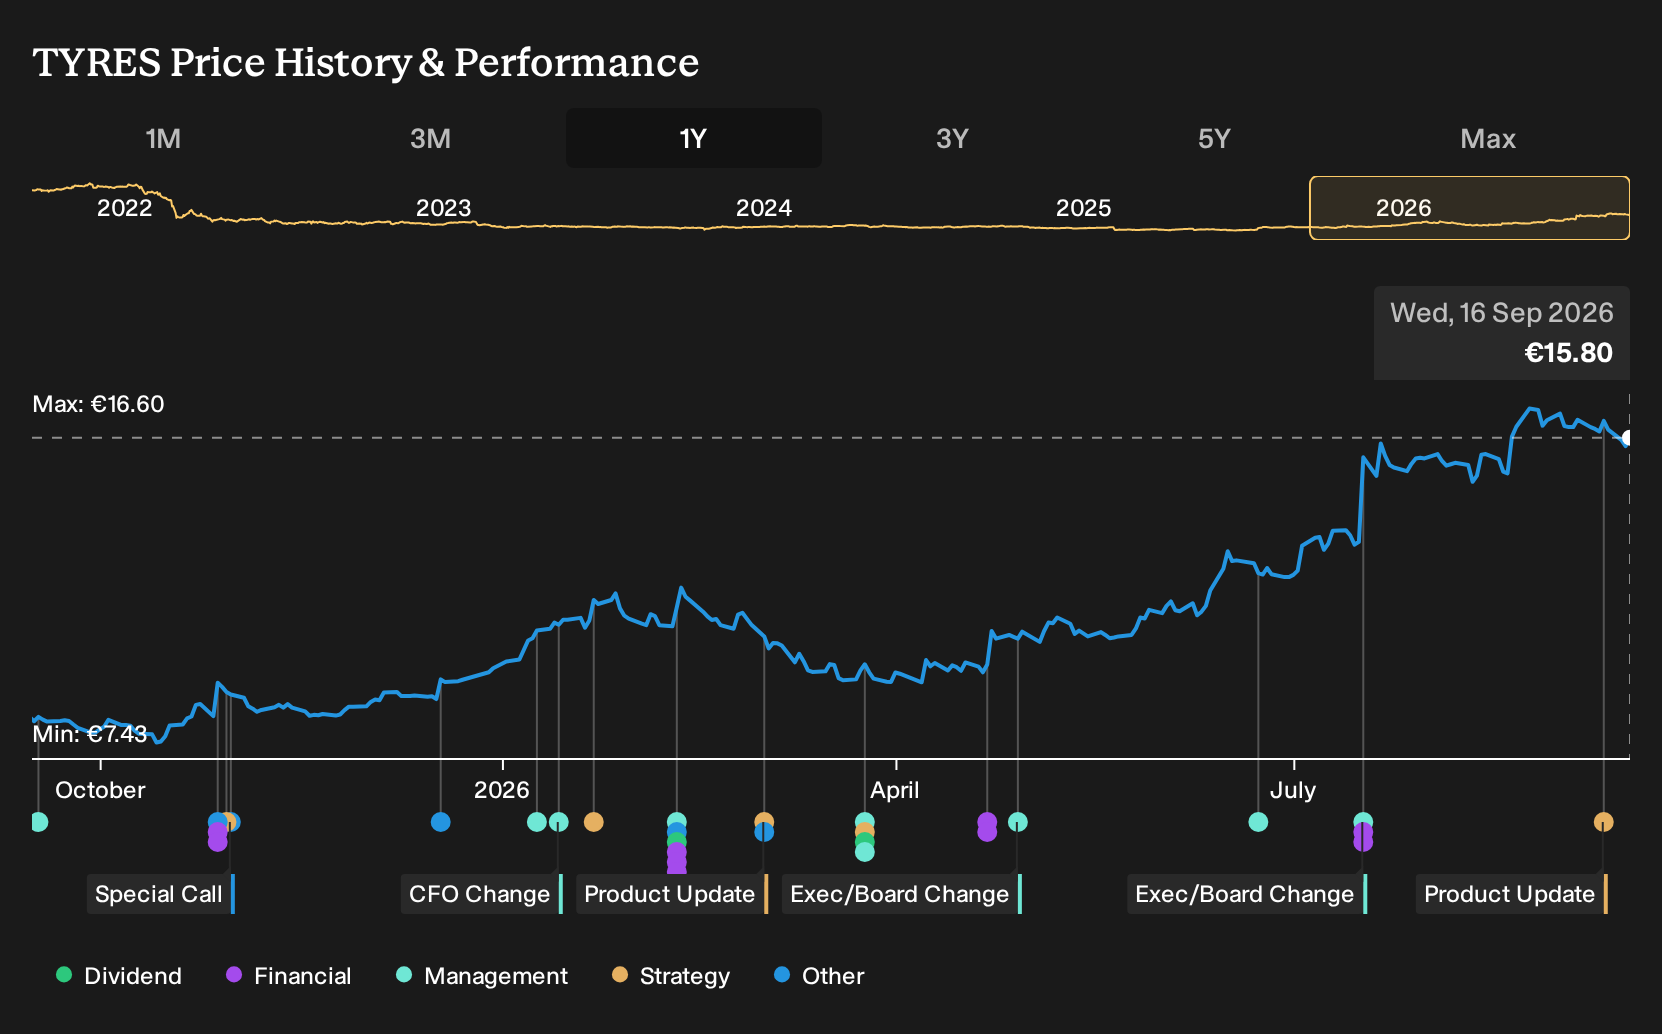
Exploring Other Perspectives
For Nokian Renkaat Oyj, the bearish twist is earnings power. The most cautious analysts were working off about €1.8b revenue and only €137.0 million in earnings by 2029, with a lower 7.8% margin view. They see flat tyre demand and higher R&D costs as a drag, although the Hakkapeliitta 01 launch could eventually reshape that story.
Explore 4 other Nokian Renkaat Oyj fair value estimates, including one that suggests as much as 16% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nokian Renkaat Oyj research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nokian Renkaat Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nokian Renkaat Oyj's overall financial health at a glance.
Looking For More Ideas Beyond Nokian Renkaat Oyj?
If you want to stress test your Nokian Renkaat Oyj view against other opportunities, a quick pass through the Simply Wall St Screener can surface stocks with different risk and reward profiles that still match your style.
- For investors who care most about resilience and capital protection, scan a curated set of 104 resilient stocks with low risk scores that keep overall risk scores in check.
- If value and quality sit at the top of your checklist, compare Nokian Renkaat Oyj with a 186 high quality undervalued stocks that pair solid balance sheets with attractive pricing.
- For those hunting for income ideas, weigh your view on Nokian Renkaat Oyj against a focused 161 dividend fortresses that blends higher yields with stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com